Breaking a mortgage contract means ending your existing mortgage before the agreed term reaches its maturity date. A homeowner might do this because they are selling the property, refinancing for a better rate, consolidating debt, moving to another lender, separating from a partner, or changing the mortgage structure before renewal. The mortgage does not simply disappear when you decide to leave, because the lender still needs to receive the amount required to discharge the existing obligation according to the contract.
For Canadian homeowners with a closed mortgage, the largest surprise can be the prepayment charge associated with leaving before the term ends. Depending on the mortgage type and lender’s contractual formula, that charge can range from a relatively manageable amount to many thousands of dollars, especially when a fixed-rate mortgage is being broken well before maturity. The Financial Consumer Agency of Canada’s guidance on breaking your mortgage contract explains that breaking a closed mortgage can result in a prepayment penalty and other fees, while open mortgages generally provide more flexibility for early repayment.
The cost alone does not determine whether breaking the mortgage is a mistake. A homeowner paying a substantial penalty today can still improve their financial position if the replacement mortgage produces enough savings, if selling the property solves a more important household need, or if restructuring expensive debt reduces a serious cash-flow problem. The opposite can also happen, because a refinance that looks attractive from its advertised rate can become financially weak once the break penalty, legal expenses, discharge costs, new mortgage fees, and the remaining term of the old loan are included.
The strongest decision in 2026 therefore begins with the mortgage you already have rather than the offer trying to replace it. Find the exact payout amount, determine how the prepayment charge is calculated, identify how much time remains until maturity, and compare the full cost of leaving with the financial benefit expected from the new arrangement. Once those numbers are visible together, breaking a mortgage contract becomes a measurable decision rather than an emotional reaction to today’s interest rates.
What Does Breaking a Mortgage Contract Actually Mean?
A mortgage contract sets out the obligations between the borrower and lender for a defined term, which is different from the mortgage’s full amortization period. A borrower might have a 25-year amortization but only a five-year mortgage term, meaning the interest rate and contractual conditions apply for the five-year period before renewal or another mortgage arrangement is needed. Breaking the contract occurs when the borrower ends that term before the scheduled maturity date.
The mortgage usually needs to be paid out when the contract is broken. If the homeowner is refinancing, the replacement lender typically provides funds used to satisfy the existing mortgage at closing. If the homeowner is selling, the existing mortgage is generally discharged from the sale proceeds so the buyer can receive the property under the closing arrangement.
Breaking the contract should therefore be distinguished from simply making an ordinary mortgage payment or waiting for renewal. Renewal occurs when the current term naturally reaches maturity and the remaining mortgage balance needs another term or lender arrangement. Breaking occurs earlier, which is why a closed mortgage can impose a financial consequence for leaving before the lender’s contracted period has ended.
Mortgage Break Cost Calculator
Estimate the cost of leaving your current mortgage, compare the payment change from a replacement mortgage, and see whether breaking today or waiting until renewal looks stronger under the numbers you enter.
Current Mortgage
Break Cost
The result will compare the switching cost with the estimated principal-and-interest payment change.
Break Now vs Wait Until Renewal
This isolates the penalty avoided by waiting and the payment savings you would give up before renewal.
Renewal Scenario
This compares the entered renewal-rate scenario with the new mortgage available today. Future rates are unknown.
Why Do Homeowners Break a Mortgage Early?
Homeowners rarely wake up one morning and decide that paying a mortgage penalty sounds appealing. Something usually changes in the household, property, lending market, or financial plan strongly enough that the existing mortgage no longer fits. Understanding the reason matters because the value of leaving early depends on what the new arrangement is expected to solve.
A sharp decline in available mortgage rates is one common reason. Someone paying a materially higher contractual rate may consider refinancing into a cheaper mortgage even after accounting for the break charge. The new rate needs to create enough savings over the period the homeowner expects to keep the replacement mortgage to justify paying the old lender’s exit cost.
Selling the home is another common trigger. A job relocation, relationship change, growing family, downsizing decision, or financial hardship can make selling necessary even when the current mortgage term has years remaining. In those circumstances, the break penalty is part of the cost of changing the household’s housing situation rather than merely a refinance expense.
Debt restructuring can also motivate the decision. A homeowner with significant high-interest consumer debt might consider refinancing and using available home equity to reorganize those obligations, although converting unsecured debt into mortgage debt creates its own long-term risks. The mortgage penalty should be included in that restructuring calculation rather than treated as an incidental fee that does not affect the economics.
Open Mortgage vs Closed Mortgage When You Leave Early
The difference between an open and closed mortgage becomes especially important when the borrower wants to repay the mortgage early. Open mortgages generally allow the borrower to make large prepayments or pay off the balance without the same type of prepayment charge that can apply to a closed mortgage. The additional flexibility normally comes with a pricing trade-off, which is one reason many borrowers choose closed mortgages when they do not expect to leave early.
Closed mortgages usually restrict how much principal can be prepaid without triggering the contractual charge. The agreement may still provide annual prepayment privileges, increased payment options, or lump-sum privileges that allow the borrower to reduce principal without breaking the entire mortgage. Those privileges vary significantly between lenders and products, so the original mortgage documents remain important even when general rules are familiar.
A borrower who expects a high probability of selling or refinancing well before maturity should therefore consider flexibility when selecting the mortgage in the first place. A slightly lower rate attached to a restrictive contract can become expensive if the household needs to leave early. Mortgage pricing should be evaluated alongside exit flexibility rather than assuming the lowest rate always creates the lowest total cost.
How Much Does It Cost to Break a Mortgage in Canada?
There is no single dollar amount because the cost depends on the mortgage contract, balance, rate, remaining term, mortgage type, lender methodology, and the date on which the mortgage is actually paid out. The prepayment charge can be the largest component, but it is not necessarily the only amount involved. Borrowers should request an up-to-date payout statement rather than estimating the decision from the principal balance shown in online banking.
For many closed variable-rate mortgages, a lender may use an amount based on approximately three months of interest, although borrowers should verify the exact contract rather than assuming that treatment applies universally. Fixed-rate closed mortgages can be more complicated because lenders may compare three months of interest with an interest rate differential, often called IRD, and apply the amount required by the mortgage agreement. The Financial Consumer Agency of Canada’s explanation of mortgage prepayment penalties provides a useful official starting point for understanding the two commonly encountered approaches.
Additional costs can include discharge or administrative expenses, legal fees associated with the new transaction, appraisal expenses, registration costs, and new mortgage charges depending on the structure. Some of those costs relate to leaving the existing mortgage, while others belong to obtaining the replacement financing. They should be separated when reviewing the transaction but combined when deciding whether the complete change creates financial value.
The Two Common Prepayment Penalty Methods
The prepayment charge deserves particular attention because different calculation methods can produce dramatically different results. A borrower who hears that the penalty is simply “three months of interest” can be surprised when the lender’s fixed-rate mortgage calculation produces a much larger amount. The applicable mortgage contract and lender calculation should therefore be confirmed before the homeowner commits to another mortgage.
| Penalty Method | General Idea | What the Borrower Should Check |
|---|---|---|
| Three months of interest | The charge is generally based on approximately three months of interest on the applicable mortgage amount under the lender’s contractual calculation. | Confirm the balance used, contractual interest rate, lender formula, and whether available prepayment privileges reduce the amount. |
| Interest rate differential | The calculation attempts to measure a difference between the mortgage rate and a comparison rate used under the lender’s contract for the remaining term. | Ask which comparison rate is being used, how discounts are treated, and request the lender’s actual calculation rather than trying to reproduce it from a generic formula. |
| Other contractual costs | Discharge, administration, legal, registration, or transaction expenses may exist in addition to the prepayment charge. | Request an itemized payout amount and separate lender exit costs from the expenses associated with the replacement mortgage. |
The table should be treated as a decision framework rather than a substitute for the mortgage contract. A fixed mortgage from one institution can calculate IRD differently from another institution because the contractual comparison methodology may differ. That variation is one reason online penalty estimates should be treated as preliminary until the lender provides an official payout figure.
What Is Three Months of Interest?
A three-month-interest penalty sounds simple because the basic concept is easy to understand. If a lender uses the mortgage balance and contractual rate to estimate approximately three months of interest, the resulting charge represents the income associated with that short period. The actual calculation should still come from the lender because the contract can specify how the amount is determined.
Suppose the mortgage balance is $400,000 and the annual rate used for a simplified illustration is 5%. One year of simple interest on that balance would be approximately $20,000, while three months would be approximately $5,000 under the simplified calculation. The lender’s actual figure can differ based on the contractual method, timing, balance used, and any prepayment privileges that apply.
A homeowner should therefore avoid treating a calculator result as the amount that will appear at closing. The useful purpose of an estimate is to identify whether the penalty is likely to be hundreds, thousands, or tens of thousands of dollars before a formal payout statement arrives. The official lender figure should replace the estimate before the homeowner makes the final break-or-stay decision.
What Is the Interest Rate Differential?
Interest rate differential calculations are more complicated because they attempt to compare the economics of your existing mortgage with another rate over the remaining term. A lender may compare your contractual mortgage rate against a current comparison rate for a mortgage with a term similar to the time remaining on your existing contract. The specific formula can also account for discounts or other contractual details, which is why two lenders can produce different penalties for apparently similar mortgages.
Suppose you have several years remaining on a fixed mortgage carrying a higher rate than the lender’s current comparable rate. The lender may face the prospect of receiving your money back early and reinvesting it at a lower rate, which is part of the economic idea behind IRD. The calculation attempts to quantify that difference according to the contract rather than simply charging three months of interest.
For borrowers, the practical lesson is to request the calculation rather than merely the final number. Ask what comparison rate is being used, whether your original mortgage received a discounted rate, what balance is included, and how much time remains in the calculation. A five-digit prepayment charge deserves more explanation than a single line saying “mortgage penalty.”
Why IRD Penalties Can Be So Large
A fixed-rate mortgage can create a particularly large penalty when the contractual rate is significantly higher than the lender’s comparison rate and substantial time remains before maturity. A large mortgage balance magnifies the effect because the rate difference applies across more principal. The same homeowner can therefore face a very different charge depending on whether they leave with three months remaining or three years remaining.
This timing effect is why a refinance decision should always include the maturity date. An attractive rate difference can justify breaking a mortgage when several years of savings remain ahead, while the same refinance may make little sense when renewal is only a few months away. Waiting becomes more valuable as the remaining contract period shrinks and the potential break cost falls.
The lender’s calculation can also change as market rates move. A homeowner who requests a penalty estimate today and closes several weeks later can receive a different final payout figure because the relevant rates or remaining period may have changed. Ask how long the quoted penalty estimate remains valid and request an updated figure close to the actual transaction date.
Your Prepayment Privileges May Reduce the Cost
Many closed mortgages allow some amount of principal to be prepaid without penalty during each year of the term. The privilege may be expressed as a percentage of the original mortgage amount, current balance, or another contractual basis, and the mortgage may also allow payment increases. These features can potentially reduce the balance exposed to the penalty when used correctly before the mortgage is broken.
Suppose a homeowner is permitted to make a significant lump-sum payment without charge and has enough cash to use that privilege safely. Reducing the balance before requesting the final payout can potentially lower the amount used in the penalty calculation, depending on the lender’s rules and timing. The strategy only works when the contract permits it and the household can use the cash without damaging necessary reserves.
Do not assume unused privileges can always be applied retroactively or immediately before discharge. Some lenders impose timing rules, annual limits, or restrictions around how prepayments are processed. Confirm the available privilege and how it would affect the actual break charge before transferring money.
Ask for the Mortgage Payout Statement Before Comparing Offers
The mortgage balance visible in online banking is not enough for a break decision. The amount required to discharge the mortgage can include accrued interest, the prepayment charge, and other applicable lender costs, which means the true payout can be materially higher than the principal balance. A replacement lender needs this more complete figure when determining how much financing is required.
Requesting the payout statement early also reveals whether the estimated penalty is significantly different from what you expected. Discovering a $15,000 break charge after accepting another mortgage offer creates unnecessary pressure, while discovering it during the comparison stage gives you time to reconsider the transaction. The payout figure is one of the most important inputs in any break-cost calculation.
If the lender gives only a total figure, request an itemized explanation. Separate principal, accrued interest, prepayment penalty, discharge costs, and other identifiable charges so you understand what disappears if you wait and what would remain regardless of timing. That distinction becomes especially valuable when comparing breaking the mortgage now with staying until renewal.
Breaking a Mortgage to Get a Lower Rate
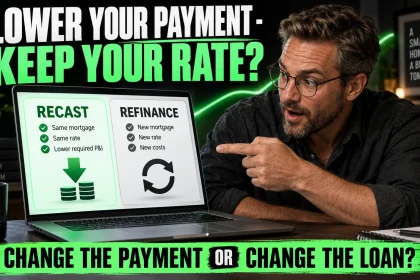
A lower interest rate is one of the most common reasons to consider breaking a mortgage. The obvious attraction is reduced interest cost and potentially a lower monthly payment, but the difference in rates should not be treated as the amount you “save.” The penalty and replacement mortgage costs need to be recovered before the lower rate creates a meaningful net benefit.
Suppose breaking the mortgage creates $12,000 of combined penalty and transaction costs, while the new mortgage reduces the monthly payment by $350. A simplified break-even calculation produces approximately 34.3 months, meaning the homeowner would need close to three years of $350 monthly savings to recover $12,000 before considering differences in principal repayment. If the homeowner expects to sell or refinance again in two years, the transaction becomes difficult to justify using that simplified comparison.
A stronger analysis also compares the outstanding mortgage balance after the same future period. The new mortgage might lower the payment partly because the amortization has been extended, which means the borrower could owe more after five years despite making smaller payments. The mortgage refinance guide explains why monthly savings and total financial improvement should be evaluated separately.
Breaking a Mortgage to Consolidate Debt
Homeowners carrying high-interest credit-card balances, personal loans, or other consumer debt sometimes consider refinancing the mortgage and using available equity to repay those obligations. The interest rate on mortgage debt can be substantially lower than the rate charged on unsecured consumer debt, which can create immediate payment relief. The risk is that debt previously scheduled to disappear over a shorter period becomes secured against the home and can remain outstanding for decades.
The break penalty makes the comparison more demanding because the household is paying an additional cost before the debt consolidation even begins. If $8,000 of mortgage penalty is incurred to restructure $40,000 of consumer debt, that cost represents a significant percentage of the amount being reorganized. The refinance needs to improve enough of the overall household debt position to justify both the mortgage exit cost and the new transaction costs.
Behaviour matters as much as the rate calculation. Consolidating credit cards into the mortgage while continuing to accumulate new card balances can leave the homeowner with a larger mortgage and renewed consumer debt several years later. The refinance should therefore be connected to a realistic repayment and spending plan rather than treated as a periodic way to clear available credit.
Breaking Your Mortgage Because You Are Selling the Home
Selling can force the mortgage question even when refinancing would otherwise make no sense. If the mortgage cannot be transferred to the next property or otherwise accommodated under the lender’s available options, the current mortgage may need to be discharged from the sale proceeds. The prepayment charge then reduces the net amount the homeowner receives from the transaction.
This cost should be estimated before setting expectations for the next purchase. A homeowner might believe they will receive $200,000 of usable equity from the sale, only to discover that mortgage penalties and transaction costs materially reduce that amount. The difference can affect the down payment available on the next home.
Ask the lender whether the mortgage can be ported before assuming it must be broken. A portability feature may allow the existing mortgage, or an adjusted version of it, to move with the borrower to another property under the lender’s qualification and product conditions. Porting can sometimes preserve favourable mortgage terms and reduce the break cost, although it should still be compared with taking a completely new mortgage.
What Is Mortgage Porting?
Mortgage porting generally means transferring an existing mortgage arrangement from the current property to another property rather than completely terminating it. The borrower still needs to satisfy lender requirements for the new property and financing arrangement, and the amount required on the new home may not exactly match the old mortgage balance. The portability clause in the existing contract determines what is actually available.
Someone moving to a more expensive home may need additional financing on top of the ported amount. The lender may offer a blended structure or another arrangement combining the existing mortgage with additional borrowing, depending on its products and the borrower. Someone downsizing may face different questions because the new property may require less mortgage debt than the balance being carried forward.
Porting is therefore an alternative that deserves comparison rather than an automatic solution. The existing mortgage rate may be excellent, but the additional financing terms can still make another lender’s complete offer more attractive. Compare the full mortgage after the move rather than focusing only on the rate being preserved.
What Is Blend and Extend?
Blend-and-extend arrangements can allow a borrower to combine the rate on an existing mortgage with a new rate while extending or modifying the mortgage term, depending on the lender’s products. The appeal is that the borrower may be able to change the mortgage without paying the same type of full break penalty that would arise from leaving the lender entirely. The resulting blended rate, however, should be compared carefully with outside refinance offers.
A lender can make a penalty-free internal option look attractive simply because the external option displays a large break charge. The correct comparison adds the external penalty to the outside mortgage costs and compares that complete path with the lender’s blended arrangement over the same time horizon. Avoid choosing based on which option has the smallest upfront charge.
The future flexibility of the blended mortgage also matters. Extending the term or accepting another closed mortgage can create a new prepayment structure that becomes relevant if the homeowner needs to leave again. A solution that avoids today’s penalty can create tomorrow’s restriction, which means the new mortgage contract deserves the same scrutiny as the old one.
Can Another Lender Pay Your Mortgage Penalty?
A new lender may sometimes offer cashback, credits, promotional incentives, or pricing concessions that reduce the homeowner’s immediate cost of switching. Those incentives do not make the underlying penalty disappear because someone still needs to satisfy the amount required to discharge the existing mortgage. The value is simply being offset somewhere else in the transaction.
A borrower should examine what is being exchanged for the incentive. A lender offering enough cashback to cover part of a $5,000 break penalty may also offer a less competitive interest rate or impose conditions requiring repayment of the cashback if the new mortgage is broken early. The headline promotion should therefore be translated into total dollars over the expected holding period.
Treat any incentive as one line in the comparison rather than the reason to select the mortgage. Rate, term, amortization, prepayment privileges, portability, fees, discharge conditions, and future break calculations can matter much more than a one-time contribution to closing costs. The cheapest mortgage to enter can become expensive to leave.
Breaking a Fixed Mortgage vs a Variable Mortgage
The financial experience of breaking a fixed-rate mortgage can differ substantially from breaking a variable-rate mortgage. A fixed mortgage may expose the borrower to an IRD calculation or another penalty mechanism specified in the contract, which can produce a large charge when market conditions and remaining term create a significant difference. The borrower should therefore request the lender’s estimate rather than assume that three months of interest will apply.
Closed variable-rate mortgages are commonly associated with a penalty based on approximately three months of interest, but the contract still controls the exact treatment. Variable borrowers should also consider whether leaving is necessary, because a variable mortgage may provide different conversion options within the same lender. Moving to a fixed mortgage internally could solve a payment-stability concern without requiring the mortgage to be discharged.
The decision should focus on the problem being solved. Someone leaving a variable mortgage because rates have risen needs to compare the cost of breaking with the available fixed or variable alternatives, while someone leaving a fixed mortgage because rates have fallen is solving the opposite pricing problem. The same words, “break the mortgage,” can describe financially very different decisions.
What If Renewal Is Only a Few Months Away?
The closer the mortgage gets to maturity, the stronger the argument for comparing waiting with breaking immediately. A homeowner who has only three months remaining may avoid a significant penalty by waiting until the term ends, while sacrificing only three months of potential savings from the replacement mortgage. That trade can be far more attractive than paying thousands of dollars to leave early.
The calculation should compare the penalty avoided with the savings delayed during the waiting period. If waiting four months avoids an $8,000 penalty while the new mortgage would save $400 per month, the simplified cost of waiting is approximately $1,600 in foregone savings. The preliminary $6,400 difference strongly favours waiting before considering the risk that available mortgage rates change during those four months.
Future rates create uncertainty rather than a reason to ignore the math. Ask how much worse the replacement mortgage would need to become before the advantage of waiting disappears. A decision becomes clearer when rate risk is expressed as a measurable threshold instead of a general fear that “rates might rise.”
Should You Break the Mortgage Now or Wait Until Renewal?
This is one of the most useful comparisons because renewal eliminates the central problem created by leaving a closed term early. At maturity, the borrower can typically negotiate a new term, switch lenders subject to the required process, or repay the mortgage without the same early-termination penalty tied to the expiring contract. Waiting therefore has a clear financial value when maturity is close.
Breaking now becomes more attractive when the remaining term is long and the new mortgage creates substantial savings or solves a major problem immediately. A homeowner with three years remaining and a large rate difference has far more time to recover the penalty than someone with three months remaining. The size of the break cost should therefore always be considered together with the time available for the replacement mortgage to earn it back.
The mortgage prepayment penalty when refinancing analysis becomes particularly useful when the penalty itself is driving this choice. Determine the exact charge, model the savings from leaving, and identify the month when the transaction moves beyond break-even. That result provides a much stronger answer than simply asking which mortgage has the lower rate.
Can You Negotiate the Mortgage Penalty?
The amount is usually determined by the mortgage contract and lender calculation rather than an informal negotiation, so borrowers should not assume the lender will reduce the charge simply because they ask. It can still be worthwhile to discuss the complete situation with the lender because internal refinancing, porting, blending, renewal timing, or another available product can change the amount that ultimately needs to be paid. The conversation should focus on documented alternatives rather than expecting a discretionary discount.
Lenders also have a reason to retain profitable mortgage customers. If the homeowner is considering leaving for another institution, the existing lender may offer a competitive renewal or early-refinance structure that improves the economics enough to avoid the need to break the contract. That offer should be compared against the outside lender after including the full break cost.
Ask for numbers in writing whenever possible. A verbal statement that the lender can “take care of the penalty” is not sufficient when thousands of dollars are involved. The final mortgage documents, payout statement, and closing figures should show exactly how the arrangement works.
Should You Use a Prepayment Privilege Before Breaking the Mortgage?
This can be worth investigating when the contract allows an unused lump-sum privilege and the household has available cash. Reducing the principal before the mortgage is discharged may reduce the amount exposed to the penalty calculation, depending on the lender’s rules. The strategy should be confirmed directly rather than assumed from a general description of annual prepayment privileges.
The cash used for the prepayment also has an opportunity cost. A borrower planning to purchase another home may need that same money for the down payment, land transfer costs, moving costs, renovations, or reserves. Saving $1,000 on the penalty is not useful if using the cash creates a $20,000 shortage on the next transaction.
Treat the privilege as another financing lever rather than free savings. Ask the lender how much the penalty would be before and after the permitted prepayment, then decide whether the cash saved is more valuable than the liquidity given up. This makes the decision specific to the household rather than automatically recommending the maximum allowable prepayment.
Breaking the Mortgage When You Have a Second Mortgage or HELOC
A first mortgage is not necessarily the only lien attached to the property. A HELOC, home equity loan, second mortgage, or other registered secured obligation may also need to be addressed when refinancing or selling. The presence of another lien can change payout amounts, legal work, and the structure available from the replacement lender.
If the first mortgage is being refinanced while a second mortgage remains, the lender providing the new first mortgage may require the junior lender to maintain an acceptable lien position. If both loans are being paid off, the new financing needs enough proceeds to satisfy both obligations and their applicable exit costs. The guide to refinancing a first and second mortgage together explains the broader mechanics of that two-loan decision.
Do not calculate the break decision using only the largest mortgage statement when several secured products exist. Request the relevant balances, payout figures, and discharge requirements for each obligation. What looks like a straightforward first-mortgage refinance can become more complicated once the complete title and lien structure is considered.
What Other Fees Can Appear When Breaking a Mortgage?
A prepayment charge is usually the number that gets the most attention, but the full transaction can contain other costs. Depending on the lender, province, mortgage structure, and replacement financing, borrowers can encounter discharge administration costs, legal expenses, property valuation costs, registration expenses, title-related charges, or fees associated with opening the new mortgage. Some of these expenses would also exist at a normal refinance, while others are specifically connected with leaving the old lender.
The safest approach is to request a complete transaction estimate from both sides. Ask the existing lender for the payout amount and itemization, then ask the replacement lender for the costs associated with establishing the new mortgage. Combining those two sets of numbers creates the actual cost of changing mortgages.
Do not judge the transaction solely by the amount of cash needed at closing because some costs can be incorporated into the replacement financing when the structure permits. Financing a $5,000 cost does not eliminate it, because the amount becomes additional mortgage principal and may generate interest for years. Compare the new mortgage balance as carefully as the cash requirement.
Calculate the Real Cost of Breaking the Mortgage
A useful simplified calculation begins by adding every unavoidable cost of leaving and replacing the mortgage. That includes the prepayment charge, discharge costs, legal or registration expenses attributable to the change, and new mortgage costs that would not otherwise exist. The total becomes the amount the new arrangement needs to recover before the financial advantage becomes meaningful.
Suppose the break penalty is $7,500, associated exit expenses are $500, and obtaining the new mortgage costs another $2,000. The simplified cost of changing mortgages is approximately $10,000. If the new mortgage produces $400 per month of comparable savings, the simplified break-even period is approximately 25 months.
The simplified method should be followed by a mortgage-balance comparison. If the replacement mortgage extends the amortization, part of the lower payment may come from slower principal repayment rather than cheaper financing. Compare how much would remain owing under both mortgages after the same future period before describing the entire payment difference as savings.
Why a Lower Payment Can Be Misleading
A homeowner may break a mortgage because the replacement lender offers a monthly payment hundreds of dollars lower. The payment can genuinely improve household cash flow, but a lower payment is not proof that the replacement mortgage costs less overall. Extending the remaining amortization can produce a smaller required payment even when the interest rate improvement is modest.
Suppose the current mortgage has 17 years remaining on its amortization, while the new mortgage is structured over 25 years. The longer schedule distributes the principal across many more payments, which can reduce the monthly obligation substantially. The household has gained flexibility while potentially extending the amount of time mortgage interest will be paid.
That outcome can still be desirable when cash flow is the main objective. The important point is to identify the source of the payment reduction so the borrower understands the trade being made. A mortgage should not be labelled cheaper simply because its required monthly payment is lower.
What Happens to Your Mortgage Insurance When You Break the Contract?
Mortgage insurance and lender insurance treatment can become relevant when moving between mortgage arrangements, especially when the mortgage was originally insured or the new financing changes the loan-to-value structure. Borrowers should not assume that every feature attached to the original mortgage transfers automatically to a replacement lender or new structure. The lender should explain how the proposed transaction affects insurance treatment and qualification.
This becomes particularly important when the borrower is switching lenders rather than merely renewing with the same institution. The new lender may need documentation about the existing mortgage and property, and the type of refinance can influence what financing is available. Ask for the complete qualification structure rather than comparing only interest rates.
A homeowner should also distinguish mortgage default insurance from creditor mortgage life or disability insurance purchased separately. Breaking or moving the mortgage can affect optional creditor insurance arrangements differently from mortgage default insurance. Review any insurance tied to the lender relationship before assuming coverage continues unchanged.
Will Breaking a Mortgage Hurt Your Credit Score?
Breaking the mortgage itself should not be confused with missing mortgage payments. A properly completed refinance or sale pays out the existing mortgage as part of the transaction, which is fundamentally different from stopping payments while the debt remains outstanding. The borrower still needs to keep the current mortgage in good standing until the lender confirms that the obligation has been properly discharged or replaced.
A refinance application can involve credit checks and a new mortgage account, which may affect the credit file in the ordinary way associated with seeking new borrowing. Those effects are usually secondary to the much larger financial question of whether the replacement mortgage is suitable. A homeowner should not keep an economically poor mortgage merely because they are afraid that applying for another loan will alter the credit score.
The dangerous behaviour is assuming that an anticipated refinance means current payments can stop. Closings can be delayed, underwriting can change, and financing can fail. Continue following the existing mortgage obligations until the appropriate lender or legal professional confirms that the loan has been paid out.
Can You Break a Mortgage During a Separation or Divorce?
Relationship changes can force decisions that have little to do with interest-rate optimization. One partner may buy out the other’s interest, the property may be sold, or the existing mortgage may need to be replaced because the borrower structure is changing. Each possibility can interact with the current mortgage contract and potential prepayment charge.
The lender still needs to approve any new borrowing arrangement. Removing a borrower from title or from the mortgage is not simply an administrative request when the remaining borrower must qualify for the debt. Legal advice is particularly important because property ownership, family law, and mortgage obligations overlap.
A break penalty should therefore be treated as one component of the separation transaction rather than the only financial concern. The immediate objective may be creating a workable ownership structure even when the mortgage change is not optimal from a pure interest-cost perspective. Household circumstances can make flexibility more valuable than minimizing every lender charge.
Can You Break a Mortgage During Financial Hardship?
Someone experiencing financial difficulty should contact the lender early rather than assuming refinancing is the only way to escape the current payment. Lenders may have hardship or payment-assistance processes depending on the circumstances, and changing the mortgage before understanding those possibilities can create additional costs. The Financial Consumer Agency of Canada’s mortgage relief guidance provides official information about measures that federally regulated financial institutions are expected to consider for borrowers experiencing severe financial difficulty with their principal residence.
A refinance can still be useful when the borrower qualifies and the new structure genuinely improves affordability. The problem is that financial hardship can also weaken qualification because income, credit, or debt ratios may have deteriorated. Waiting until payments are already missed can therefore reduce the available options.
Seek help before the situation becomes urgent. A homeowner who still has a strong payment history and time to compare alternatives is in a better negotiating position than someone attempting to restructure the mortgage immediately before a missed payment. Early action preserves more choices.
What Happens When You Break the Mortgage to Switch Lenders?
Switching lenders before maturity usually means the existing mortgage needs to be paid out and the new lender needs to establish its mortgage against the property. The break penalty can therefore become the largest barrier to moving, especially when the borrower is attracted by a modest rate difference. The new lender’s offer should be compared only after the full old-lender exit cost is included.
The new mortgage can also contain its own restrictions. A borrower who leaves one lender because the current contract feels inflexible should carefully review the portability, prepayment privileges, penalty formula, collateral-charge structure where applicable, and discharge conditions of the replacement mortgage. Saving money today while accepting another restrictive contract can repeat the same problem later.
This is also why switching solely for a promotional rate deserves caution. A strong mortgage is a combination of rate, flexibility, fees, service, and future exit conditions rather than one number. The mortgage needs to work when entering it and when eventually leaving it.
How Close to Renewal Should You Start Comparing Options?
You do not need to wait until the maturity date arrives before understanding the alternatives. Beginning the comparison several months before renewal provides time to request the payout amount, check competing mortgage rates, understand the break penalty, and determine whether waiting or leaving early produces the stronger result. The closer maturity becomes, the more valuable a precise date-by-date comparison can be.
Renewal offers from the existing lender should also be compared rather than accepted automatically. The Financial Consumer Agency of Canada’s guidance on renewing your mortgage recommends shopping around and comparing mortgage options rather than assuming the existing lender’s renewal is the best available choice. Starting early gives the borrower time to negotiate without creating an urgent closing deadline.
The goal is not necessarily to break the mortgage before renewal. The goal is to know what breaking would cost and what waiting would preserve so the timing becomes intentional. A homeowner who enters renewal month already understanding both numbers has much more negotiating power.
The Break-Now vs Wait-for-Renewal Test
Begin with the exact cost of leaving today. Include the prepayment charge and all incremental costs necessary to complete the new transaction. Then calculate how much the replacement mortgage is expected to save each month on a comparable basis.
Next, multiply the expected monthly saving by the number of months remaining before renewal. That amount represents the simplified savings you sacrifice by waiting, while the penalty represents the major cost you may avoid by staying. Compare those numbers before considering the additional uncertainty of future mortgage rates.
Finally, calculate the mortgage rate or payment change that would need to occur during the waiting period before leaving today becomes preferable. This is the useful stress test because it gives the homeowner a threshold. Instead of saying, “Rates might rise,” you can say, “The future mortgage would need to become approximately this much more expensive before today’s penalty is worth paying.”
When Breaking the Mortgage Has a Stronger Case
Breaking becomes more attractive when the new mortgage creates substantial ongoing savings and a meaningful amount of time remains before the existing mortgage reaches maturity. The larger the monthly improvement and the longer the homeowner expects to keep the replacement mortgage, the more opportunity exists to recover the break cost. A relatively small penalty also strengthens the financial case.
The argument can become even stronger when the mortgage change solves another significant problem. Moving from an unaffordable payment structure, completing a necessary property sale, restructuring after a separation, or eliminating another serious mortgage risk can provide value that is not captured by the simple rate comparison. Financial decisions are not always about minimizing interest when household circumstances have changed materially.
The replacement mortgage still needs to be examined carefully. A large rate reduction combined with expensive new fees, an extended amortization, poor prepayment privileges, or an unattractive future break formula can reduce the apparent advantage. The whole contract needs to improve rather than merely the advertised rate.
When Waiting Is Usually More Attractive
Waiting becomes particularly compelling when renewal is close and the prepayment charge is large. A homeowner with only a few months remaining has limited time to benefit from the new mortgage before the old contract ends naturally. Paying a five-figure penalty to capture several months of savings can therefore be difficult to justify.
Waiting can also be attractive when the existing mortgage rate is already competitive. If the replacement mortgage saves only a modest amount each month, the break-even period can stretch beyond the time the homeowner expects to keep the new loan. The borrower is then paying a substantial upfront amount for a relatively small financial improvement.
A short expected ownership period creates the same problem. Someone planning to sell again soon may not keep the replacement mortgage long enough to recover the cost of breaking the current contract. Use the actual expected holding period rather than assuming the new mortgage will remain for its entire term.
Questions to Ask Your Lender Before Breaking the Mortgage
Ask for the exact mortgage payout amount for a realistic closing date and request an itemized explanation of the prepayment charge. Ask which calculation method is being used, what interest rate or comparison rate applies, whether prepayment privileges can reduce the balance, and how long the quoted amount remains valid. These answers establish the cost of leaving rather than relying on a rough online estimate.
Then ask about alternatives available without fully breaking the mortgage. Portability, internal refinancing, blend-and-extend arrangements, conversion options, and renewal timing can potentially change the decision depending on the lender’s products. Request enough detail to compare those options against an outside refinance rather than treating an internal offer as automatically cheaper.
Finally, ask how the lender calculates future penalties on any replacement mortgage it proposes. A borrower leaving an expensive contract should be especially careful not to enter another mortgage whose exit conditions are poorly understood. Today’s flexibility problem is useful information when selecting tomorrow’s loan.
Questions to Ask the New Lender Before You Switch
Tell the new lender the actual payout amount rather than only the current mortgage balance. Ask whether the new mortgage amount, closing costs, legal expenses, and cash requirement already account for the break penalty. A quote that ignores the old-lender payout does not yet describe the real transaction.
Ask for the rate, term, amortization, payment, prepayment privileges, portability, penalty provisions, and all lender charges in writing. Compare the future mortgage balance at the end of the period you expect to keep the loan, especially when the replacement mortgage changes the amortization. This helps separate genuine financing improvement from a payment reduction caused mostly by extending repayment.
If you have refinanced recently, also consider how frequently the household is replacing mortgages. The guide to how often you can refinance your mortgage explains why repeated closing costs can consume the savings from chasing relatively small rate changes. The new transaction should create enough improvement to justify another reset.
A Practical Checklist Before You Break the Contract
Start by locating the mortgage agreement, original commitment, current mortgage statement, and any documentation describing prepayment privileges. Confirm the contractual maturity date and determine exactly how many months remain in the term. Those documents establish the baseline before lender quotes begin influencing the decision.
Request a written payout figure and identify the penalty separately from ordinary principal and accrued interest. Then obtain a complete replacement mortgage scenario, including the new rate, term, amortization, payment, fees, legal costs, and expected mortgage amount. Calculate break-even using comparable payments and then compare future balances.
Finally, consider the non-financial reason for leaving. A refinance designed purely to save interest should pass a stricter cost test than a mortgage change required because a home is being sold or a household is separating. The reason does not make costs disappear, but it changes what success looks like.
Frequently Asked Questions About Breaking a Mortgage Contract
What does it mean to break a mortgage contract?
Breaking a mortgage contract means ending the current mortgage term before its scheduled maturity date. The existing mortgage usually needs to be paid out through a sale, refinance, or other approved arrangement, and a closed mortgage may impose a prepayment charge when that happens. The exact cost and available alternatives depend on the contract and lender.
How much does it cost to break a mortgage in Canada?
There is no single cost because the amount depends on the mortgage balance, rate, type of mortgage, remaining term, lender formula, prepayment privileges, and date of payout. The prepayment charge can be based on a method such as three months of interest or an interest rate differential under the lender’s contract, and additional discharge or transaction expenses may also apply. Request a current itemized payout statement before making the decision.
Is it worth breaking a mortgage for a lower interest rate?
It can be worthwhile when the savings from the replacement mortgage are large enough to recover the prepayment penalty and other switching costs within the period you expect to keep the new mortgage. Calculate the break-even period and compare future mortgage balances rather than looking only at the new monthly payment. A lower rate does not automatically create a cheaper transaction when the break cost is substantial.
Can I avoid the penalty by waiting until mortgage renewal?
Waiting until the existing term reaches maturity can avoid the early-break penalty associated with ending that term, subject to the mortgage contract and the way the loan is handled at maturity. The decision should compare the penalty avoided with the mortgage savings you give up while waiting. Future rates are uncertain, so the comparison should also consider how much pricing could change before waiting becomes less attractive.
Can I move my mortgage to another home instead of breaking it?
Some mortgages are portable, which may allow the mortgage or an adjusted version of it to move to another qualifying property. Porting depends on the mortgage contract, lender requirements, new property, borrower qualification, transaction timing, and amount of financing needed. Compare the complete ported arrangement with the cost of breaking the mortgage and taking a new loan.
Can I use a lump-sum prepayment before breaking my mortgage?
Potentially, when the mortgage contract provides an available prepayment privilege and the lender permits it under the applicable timing rules. Reducing the principal before payout may reduce the amount exposed to a penalty calculation in some situations. Confirm the effect with the lender before using cash because the household may need that liquidity for the next property, closing costs, or emergency reserves.
Does breaking a mortgage hurt your credit?
Properly refinancing or selling a property and paying out the existing mortgage is different from missing required mortgage payments. A new mortgage application can involve credit inquiries and a new account, but those ordinary borrowing effects should be separated from delinquency. Continue paying the existing mortgage as required until the appropriate parties confirm that it has been discharged or replaced.
Should I break a mortgage that is only a few months from renewal?
Waiting often deserves serious consideration when maturity is close because the borrower has relatively little time to capture savings before the existing contract ends naturally. Compare the penalty avoided with the savings lost during the remaining months, then stress-test how much future mortgage pricing would need to worsen before breaking today becomes preferable. The actual numbers matter more than a universal rule.
Final Verdict
Breaking a mortgage contract in Canada can be financially sensible, but the decision should never begin and end with the interest rate on the replacement mortgage. The existing lender may require a significant prepayment charge to end a closed mortgage before maturity, and additional discharge, legal, or refinancing expenses can increase the cost of moving. The first step should therefore be obtaining the exact payout amount and understanding every component of that figure.
A lower-rate refinance has the strongest case when substantial savings are available and enough time remains for those savings to recover the break cost. A mortgage with only a few months remaining until renewal deserves a very different analysis because waiting can eliminate the early-exit charge while sacrificing only a limited period of potential savings. Comparing the penalty avoided with the savings delayed provides a much more useful answer than simply asking whether current rates are lower.
Homeowners moving to another property should also examine portability and internal lender options before automatically discharging the mortgage. Someone refinancing should compare the complete replacement mortgage, including its amortization, future balance, prepayment privileges, portability, fees, and its own future break provisions. Escaping one restrictive mortgage by entering another poorly understood contract simply moves the problem forward.
The most useful question is therefore not “Can I break my mortgage?” because a mortgage can usually be paid out when the necessary contractual amounts are satisfied. The decision that deserves careful work is “What does leaving today cost compared with staying, and what problem does leaving solve?” Once the penalty, remaining term, new mortgage costs, future savings, and household objective are placed beside each other, the correct timing becomes considerably easier to judge.