Yes, it is often possible to refinance a first and second mortgage together, but the transaction is more complicated than refinancing a property with only one lien. The central issue is that two separate loans currently have claims against the same property, and the new lender needs to know exactly what will happen to both of those claims when the refinance closes. Depending on the structure, the first and second mortgages may both be paid off and replaced by one new mortgage, or the first mortgage may be refinanced while the existing second mortgage remains in place.
Those two outcomes should not be treated as interchangeable. Combining both loans can simplify the household from two mortgage payments to one and may improve the overall rate or repayment structure, but it can also move an inexpensive first mortgage or second mortgage into a new loan with higher current-market pricing. Keeping the second mortgage instead may preserve favorable terms, but the second lender may need to agree to remain subordinate to the new first mortgage.
The Consumer Financial Protection Bureau’s explanation of second mortgages defines a second mortgage or junior lien as another loan secured by the home while a different loan is already secured by that same property. The word “second” refers to repayment priority if the property must be sold to satisfy the debts, which is why lien position becomes so important when one of those loans is replaced.
The CFPB also specifically warns that refinancing can become more complicated when a second mortgage exists because the second mortgage lender generally has to agree to the refinance unless the second mortgage is being paid off through the new loan. That single issue explains why a homeowner with excellent credit and substantial income can still encounter additional paperwork during a first-mortgage refinance when a HELOC, home equity loan or other junior lien remains open.
The better question in 2026 is therefore broader than “Can I combine the loans?” You should ask whether combining them creates a stronger mortgage than keeping them separate. The answer depends on both balances, both interest rates, remaining terms, home value, combined loan-to-value ratio, closing costs, the second lender’s subordination decision and how long you expect to keep the new mortgage.
What Happens When You Refinance a First and Second Mortgage Together?
When both mortgages are being consolidated, the new refinance loan generally provides enough proceeds to satisfy the balances that need to be paid off as part of the transaction. After closing, the old first mortgage and second mortgage are no longer separate monthly obligations, and the homeowner begins making payments under the terms of the new mortgage.
That can create a much cleaner financial structure. Instead of remembering a first mortgage payment and a separate home equity loan or second mortgage payment, the household has one principal balance, one interest structure, one scheduled payment and one maturity timeline.
The simplification is useful, but it is not automatically a financial saving. If the first mortgage carries a very low rate and the second mortgage is relatively small, replacing both balances with a new mortgage at a higher rate can increase the cost applied to a large amount of debt merely to eliminate the smaller second loan.
This is why the refinance should be modeled as old structure versus new structure, rather than looking only at whether the new payment is lower.
First + Second Mortgage Refinance Gap Calculator
Find out how large a refinance needs to be to pay off both mortgages, whether your home’s equity can support it, and how much cash or debt reduction may be needed if the proposed refinance falls short.
Current Property and Mortgages
Can the Refinance Cover Both Loans?
The calculator will show whether the selected LTV leaves enough room to pay off both mortgages.
Three Ways a First and Second Mortgage Refinance Can Be Structured
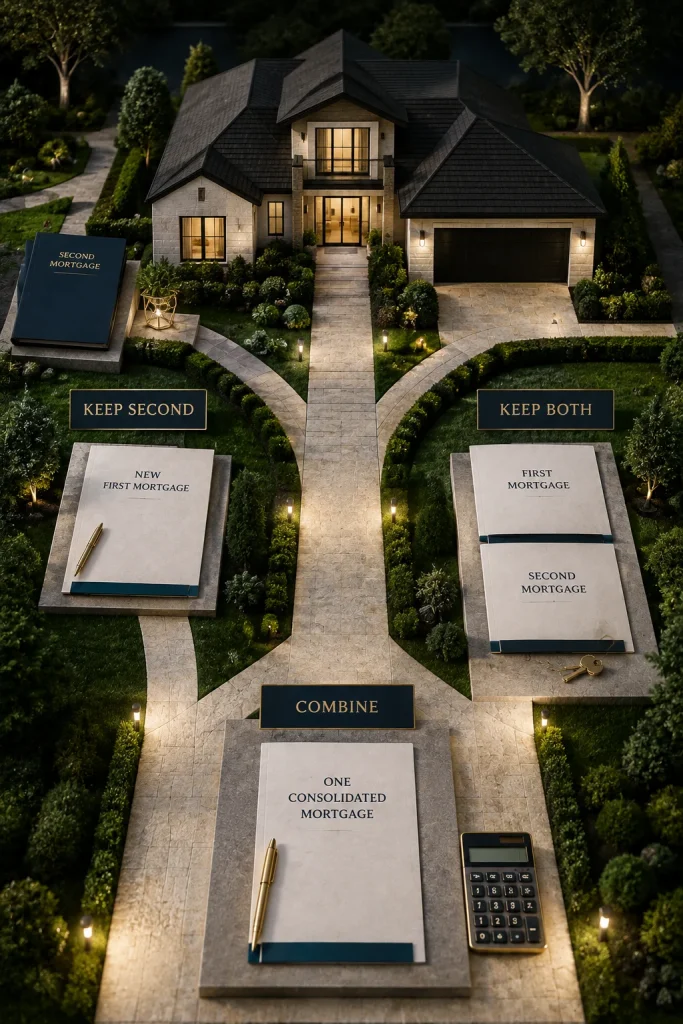
There are three common decision paths when a property has two mortgage liens.
| Structure | What Happens | When It May Be Attractive |
|---|---|---|
| Combine both into one refinance | The existing first and second mortgages are paid off and replaced by one new mortgage. | When the combined new rate, payment, term and costs improve the overall borrowing structure. |
| Refinance the first and keep the second | The first mortgage is replaced, while the second mortgage remains and may need to subordinate to the new first loan. | When the second mortgage has attractive terms or paying it off would make the refinance unnecessarily large. |
| Keep both existing loans | No refinance occurs, and both current mortgages continue under their existing terms. | When refinancing costs or current rates would make replacement financing more expensive. |
The important point is that “refinancing with a second mortgage” does not always mean combining the second mortgage into the new first mortgage. A borrower can sometimes refinance the first mortgage while leaving the junior lien intact, provided the involved lenders and transaction structure allow the required lien priority.
Understanding which of these three structures you are actually requesting can prevent substantial confusion during lender comparisons.
Why Lien Position Matters
A mortgage is more than a monthly payment. It is also a secured claim against the property.
The first mortgage normally occupies first lien position, while the second mortgage sits behind it. If the property had to be sold to satisfy secured debts, lien priority determines the order in which those claims are generally addressed.
When the original first mortgage is paid off during refinancing, a new first mortgage is created. The lender providing that new mortgage normally expects its loan to occupy the appropriate senior lien position.
The problem is that the existing second mortgage has already been recorded. Without the proper transaction handling, replacing the old first mortgage could disturb the expected lien relationship between the loans.
This is why refinancing with a second lien sometimes requires subordination.
What Is Mortgage Subordination?
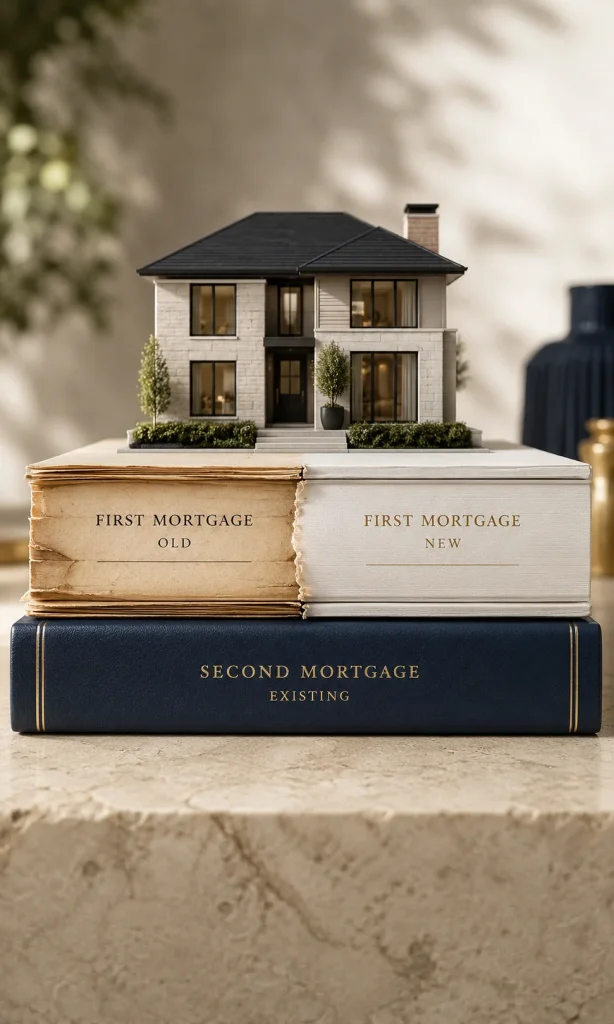
Mortgage subordination is the process that allows an existing junior lien to remain behind a newly created first mortgage rather than moving ahead of it when the old first mortgage is replaced.
Imagine you have:
First mortgage: $300,000
Home equity loan: $50,000
You want to refinance only the $300,000 first mortgage.
If the $50,000 home equity lender agrees to subordinate its lien, the new refinance mortgage can occupy first position while the existing $50,000 loan continues in second position.
The CFPB notes that refinancing with an existing second mortgage can require the second lender’s agreement unless that second loan is being paid off through the refinance. That is why the junior lender may become part of the refinance process even though you are not asking that lender for a new loan.
Subordination can require documentation, processing time and potentially fees. It should therefore be identified early rather than discovered shortly before the expected closing date.
Why Would the Second Mortgage Lender Agree to Stay in Second Position?
The second lender originally agreed to lend money while another mortgage occupied senior position. Subordination allows that basic ranking to continue after the old first mortgage is replaced.
The lender still evaluates whether the new transaction changes its risk.
If the new first mortgage balance becomes substantially larger, the property value has declined or the borrower’s circumstances have weakened, the junior lender may view the new arrangement differently from the original one.
This is particularly important when the homeowner wants to take cash out through the new first mortgage while leaving the existing second mortgage in place. Increasing the amount owed ahead of the second lender can reduce the equity cushion protecting that junior lien.
A borrower should therefore never assume subordination is automatic simply because the second loan was already subordinate before refinancing.
Can You Refinance Both Mortgages Into One Loan?
Potentially, yes. This is often the cleanest version of mortgage consolidation because both existing loans are satisfied and one new mortgage replaces them.
Suppose your current balances are:
First mortgage: $320,000
Second mortgage: $55,000
The combined secured debt is $375,000 before considering any additional financed costs or cash-out amount.
A refinance large enough to pay off both loans could replace that structure with one new mortgage, subject to property value, equity, underwriting requirements and program rules.
You would then compare the new mortgage against the combined economics of the old first and second loans.
The monthly payment may become easier to understand, but the financial comparison should include far more than the payment.
The Existing First Mortgage Rate Can Completely Change the Decision
A homeowner who obtained the first mortgage under very favorable conditions needs to be particularly careful about consolidation.
Suppose the first mortgage balance is large and carries a substantially lower interest rate than a new refinance would provide, while the second mortgage is comparatively small.
Refinancing both loans together could solve the second mortgage problem by repricing the entire first mortgage balance.
That can be an expensive trade.
For example, imagine a household has a $350,000 first mortgage with attractive terms and a $40,000 second mortgage carrying a much higher rate. Consolidating them means the new mortgage is pricing approximately $390,000 of debt rather than solving only the expensive $40,000 component.
The second mortgage may be unpleasant, but replacing a favorable first mortgage can still cost more.
When Combining Both Mortgages Can Make Sense
Consolidation becomes more attractive when both existing loans are expensive relative to the realistic terms available on a new mortgage.
It may also make sense when the second mortgage has an uncomfortable repayment structure, a future balloon payment, a variable rate that creates budgeting uncertainty or a monthly payment that no longer fits the household’s preferred cash-flow structure.
Another reason is simplification. Two mortgages create two payment obligations and potentially two servicing relationships. Combining them can make budgeting easier and eliminate the administrative burden associated with the second loan.
The financial value of simplification should still be measured. Paying thousands of dollars in refinancing costs purely to reduce the number of monthly bills is very different from consolidating while also improving the rate, repayment term or risk profile.
When Keeping the Second Mortgage Can Be Better
A second mortgage should not be viewed as something that must be eliminated merely because you are refinancing the first loan.
If the second mortgage has a favorable fixed rate, low balance or short remaining term, preserving it can be financially reasonable.
Keeping the second may also allow the new first mortgage to remain smaller, which can affect qualification, loan-to-value calculations and the total amount of debt being repriced.
The subordination process introduces another step, but an additional administrative step can still be worth completing when it preserves a favorable second loan.
The correct comparison is therefore not “one payment is always better than two.”
The better comparison is “which combination of loans produces the stronger total cost, cash flow and risk profile?”
What Is CLTV When You Have Two Mortgages?
CLTV means combined loan-to-value ratio.
With one mortgage, loan-to-value compares that mortgage balance with the property value. With multiple liens, CLTV combines the relevant mortgage balances before comparing them with the property.
A simplified calculation is:
First mortgage balance + second mortgage balance ÷ property value = CLTV
If your house is valued at $600,000 and you owe $300,000 on the first mortgage plus $60,000 on a home equity loan, your combined secured debt is $360,000.
The simplified CLTV is:
$360,000 ÷ $600,000 = 60%
That number helps lenders understand how much of the property’s value is already supporting secured debt.
Why CLTV Can Affect Whether the Refinance Works
Two homeowners with identical first mortgage balances can face very different refinance options when one of them also has a large second mortgage.
The second lien consumes part of the property’s equity cushion.
If a lender or loan program limits how much combined secured debt can exist relative to the property value, the second mortgage becomes part of that calculation even when it is not being paid off.
A lower appraisal can therefore create problems.
Suppose you expect the property to be worth $700,000 but the appraisal supports only $625,000. The mortgage balances have not changed, but the CLTV has increased because the denominator became smaller.
This can alter the available refinance structure, pricing or qualification.
Use the Combined Mortgage, Not Just the First Mortgage, When Measuring Equity
Homeowners often look at the first mortgage statement and mentally compare only that balance with the home’s estimated value.
That can substantially overstate available equity when a HELOC or second mortgage also exists.
If your property is worth $500,000 and the first mortgage balance is $300,000, looking only at the first loan suggests $200,000 of equity.
If a $75,000 second mortgage also exists, combined secured debt is actually $375,000.
The remaining gross equity before selling costs or other obligations is closer to $125,000.
A refinance analysis should therefore begin with every recorded mortgage obligation rather than the largest one.
First and Second Mortgage Consolidation Example
Consider this illustrative household:
Home value: $650,000
First mortgage balance: $340,000
First mortgage rate: 6.75%
Second mortgage balance: $60,000
Second mortgage rate: 10.00%
The household owes $400,000 in combined mortgage debt.
Their simplified CLTV is approximately:
$400,000 ÷ $650,000 = 61.54%
Now imagine the borrower is offered a refinance that would consolidate the $400,000 into one new loan.
The new payment might be lower than the combined current payments if the repayment period is extended or if the expensive second mortgage is absorbed into lower-rate financing.
That lower payment is useful, but it is not enough information to approve the transaction.
The borrower should compare how much interest remains on both current loans, how many years remain on each, the closing costs for the refinance and how long the new mortgage will remain outstanding.
A Lower Combined Payment Can Hide a Longer Repayment Period
This is one of the most important traps in mortgage consolidation.
Suppose the second mortgage is scheduled to disappear in five years, while the first mortgage has 22 years remaining.
If both balances are refinanced into a new 30-year mortgage, the required payment could fall substantially.
The household feels immediate relief because two payments have become one smaller payment.
The second mortgage balance, however, may now be spread across a much longer period unless the borrower pays extra principal.
That is why payment reduction and interest reduction should always be evaluated separately.
A lower payment can be achieved because the loan became cheaper, because the repayment period became longer, or through a combination of both.
Should You Consolidate a HELOC Into the First Mortgage?
A HELOC introduces another variable because its structure can differ significantly from a closed-end home equity loan.
HELOCs commonly allow revolving borrowing during a draw period and may have variable interest rates. A homeowner can therefore face payment changes when benchmark rates change or when the loan moves into a different repayment phase.
Consolidating the HELOC into a fixed-rate first mortgage can remove some of that uncertainty.
The trade-off is losing the revolving credit line and potentially converting a balance that might otherwise be repaid more quickly into a longer mortgage.
If you expect to need continued access to the credit line for an ongoing renovation or another planned expense, paying off and closing the HELOC may also affect future borrowing flexibility.
The decision needs to consider what the HELOC is being used for, not merely its current balance.
What Happens to an Open HELOC During a Refinance?
An open HELOC can complicate refinancing even when its current balance is zero.
The credit line may still represent a lien against the property and the potential for future borrowing.
A refinance lender therefore needs to know that it exists.
Depending on the new mortgage, lender requirements and HELOC lender, the line may need to be closed, paid off, frozen, modified or subordinated.
A zero balance should not be interpreted as proof that the HELOC can simply be omitted from the refinance application.
Tell the refinance lender about every mortgage or credit line secured by the property.
Is Combining First and Second Mortgages a Cash-Out Refinance?
Sometimes, but not automatically.
The classification depends on the transaction structure, how the second mortgage was created, the applicable loan program and whether additional equity is being taken out.
From a consumer decision perspective, the most important question is what the new loan is doing.
If it only satisfies existing secured debt and allowable transaction costs, the economics differ from a refinance that also substantially increases the total mortgage balance to provide additional cash.
Cash-out structures can have different pricing, equity requirements and underwriting treatment.
Do not assume that paying off the second mortgage guarantees the transaction will be treated exactly like a simple rate-and-term refinance.
What If the Second Mortgage Was Used to Buy the Home?
This detail can matter to the refinance structure.
Some homeowners originally used a first mortgage together with a smaller second mortgage to finance the home purchase. Others added a home equity loan or HELOC years later.
Those histories are financially different.
A purchase-related second mortgage may represent debt that has been part of the property’s acquisition financing from the beginning, while a later home equity loan represents additional borrowing against equity.
When asking lenders for refinance quotes, explain when and why the second mortgage was originated rather than assuming the current balance tells the entire story.
The lender can then determine how the transaction is treated under the relevant program.
What If Your Second Mortgage Has a Balloon Payment?
A balloon structure creates a particularly strong reason to examine refinancing before the maturity date arrives.
Instead of amortizing completely through ordinary scheduled payments, the loan may require a substantial remaining balance to be paid at a specific point.
A homeowner who waits until that date is close may have fewer options if property value, income, credit or mortgage-market conditions become less favorable.
Combining the balloon balance into a new first mortgage can solve the immediate maturity problem, but the transaction still needs to make sense after fees and long-term interest are considered.
If the balloon mortgage itself is the main concern, review the existing guide to refinancing a balloon payment before deciding whether the first mortgage also needs to be replaced.
What If the Second Mortgage Rate Is Much Higher Than the First?
This is one of the hardest scenarios because the household has one inexpensive loan and one expensive loan.
Combining the debts produces a weighted trade.
The high-rate second balance benefits from moving into the lower new refinance rate, while the low-rate first balance may become more expensive.
The larger balance usually deserves greater weight in the calculation.
If the first mortgage is six times larger than the second mortgage, a modest rate increase on the first balance can offset a dramatic rate reduction on the second.
This is exactly why a purpose-built combined mortgage calculator can be more useful than simply comparing headline rates.
Use the first and second mortgage consolidation refinance calculator to compare the combined payment structure before assuming the higher-rate second loan should automatically be absorbed into a refinance.
What Costs Should You Include in the Comparison?
Closing costs
Refinancing can involve lender charges, appraisal-related costs, title-related expenses, government recording charges and other transaction costs depending on the loan.
Those expenses need enough monthly savings or other financial benefit to justify them.
Subordination fees
If the second mortgage remains in place, the junior lender may have its own processing requirements and possible fees for reviewing a subordination request.
Ask about those requirements early.
Prepayment penalties
Some existing mortgage agreements can include prepayment charges under specified conditions.
Review both loans rather than assuming only the first mortgage could contain an early-payoff consequence.
Points
A new lender may offer a lower interest rate in exchange for discount points paid upfront.
The value depends partly on how long you expect to keep the new mortgage.
Escrow funding and prepaid items
These can affect the amount of cash required at closing even though they should be distinguished from lender costs.
Looking only at “cash to close” without understanding each component can make one refinance offer appear more expensive than another for the wrong reason.
Calculate the Break-Even Period on the Combined Refinance
Suppose combining your two mortgages reduces the household’s required monthly payments by $400, while the refinance creates $8,000 in costs that you would not otherwise incur.
A simplified break-even estimate would be:
$8,000 ÷ $400 = 20 months
That means approximately 20 months of payment savings would be needed to recover the transaction costs under the simplified calculation.
If you expect to sell the house in 12 months, the refinance may struggle to repay its costs before the mortgage disappears.
If you expect to keep the new mortgage for many years, the transaction has much more time to recover the upfront expense.
A proper analysis should go farther by considering changes in principal repayment and loan term, but break-even remains a useful first screen.
What If You Cannot Get the Second Lender to Subordinate?
If the second lender will not agree to the required subordination, refinancing only the first mortgage may become difficult or impossible under the proposed structure.
That does not necessarily end every refinance possibility.
One alternative is paying off the second mortgage as part of the new loan if the borrower qualifies and the transaction economics support it.
Another is paying the second loan off separately before refinancing, although that requires sufficient liquidity and may not be practical.
A different lender or loan program may also produce another path, but no lender can simply ignore the recorded junior lien.
The title and lien structure must be resolved appropriately.
Can You Refinance Just the Second Mortgage?
Potentially, yes.
A homeowner may be satisfied with the first mortgage and want only to replace an expensive second mortgage or HELOC.
That can preserve favorable first-mortgage pricing while changing only the debt that actually needs improvement.
The new second lender still evaluates the property, existing senior debt, borrower qualification and combined leverage.
This strategy can be particularly attractive when the first mortgage was obtained under substantially better terms than anything available today.
Do not replace inexpensive debt merely because another debt secured by the same property is expensive.
Could You Pay Off the Second Mortgage Without Refinancing?
Yes, and this alternative should be included in the comparison.
If the second mortgage balance is modest and the household has sufficient cash flow, directing additional principal payments toward the second loan may eventually eliminate it without touching the first mortgage.
The strategy avoids new refinance closing costs.
The downside is that the required monthly second-mortgage payment remains until the debt has been repaid, and using large amounts of savings to eliminate the loan can reduce household liquidity.
The relevant comparison is therefore:
Pay the second mortgage faster
versus
Refinance only the second mortgage
versus
Combine both mortgages
versus
Keep both loans unchanged
The strongest option depends on the actual numbers.
What Documents Will the Refinance Lender Need?
Expect the new lender to request information about both mortgage obligations.
That can include recent statements showing balances, loan numbers, payment information and the identity of the lenders or servicers.
The lender may also need information needed to obtain payoff statements or communicate about subordination.
Property-value documentation, income information, assets, credit and other underwriting materials may also be required depending on the refinance type.
Having the second mortgage documents ready at the beginning makes the lien analysis easier than disclosing the loan late in underwriting.
What Happens at Closing When Both Mortgages Are Being Paid Off?
When the refinance is structured to consolidate the loans, funds from the new transaction are used to satisfy the existing secured obligations according to the closing arrangement.
The CFPB’s mortgage disclosure rules specifically contemplate subordinate-lien payoffs being shown in refinance transaction disclosures. (consumerfinance.gov)
After the existing loans are paid off, the homeowner should eventually verify that both old accounts reflect the appropriate payoff status.
If automatic payments were previously established for either mortgage, coordinate their cancellation carefully rather than stopping them prematurely because a refinance is merely scheduled.
A delayed closing can leave an existing payment obligation in place longer than expected.
Do You Get the Old Escrow Balance Back?
If the old first mortgage includes an escrow account, that account may need to be reconciled after payoff.
The new mortgage may also establish an escrow account, which can mean the borrower funds part of the new account during the refinance and later receives remaining funds associated with the old mortgage.
The timing can make the refinance look temporarily expensive because money may be needed for the new escrow before the previous balance has been returned.
Do not rely on the expected old escrow refund as closing-day cash unless the transaction documentation specifically supports that assumption.
Treat it as a separate post-payoff cash-flow item.
Should You Extend the Loan Back to 30 Years?
A new 30-year mortgage can dramatically reduce the required payment when the existing loans have much shorter remaining terms.
That flexibility may be useful, especially when the household’s priority is monthly cash flow.
The danger is allowing debt that was scheduled to disappear sooner to remain outstanding for decades.
One possible strategy is taking the longer contractual term for flexibility while voluntarily paying additional principal when cash flow allows.
That can provide a lower required payment without necessarily committing the household to the minimum payment for the full term.
The success of that strategy depends on actually making the additional payments rather than merely intending to do so.
Could Consolidation Improve Your Monthly Cash Flow?
Yes, particularly when the second mortgage carries a high required payment or short amortization period.
Replacing two payments with one longer-term mortgage can significantly reduce the amount due each month.
That improvement can create genuine financial stability for a household whose income is sufficient but whose existing debt schedule is too aggressive.
However, monthly cash flow is only one dimension of affordability.
A refinance that lowers the payment while substantially increasing lifetime interest should be understood as buying payment flexibility rather than simply “saving money.”
There are situations where that trade is still worthwhile, but it should be intentional.
Could Consolidation Increase Your Total Interest?
Yes.
Extending repayment is the most obvious reason.
Even if the new mortgage rate is lower than the second mortgage rate, the second balance can remain outstanding much longer when it is absorbed into a new long-term first mortgage.
The first mortgage balance can also become more expensive if the new rate is higher than the existing first-mortgage rate.
The only reliable solution is to model both paths.
Compare the scheduled interest and principal of keeping the existing loans against the new mortgage over the period you actually expect to keep the debt.
Should You Refinance Before or After Paying Down the Second Mortgage?
Paying down the second mortgage first can reduce combined leverage and the size of the refinance.
That may improve the structure of the new loan in some circumstances.
The drawback is using cash that could otherwise remain available for emergencies, closing expenses or other priorities.
A homeowner should not empty a healthy emergency fund merely to make a refinance application look cleaner without understanding whether the additional equity will materially change the offer.
Ask prospective lenders how different second-mortgage balances would affect the proposed terms before deciding how much cash to commit.
What If Your Home Value Has Fallen?
A declining home value can make a two-lien refinance significantly harder.
The balances remain the same while the equity cushion becomes smaller.
The CFPB specifically notes that refinancing can become more difficult with a second mortgage when the home’s value has declined. CFPB guidance on piggyback second mortgages and refinancing
A lower value can affect CLTV, the second lender’s willingness to subordinate and the new lender’s ability to approve the requested mortgage structure.
This is why an optimistic online home-value estimate should not be treated as the final number supporting the refinance.
What If You Are Already Struggling With Both Payments?
A refinance should not be assumed to be available simply because the existing payment structure has become difficult.
Borrowers experiencing financial hardship may face credit, income or payment-history issues that affect normal refinance qualification.
If payments are already being missed or foreclosure risk is developing, waiting for an ordinary refinance to solve the situation can be dangerous.
The CFPB provides mortgage-help resources and directs struggling homeowners toward HUD-approved housing counseling when appropriate.
The priority in that situation is obtaining qualified assistance early rather than adding late fees and missed payments while hoping refinance approval will eventually arrive.
A Better Decision Test: What Exactly Are You Trying to Fix?
Before requesting mortgage quotes, identify the problem.
If the first mortgage is expensive and the second mortgage is expensive, combining them may be a natural candidate.
If the first mortgage is excellent but the second mortgage is expensive, changing only the second loan deserves serious consideration.
If both loans are affordable and competitively priced, refinancing may create activity without creating value.
If the problem is only that two payments are inconvenient, automatic payment systems may solve the administrative issue without thousands of dollars in refinancing costs.
The financing structure should solve the actual problem rather than merely produce a new mortgage.
Use the Two-Loan Replacement Test
A simple framework can make this decision much easier.
First, calculate the combined current position:
First mortgage balance + second mortgage balance.
Then calculate the combined current monthly obligation:
First mortgage payment + second mortgage payment.
Next, identify the remaining term and interest rate of each loan independently.
Now compare the proposed refinance using five questions:
Will the required monthly payment fall?
Will the expected interest cost over my holding period fall?
How much will I pay in refinance costs?
Will any debt remain outstanding substantially longer?
How long must I keep the new mortgage before the transaction becomes worthwhile?
If the new loan produces a convincing answer across those questions, consolidation has a real economic argument.
If the only attractive answer is the smaller monthly payment, examine the extended term carefully before proceeding.
Frequently Asked Questions About Refinancing a First and Second Mortgage
Can you refinance a first and second mortgage into one loan?
Yes, borrowers can sometimes refinance a first and second mortgage into one new mortgage when they meet the lender and loan-program requirements. The new loan generally needs enough proceeds to satisfy the existing secured debts being consolidated, and the transaction must meet applicable equity, underwriting and lien requirements.
Can I refinance my first mortgage and keep my second mortgage?
Potentially. The second mortgage may need to remain subordinate to the new first mortgage, which can require the second lender to approve a subordination request. Approval is not automatic, so borrowers should identify the second lien early in the refinance process.
What does subordination mean when refinancing?
Subordination allows an existing junior mortgage to remain behind a newly refinanced first mortgage in lien priority. Without an acceptable subordination arrangement, an existing second mortgage can interfere with the new lender obtaining the senior lien position required for the refinance.
Is it better to combine a first and second mortgage?
It depends on the rates, balances, remaining terms, closing costs and property equity. Combining both loans can simplify payments and reduce the cost of an expensive second mortgage, but it can be a poor trade when it requires replacing a large first mortgage that already has very favorable terms.
Can I refinance just my second mortgage?
Potentially. Refinancing only the second mortgage can preserve a favorable first mortgage while replacing the debt that actually needs improvement. The new second lender will still evaluate the existing first lien, property value, borrower qualification and combined loan-to-value ratio.
Does a HELOC affect refinancing my first mortgage?
Yes. A HELOC can remain a lien against the property even when its current balance is low or zero. Depending on the transaction, it may need to be paid off, closed, modified or subordinated so the new first mortgage can obtain the required lien position.
What is CLTV when refinancing two mortgages?
CLTV is the combined loan-to-value ratio. It compares the relevant balances of the first and second mortgages with the property’s value. A higher CLTV means more of the property’s value is already supporting secured debt and can affect qualification or available refinance structures.
Final Verdict
You can often refinance a first and second mortgage together, but the fact that consolidation is possible does not establish that consolidation is financially superior.
The cleanest structure is replacing both existing liens with one new mortgage, which gives the homeowner one payment and one repayment schedule. That simplicity can be valuable when both existing loans are expensive, the second mortgage carries an uncomfortable payment structure or the new mortgage produces meaningful savings after closing costs.
The alternative is refinancing only the first mortgage and keeping the second loan. That can be the stronger choice when the second mortgage has attractive terms, although the junior lender may need to approve subordination so the new refinance mortgage can occupy first position.
The most dangerous mistake is focusing only on the expensive second mortgage while ignoring the size and quality of the first mortgage. A dramatic rate reduction on a $40,000 second loan can be overwhelmed by a modest rate increase applied to a $350,000 first mortgage.
Run the numbers as a combined household debt structure. Compare the two current payments, both interest rates, both remaining terms, combined secured balance, property value, CLTV, refinance costs and the proposed new mortgage over the period you realistically expect to keep it.
Use the first and second mortgage consolidation refinance calculator before deciding, because this is exactly the kind of refinance where a lower monthly payment can conceal a much longer repayment period.
The strongest refinance is the one that improves the whole two-loan position, not simply the one that makes the second mortgage disappear.