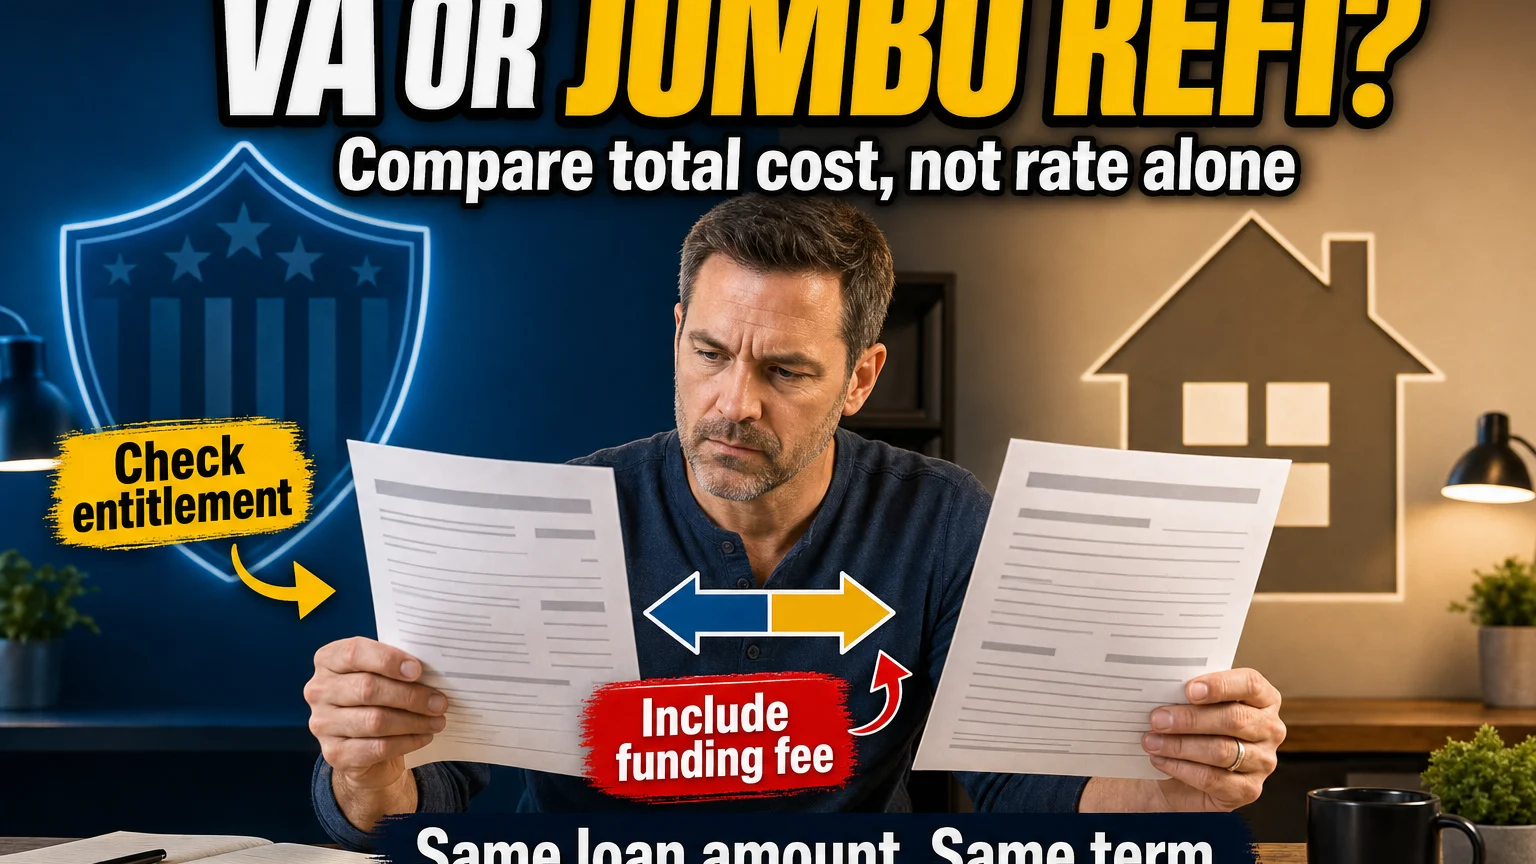
If you qualify for VA-backed financing and are refinancing a large mortgage, compare the VA option before assuming a conventional jumbo refinance is the natural choice. VA-backed financing can remain available above the conventional conforming-loan boundary, while a conventional jumbo mortgage follows private lender and investor standards. The winner depends on your entitlement, refinance type, property value, current mortgage, funding-fee treatment, lender pricing and how long you expect to keep the replacement loan.
The fastest way to compare them is to put both lenders on the same footing. Ask for approximately the same loan amount, the same 30-year fixed term, the same property-value assumption and quotes issued as close together as practical, then compare the rate, APR, points, lender credits, upfront costs, funding fee, final mortgage balance and monthly principal-and-interest payment. A lower advertised rate can lose once those differences are converted into dollars.
| Decision Factor | VA-Backed Large-Balance Refinance | Conventional Jumbo Refinance | Decision Cue |
|---|---|---|---|
| Eligibility | Requires qualifying VA home-loan eligibility and the applicable refinance requirements. | Available according to the lender’s jumbo credit, income, reserve, equity and property rules. | Verify VA eligibility first, then compare actual approval structures. |
| Conforming limit | Full and partial entitlement situations are treated differently; the conforming limit is not a universal VA borrowing ceiling. | The mortgage is considered jumbo because its balance exceeds the applicable conforming boundary. | Do not apply conventional jumbo logic directly to VA entitlement. |
| Program fee | An applicable VA funding fee may materially affect the transaction unless an exemption applies. | No VA funding fee, although lender fees, points and other jumbo pricing adjustments may apply. | Compare total dollars, not one fee in isolation. |
| Monthly mortgage insurance | The VA program does not require monthly private mortgage insurance. | Requirements depend on the selected private jumbo structure and retained equity. | Check the actual payment structure rather than assuming either route is cheaper. |
| Best comparison | Same amount, term, value and cash objective as the jumbo quote. | Same amount, term, value and cash objective as the VA quote. | Normalize the scenarios before comparing rates. |
What “VA Jumbo Refinance” Actually Means
“VA jumbo” is primarily lender and mortgage-market terminology rather than the name of a separate VA refinance program. Conventional lending uses “jumbo” for mortgages above the applicable conforming-loan limit, while VA lending organizes qualification around entitlement, guaranty, property value, underwriting and the actual refinance program being used. That difference is why a borrower can see a lender advertise a “VA jumbo refinance” even though the underlying VA rules do not suddenly become a completely different benefit above one dollar threshold.
The FHFA conforming loan limit guidance explains that Fannie Mae and Freddie Mac are restricted from purchasing mortgages above the applicable conforming-loan limit and that loans above that level are called jumbo loans. Those limits are updated periodically and can differ in designated higher-cost areas, so the applicable current limit should be checked when the loan is evaluated rather than hard-coded permanently into an evergreen comparison. Conventional jumbo status therefore begins with the relationship between the mortgage balance and the current conforming boundary.
VA entitlement follows another framework. The VA home loan entitlement and limits guidance explains that full entitlement does not impose the same VA loan-limit constraint that applies when entitlement has already been used and not fully restored, although the lender still decides what the borrower can afford and the property value still constrains the transaction. A large VA-backed mortgage can consequently sit above the conventional conforming threshold without becoming a conventional jumbo mortgage.
First Identify Which VA Refinance You Are Actually Comparing
The phrase “VA jumbo refinance” does not tell you whether the borrower should be using an IRRRL or a VA cash-out refinance. That distinction matters because the two transactions solve different problems, follow different rules and can produce very different cost structures. Before comparing VA with conventional jumbo financing, establish the correct VA lane.
- Existing VA mortgage + rate or payment improvement + no equity withdrawal: Start with an VA Streamline Refinance – IRRRL comparison. An IRRRL is specifically designed to refinance an existing VA-backed mortgage and does not permit the borrower to receive cash from the loan proceeds.
- Existing non-VA mortgage being converted into VA financing: The transaction generally belongs in the VA cash-out refinance framework even when the homeowner’s real objective is mortgage replacement rather than taking a large check at closing.
- Existing mortgage + meaningful equity withdrawal: Compare the transaction under the VA cash-out refinance rules because the amount of new debt, retained equity, funding fee and whole-mortgage repricing become central to the decision.
- Need only a relatively small amount of extra borrowing: Compare whether preserving the existing first mortgage and using a second-lien structure would be more efficient than replacing the entire balance. The second-mortgage refinancing guide explains that separate debt structure in more detail.
The VA IRRRL guidance confirms that an IRRRL is limited to refinancing an existing VA-backed mortgage, while the VA cash-out refinance guidance explicitly includes refinancing a non-VA mortgage into a VA-backed loan. That program distinction should be made before rates are compared because a borrower can otherwise place two fundamentally different refinance transactions beside each other and assume the difference is merely pricing.
How Full and Partial VA Entitlement Change a Large Refinance
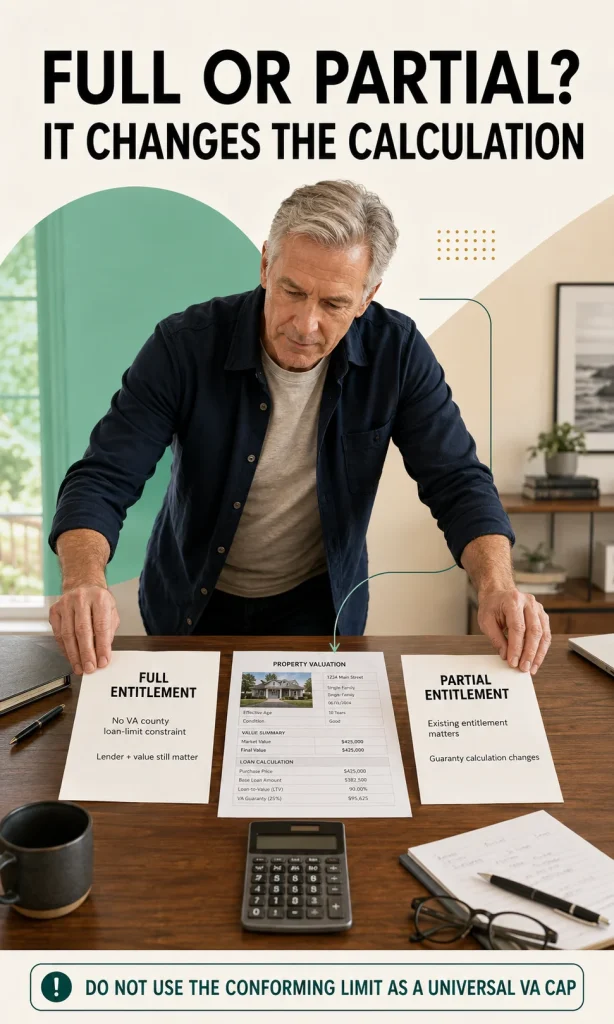
Full entitlement matters because the conventional conforming threshold is not automatically the ceiling on the VA guaranty. VA guidance states that for a borrower with full entitlement, the guaranty on a loan above the basic entitlement threshold can cover up to 25% of the loan amount, subject to lender approval and the supported property value. The practical borrowing limit therefore comes from the complete underwriting and collateral picture rather than from treating the conventional conforming limit as a universal VA cap.
Partial entitlement requires more care. If entitlement remains charged to another VA loan or has otherwise not been fully restored, the current one-unit conforming-loan limit can become part of the remaining-guaranty calculation. That can change how much VA guaranty is available and, depending on the transaction and lender, can affect the equity or cash contribution required to support a large mortgage.
This is one reason borrowers should avoid relying on a lender’s generic “jumbo begins here” graphic to determine VA qualification. The Certificate of Eligibility, entitlement already used, entitlement restored for the refinance and the property’s VA reasonable value can all matter. Two borrowers pursuing the same mortgage balance can therefore receive materially different VA structures even before rate pricing is considered.
What a Conventional Jumbo Refinance Does Differently
A conventional jumbo refinance replaces the existing mortgage with private financing above the applicable conforming-loan boundary. Because the mortgage does not fit within the standard Fannie Mae or Freddie Mac acquisition limit, the lender or investor establishes its own large-loan underwriting and pricing requirements. Credit thresholds, reserve expectations, acceptable property types, maximum leverage and loan-size tiers can consequently vary from one jumbo lender to another.
This lender variation is important for strong borrowers because conventional jumbo pricing is not uniformly expensive. Someone with excellent credit, substantial liquidity, significant retained equity and a valuable banking relationship can receive aggressive pricing from a lender that wants that borrower profile. Another lender can view exactly the same mortgage less favorably, which makes lender shopping more consequential than comparing two generic program descriptions.
The absence of the VA funding fee is another potential advantage for the conventional route, but that advantage needs to survive the complete quote comparison. A jumbo lender may require more points, charge a higher rate, demand more retained equity or apply other pricing adjustments. Removing one VA-specific fee does not tell you which mortgage costs less.
How a 30-Year Fixed Term Changes the Comparison
A 30-year fixed structure makes the comparison cleaner because the repayment period and rate behavior can be held constant between the two offers. The VA lender handbook permits a cash-out refinance term up to the lesser of 30 years and 32 days or the remaining economic life of the property, while private jumbo lenders establish their own available term structures. When both quotes use approximately the same 30-year term, differences in rate, fees and mortgage amount become easier to isolate.
The 30-year payment should still be interpreted carefully because refinancing resets amortization. A homeowner who has already paid an existing mortgage for many years can lower the monthly payment partly by stretching the remaining balance over another long repayment period. That result can improve cash flow while increasing the amount of time principal remains outstanding.
For this reason, “mortgage price” should mean more than the note rate. A useful refinance price includes the rate, APR, discount points, lender charges, lender credits, applicable funding fee, financed costs, new principal balance and the payment produced by that structure. The rate is one input inside the price rather than the complete price itself.
Rate Alone Is a Weak Way to Choose Between VA and Jumbo
Mortgage advertisements are especially easy to misread on large balances because a small rate difference can look modest while producing a substantial dollar difference. At the same time, lenders can lower an advertised rate by charging discount points, and one point represents one percent of the applicable loan amount. The larger the mortgage becomes, the more important it is to convert rate and points into actual dollars.
Suppose one lender offers a slightly lower rate but requires two expensive points while another lender offers a slightly higher rate with minimal points. The first offer can become cheaper if the borrower keeps the mortgage long enough to recover the upfront cost, while the second can perform better when the homeowner expects to move, refinance again or pay the balance down aggressively. There is no useful rate comparison until the expected holding period is included.
Rate quotes should also be collected reasonably close together because mortgage pricing moves. The CFPB guidance for comparing Loan Estimates specifically warns that rates can change daily and recommends comparing the loan amount, interest rate, monthly principal-and-interest payment, upfront costs and lender credits. This is particularly valuable on a jumbo transaction because small percentage differences are being applied to a large principal balance.
The VA Funding Fee Can Change the Winner
An applicable VA funding fee can become a large dollar item on a large refinance, so it should be modeled separately rather than hidden inside the new principal balance. The current VA funding-fee schedule lists a 2.15% fee for first use and 3.3% after first use for VA-backed cash-out refinancing, while qualifying borrowers can be exempt. The fee can generally be paid at closing or financed, and financing it reduces the cash burden today while increasing the amount on which mortgage interest can accrue.
Funding-fee exemption status can therefore materially alter a VA-versus-jumbo comparison. A borrower who qualifies for an exemption removes a potentially significant upfront VA cost, while a non-exempt borrower needs to determine whether the VA rate, underwriting and other benefits compensate for the fee. The answer should be calculated rather than assumed.
A conventional jumbo refinance has no VA funding fee because it does not use the VA guaranty. It can still include origination charges, discount points, appraisal charges and lender-specific costs. The clean comparison is the complete cost to create each replacement mortgage.
| Number to Compare | VA Quote | Jumbo Quote | Why It Changes the Decision |
|---|---|---|---|
| Starting principal | Include financed funding fee and financed eligible costs where applicable. | Include any financed costs or additional debt being rolled into the loan. | A lower rate on a larger balance may not be the cheaper mortgage. |
| Interest rate | Use the actual personalized quote. | Use the actual personalized quote. | Do not compare advertised teaser rates. |
| Points | Convert the percentage into dollars. | Convert the percentage into dollars. | Large balances magnify point costs. |
| Monthly P&I | Calculate from the actual new principal and term. | Calculate from the actual new principal and term. | Payment answers the cash-flow question, not total cost by itself. |
| Upfront loan cost | Separate funding fee, points and ordinary closing costs. | Separate points, origination and ordinary closing costs. | This is needed for break-even analysis. |
| Balance after your likely holding period | Project the remaining principal after the same number of years. | Project the remaining principal after the same number of years. | A lower payment can hide slower principal reduction. |
The Hidden Cost Is Often Repricing the Mortgage You Already Have
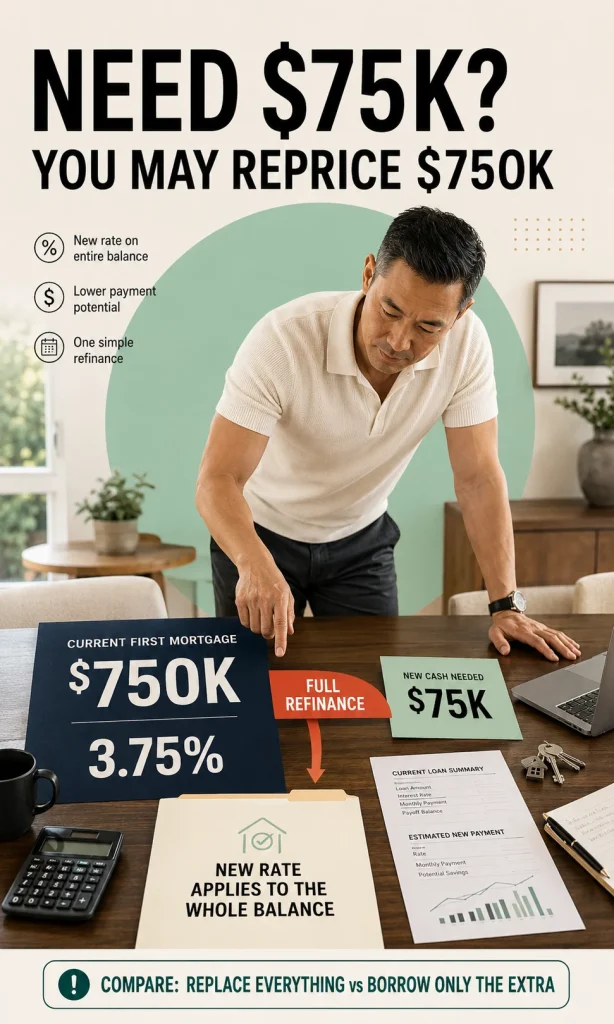
A refinance replaces the existing first mortgage, which means the new rate applies to much more than any additional money being borrowed. If a homeowner owes $750,000 at a particularly favorable fixed rate and wants another $75,000, a cash-out refinance is effectively asking whether it makes sense to reprice the existing $750,000 in order to obtain the additional $75,000. That relationship can outweigh a superficially attractive cash-out offer.
This is why the existing mortgage should always be treated as the control case. Record its balance, rate, remaining term and payment before comparing any new offer. A replacement mortgage has to improve the household’s real objective enough to justify giving up the financing already owned.
The issue becomes especially important when current mortgage rates are materially above an older first-mortgage rate. In that situation, a second mortgage or HELOC may carry a higher rate on the incremental borrowing but preserve the much lower rate on the far larger first-mortgage balance. Comparing only the rate on the new money can therefore produce the wrong conclusion in either direction.
When the VA Route Has the Stronger Case
VA-backed large-balance refinancing deserves particular attention when eligibility is established, entitlement supports the transaction and the actual VA quote is competitive after the funding fee is included. The case becomes stronger when the conventional jumbo lender requires materially more retained equity, substantially higher pricing or other underwriting conditions that make the private jumbo structure expensive. A borrower with a funding-fee exemption can see the VA comparison improve even further.
The VA route can also be attractive when the borrower is converting a non-VA jumbo mortgage into VA-backed financing and receives a meaningfully better complete loan structure. The relevant improvement may come from the rate, payment, equity treatment or combination of terms rather than one isolated feature. Qualification still depends on the lender’s credit and income standards and the supported property value.
VA cash-out underwriting also provides a useful technical boundary: the lender handbook states that a cash-out refinance generally requires a full appraisal, credit information and underwriting, while the maximum loan amount may not exceed 100% of the property’s VA reasonable value under the core rule. Lenders can still impose overlays that are more conservative than the VA maximum, which is another reason an advertised theoretical maximum should not be confused with an actual approval.
When Conventional Jumbo Can Be the Better Refinance
A conventional jumbo refinance can win when the private lender offers unusually strong pricing to a borrower with excellent credit, substantial liquidity and a large equity cushion. Relationship pricing can also matter at institutions that value deposits, investments or other banking business. In these cases, the conventional quote can compete effectively even though VA financing is available.
The conventional route can also become more attractive when the borrower is not exempt from the VA funding fee and the fee adds a large amount to the transaction. Avoiding the fee does not automatically make conventional financing cheaper, but it removes one significant cost from that side of the comparison. The remaining rate, points, lender costs and loan amount then determine whether the advantage survives.
Some borrowers may also prefer not to restructure VA entitlement for a particular transaction because they expect to use the benefit differently later. That is a personal strategic consideration rather than a universal financial rule. It should be evaluated separately from the dollar comparison so an entitlement preference does not obscure an otherwise more expensive mortgage.
Five Checks Before You Choose
- Confirm the correct VA refinance program. If the current mortgage is already VA backed and the objective is simply a lower rate or more stable payment without taking cash, compare IRRRL first. A non-VA-to-VA refinance or meaningful equity withdrawal usually belongs in the cash-out framework.
- Verify full versus partial entitlement. Do not infer entitlement from the mortgage balance alone. Use the Certificate of Eligibility and have the VA lender explain how existing entitlement charges, restoration and guaranty affect the proposed refinance.
- Make both quotes describe the same transaction. Use the same approximate loan amount, 30-year fixed term, property value and cash objective. Otherwise the borrower can mistake differences created by loan size for differences created by the mortgage program.
- Convert every percentage into dollars. Calculate the funding fee, discount points, lender charges, new principal balance, monthly payment and equity remaining. A percentage that looks small can represent a large amount of money on a jumbo-sized mortgage.
- Compare the result at your likely exit date. Estimate what each mortgage will have cost and how much principal will remain after the period you realistically expect to keep it. A five-year decision can produce a different winner from a twenty-year decision.
Common VA Jumbo Refinance Mistakes
The first common mistake is treating the conforming-loan limit as a universal VA maximum. That boundary defines conventional jumbo status, while VA entitlement and guaranty rules require a different analysis. Full and partial entitlement should therefore be established before the borrower concludes that the requested refinance is “too large” for VA financing.
The second mistake is comparing rate advertisements rather than matched Loan Estimates. A VA quote at one balance with several points and a jumbo quote at another balance with few points are not comparable simply because both display a 30-year fixed rate. Normalize the transaction first.
The third mistake is forgetting the existing mortgage. A homeowner can spend a great deal of money obtaining additional liquidity while unnecessarily repricing a large low-rate first mortgage. The benefit of the new transaction must exceed the value surrendered.
The fourth mistake is assuming maximum borrowing capacity is the target. A lender approving a large VA or jumbo mortgage establishes what the underwriting permits, not how much secured debt the homeowner should choose. Retained equity, monthly cash flow and resilience after closing remain household decisions.
How to Compare the Loan Estimates
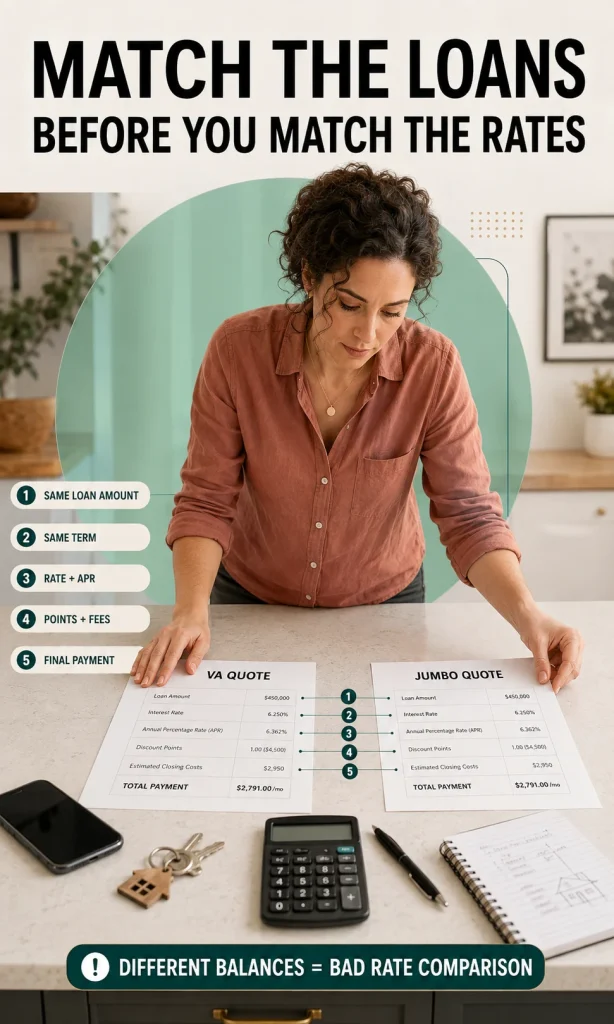
Ask at least two lenders to price the VA route and two capable lenders to price the conventional jumbo route when practical. Request the quotes within a reasonably tight time window because market pricing moves, and provide each lender with essentially the same loan amount, property-value estimate, occupancy, term and cash objective. This makes the comparison substantially more useful.
Then compare the Loan Estimates line by line. The Consumer Financial Protection Bureau’s Loan Estimate comparison guidance directs borrowers to look at the loan amount, rate, principal-and-interest payment, upfront loan costs and lender credits, while also recognizing that rates can move between different quote dates. Those same fields form the foundation of a strong VA-versus-jumbo refinance comparison.
Finally, calculate the consequences rather than stopping at the form. Determine the new principal, monthly payment difference, upfront cost, break-even period and expected remaining balance at realistic future dates. That turns the lender documents into a household decision instead of a rate-shopping exercise.
Frequently Asked Questions
Is VA jumbo refinance a separate VA mortgage program?
No separate universal VA program is created simply because the mortgage is above the conventional conforming-loan boundary. “VA jumbo” is commonly used by lenders to describe a large VA-backed mortgage, while the actual VA transaction still follows entitlement, guaranty, appraisal, underwriting and the applicable refinance program. Start by determining whether the transaction is an IRRRL or a cash-out refinance and then evaluate the large-balance structure.
Can a VA refinance be larger than the conforming loan limit?
A large VA-backed refinance can exceed the conventional conforming threshold, but entitlement status, guaranty, property value, underwriting and lender overlays still matter. Full entitlement and partial entitlement situations are treated differently, so the current conforming limit should not be treated as one universal VA ceiling. Ask the lender to explain the entitlement and guaranty calculation for the actual property and transaction.
Can I refinance a conventional jumbo mortgage into a VA loan?
An eligible borrower may be able to refinance a non-VA mortgage into VA-backed financing through the applicable VA cash-out refinance framework. The borrower must still satisfy VA and lender requirements, live in the home being refinanced as required for that transaction, and obtain the necessary appraisal and underwriting approval. Compare the complete new VA structure with retaining or conventionally refinancing the existing jumbo mortgage.
Is a VA jumbo refinance rate always lower than a conventional jumbo rate?
No. VA-backed financing can be competitively priced, but lenders set their actual rates, points and fees, while private jumbo lenders can also price aggressively for strong borrower profiles. Compare personalized quotes issued close together in time and include the funding fee, points, credits and final mortgage amount before deciding which rate is really cheaper.
Does full VA entitlement mean I can refinance any mortgage amount?
No. Full entitlement changes the VA guaranty and loan-limit analysis, but the lender still has to approve the borrower and the property must support the proposed mortgage. Credit, income, debts, assets, appraisal and lender overlays can all constrain the final amount. A theoretical VA program maximum should never be treated as a guaranteed approval.
Is a 30-year fixed VA refinance better than a 30-year conventional jumbo refinance?
Neither structure is automatically better simply because both use a 30-year fixed term. Compare the same approximate loan amount and then evaluate rate, APR, points, funding-fee treatment, lender credits, closing costs, monthly principal and interest, retained equity and expected holding period. The better mortgage is the one that performs better for the borrower’s actual financial objective and likely timeline.
Should I refinance a low-rate jumbo mortgage just to take cash out?
Be careful when the amount of cash needed is small relative to a large first-mortgage balance carrying a favorable rate. A cash-out refinance reprices the entire replacement mortgage, which can make obtaining a relatively small amount of additional money expensive. Compare a HELOC or second-mortgage structure when preserving the current first mortgage may have substantial value.
Next Steps
Start by identifying the refinance job rather than requesting rates immediately. Determine whether the goal is to lower the rate, stabilize the payment, convert a non-VA mortgage into VA-backed financing, withdraw equity or restructure a large existing mortgage. That one decision determines which VA rules belong in the comparison.
Next, confirm entitlement and obtain matched quotes. Ask VA and conventional jumbo lenders to price approximately the same mortgage amount and 30-year fixed term using the same property-value assumption, then separate the funding fee, points, lender credits and financed costs so the real starting principal is visible. A borrower should be able to explain why the two proposed mortgage balances differ before comparing their rates.
Finally, compare both replacement loans with the mortgage you already have. Look at the immediate payment, upfront expense, whole-mortgage repricing, projected balance during your likely holding period and equity left after closing. The strongest refinance is the one that solves the household’s actual problem at the lowest acceptable long-term cost, whether the winning structure happens to be VA backed or conventional jumbo.