A VA cash-out refinance replaces eligible mortgage debt or another qualifying recorded property lien with a new VA-backed first mortgage, and the new financing can provide cash when the replacement loan exceeds the debt and settlement obligations being paid. It can also refinance a conventional, FHA or other non-VA mortgage into VA financing, so the program serves a broader purpose than simply withdrawing equity. The real decision is whether the new mortgage improves the household’s position enough to justify replacing the financing already attached to the home.
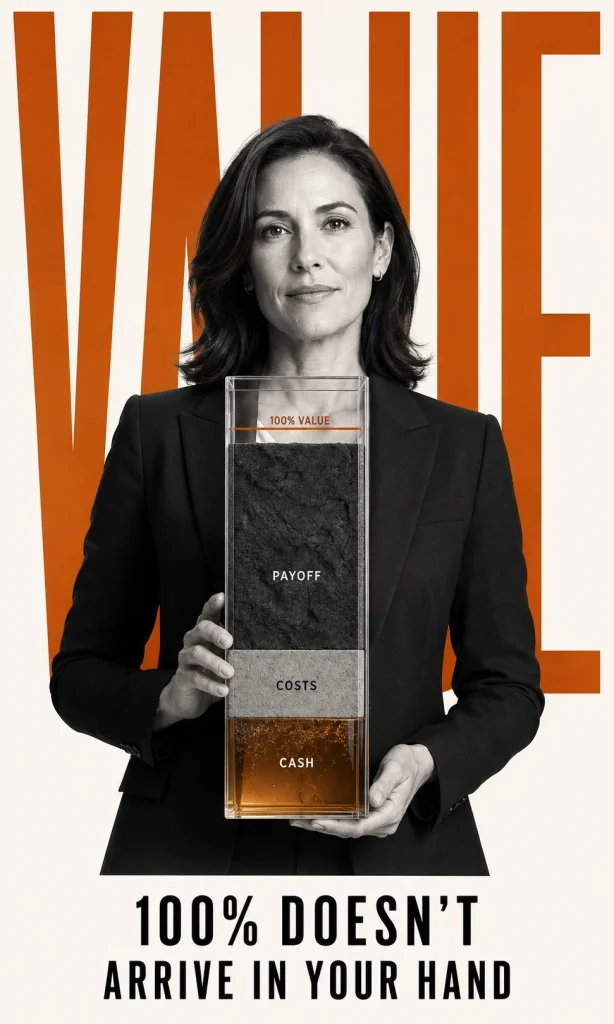
VA financing can be unusually flexible because the program’s regular cash-out framework can permit a loan amount reaching 100% of VA reasonable value, subject to entitlement, underwriting, the lender’s own policy and the remaining VA requirements. That percentage is a financing ceiling rather than a promise that every lender will approve 100% or that the homeowner will receive the entire difference as spendable cash. Existing mortgage payoffs, other liens, closing expenses and an applicable VA funding fee all influence what remains after settlement.
VA also divides cash-out refinancing into Type I and Type II, and that distinction changes how several rules should be interpreted. Type I describes a replacement loan whose new amount, including the VA funding fee, does not exceed the payoff amount of the debt being refinanced, while Type II exceeds the relevant payoff and can remove home equity. The distinction becomes particularly important when a VA-backed mortgage is refinancing another VA-backed mortgage because seasoning, interest-rate reduction and fee-recoupment protections can apply.
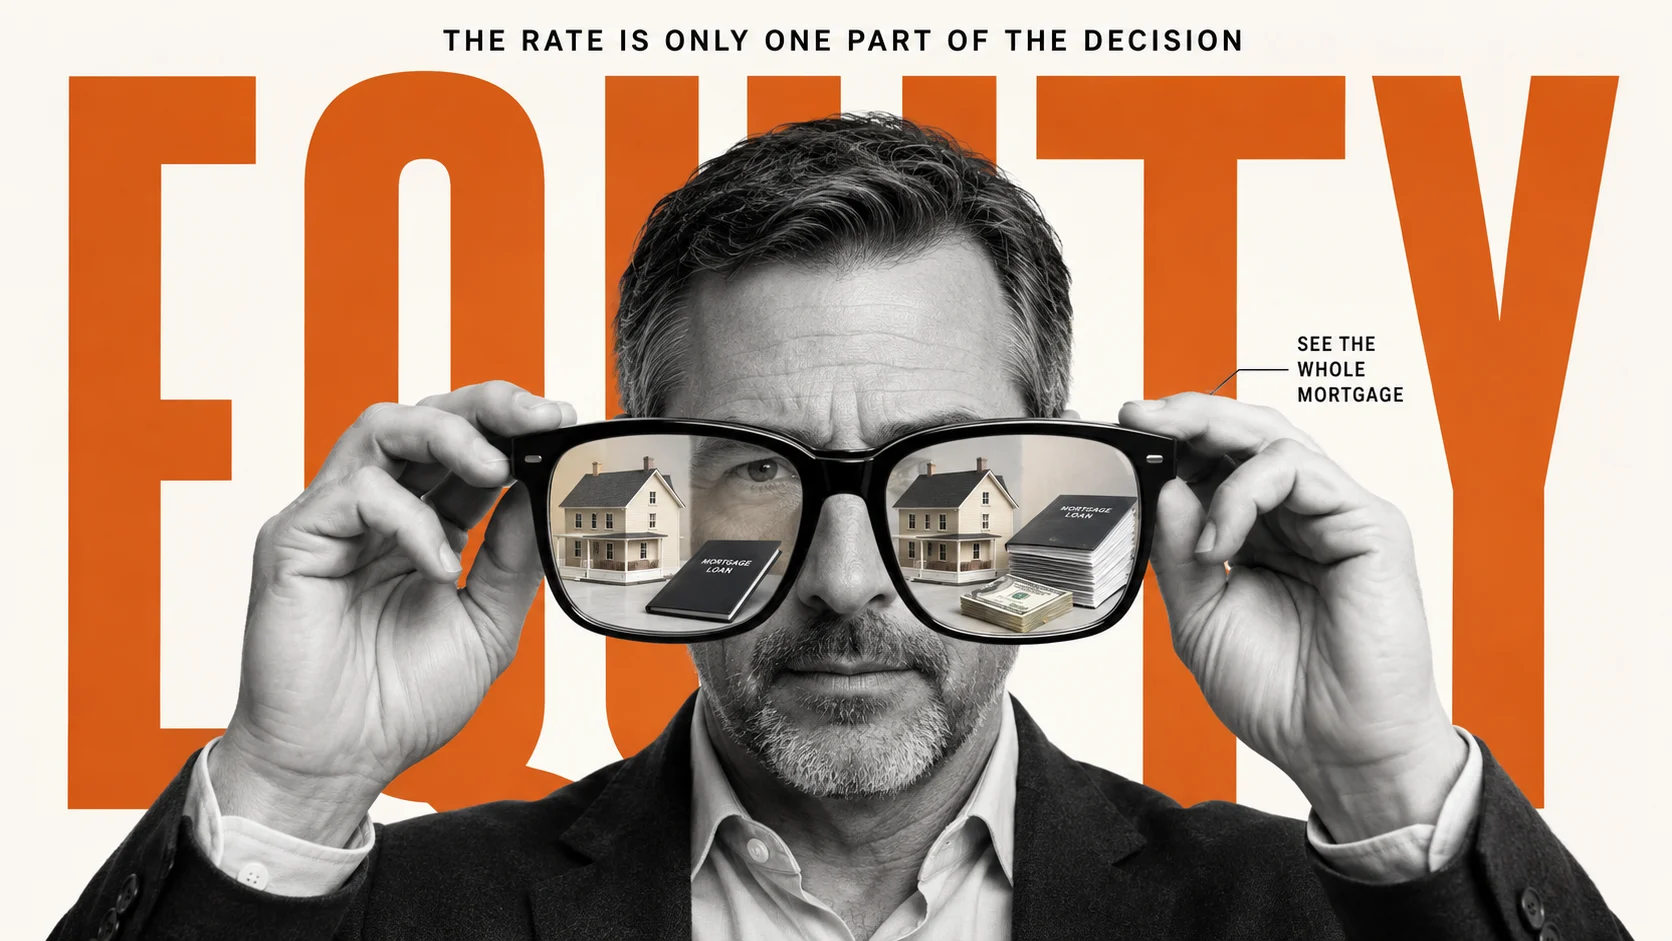
The most expensive part of a cash-out refinance is sometimes hidden in plain sight: the new rate applies to the entire replacement mortgage, rather than only to the additional cash being borrowed. Someone who owes $325,000 on an unusually low-rate mortgage and needs another $50,000 may end up repricing roughly $375,000 plus applicable costs in order to obtain that $50,000. A HELOC or second mortgage can consequently carry a higher rate on the new money while still producing a better household outcome because the valuable first mortgage remains untouched.
What Is a VA Cash-Out Refinance?
A VA-backed cash-out refinance is a VA-guaranteed replacement mortgage that can refinance an existing mortgage or other eligible recorded property lien and can provide additional cash when the new loan is large enough to exceed the debts and settlement amounts being satisfied. The existing first mortgage does not have to be VA backed, which separates cash-out refinancing from the VA Interest Rate Reduction Refinance Loan. The current VA cash-out refinance guidance specifically describes both accessing home equity and refinancing a non-VA mortgage into VA-backed financing as potential uses of the program.
One easily missed restriction appears in the current VA lender rules: the standard cash-out guarantee is built around refinancing an existing mortgage or another indebtedness secured by a recorded lien. A property with no existing mortgage and no lien of record does not ordinarily fit the standard VA cash-out guarantee definition simply because the owner has substantial equity. Someone with a completely free-and-clear property should therefore discuss the financing objective with an experienced VA lender before assuming the usual cash-out structure applies, because another financing route may be required.
Type I and Type II VA Cash-Out Refinancing
A Type I transaction occurs when the new VA loan amount, including the VA funding fee, does not exceed the payoff amount of the mortgage being refinanced. Type I can still fall under VA’s cash-out refinance framework even when no meaningful cash is handed to the Veteran, because the classification is based on the relationship between the new mortgage amount and the debt payoff rather than on the marketing meaning of “cash out.” It can also involve refinancing either a VA-guaranteed loan or a non-VA mortgage.
A Type II refinance occurs when the replacement mortgage, including the funding fee, exceeds the mortgage or recorded liens being refinanced. This is the structure people usually imagine when discussing cash-out because the excess financing can convert part of home equity into cash proceeds after the applicable obligations are settled. The current VA Lenders Handbook Chapter 6 refinancing guidance contains the controlling Type I and Type II definitions lenders use.
The classification is not merely terminology because several consumer protections attach differently depending on the transaction. Certain VA-to-VA Type I refinances have specific rate-reduction and 36-month fee-recoupment requirements, while a Type II refinance follows the broader cash-out benefit and seasoning framework. Asking the lender to identify the transaction as Type I or Type II before comparing offers removes a surprising amount of confusion later.
VA Cash-Out Requirements at a Glance
Before comparing rates, separate the transaction into financing capacity, loan history, underwriting and economic benefit. A property can support a large mortgage from a valuation standpoint while the borrower’s income supports a smaller one, and a seasoned VA mortgage can still produce a poor refinancing decision when the existing rate is unusually attractive. The table below is therefore a screening framework rather than an approval promise.
| Decision Area | General VA Framework | What You Need to Verify |
|---|---|---|
| Existing debt | The transaction refinances existing mortgage debt or other qualifying recorded liens. | Identify every lien that will be paid, retained or subordinated. |
| Maximum program financing | The VA program maximum generally may not exceed 100% of VA reasonable value. | Confirm reasonable value, entitlement and the lender’s actual maximum LTV. |
| Type I | New loan including the funding fee does not exceed the relevant payoff. | Determine whether VA-to-VA rate and recoupment rules apply. |
| Type II | New loan exceeds the payoff and can convert equity into cash. | Calculate gross equity removal and actual net proceeds separately. |
| VA-to-VA seasoning | Federal seasoning applies when the debt being refinanced is VA guaranteed. | Use the actual loan dates and payment ledger rather than a rough month count. |
| Appraisal | VA reasonable value is established through the VA appraisal process. | Do not commit expected proceeds from an online value estimate alone. |
| Underwriting | Full credit and income underwriting applies. | Prepare income, employment, debts, assets and housing information. |
| Funding fee | Standard cash-out funding fee is currently 2.15% for first use and 3.3% after first use unless exempt. | Verify use history and exemption status before comparing final costs. |
A lender still has to evaluate entitlement, credit, income, residual income, property condition and any additional company requirements before the mortgage is approved. The table is most useful because it prevents one attractive number, such as appraised value or an advertised rate, from dominating a transaction that depends on several interacting variables. Once those inputs are known, the decision becomes much easier to model.
How Much Can You Borrow With a VA Cash-Out Refinance?
The current VA lender framework allows a regular cash-out refinance loan amount up to 100% of VA reasonable value, with the funding fee also required to remain inside that value boundary when it is financed. That makes VA different from an FHA cash-out refinance, which normally stops at a substantially lower percentage of eligible property value. The controlling maximum-loan treatment appears in the VA maximum loan amount guidance.
The 100% figure still does not mean that every borrower has access to an unlimited no-down-payment VA mortgage at any property value. Entitlement and guaranty considerations still matter, while lenders can impose their own cash-out LTV limits that are lower than VA’s outer program boundary. A lender offering 90% maximum cash-out financing can therefore be applying company policy rather than claiming VA itself has a universal 90% ceiling.
Consider a home with a VA reasonable value of $500,000 and a lender willing to approve a $450,000 replacement mortgage. If the current first-mortgage payoff is $335,000, there is a gross difference of $115,000 before another lien, closing expenses and funding-fee treatment are considered. That gross difference is useful for planning, but it is not yet the amount the homeowner should expect to receive.
How Much Cash Do You Actually Receive?
Net proceeds are produced only after the settlement obligations are deducted from the approved financing. Begin with the base amount supported by the lender and appraisal, then subtract the mortgage payoff, other liens being satisfied and transaction expenses that reduce available proceeds. The final cash movement can also change because of escrow adjustments, prepaid items and the funding-fee structure.
A homeowner therefore needs two numbers on the same page: equity removed and cash actually received. Removing $100,000 of equity can result in materially less than $100,000 arriving as spendable proceeds when part of the financing pays settlement expenses or other secured obligations. Treating the gross equity difference as disposable cash can cause a project budget to be overcommitted before the loan reaches closing.
Before You Use the Maximum VA Amount
- Write down the amount of cash that solves the actual problem. A $45,000 renovation does not automatically justify a $100,000 equity withdrawal merely because the appraisal supports the larger mortgage. Extra borrowing creates additional principal, interest and potentially a larger funding fee for a non-exempt borrower.
- Compare the new total mortgage with today’s payoff. Cash received should always be displayed beside the amount by which mortgage debt increases after the transaction. A borrower can receive $70,000 while increasing secured debt by substantially more once other transaction components are included.
- Measure the equity remaining after closing. VA’s program maximum is a boundary rather than a target for household leverage. Retaining more equity can create additional flexibility if property values decline, a move becomes necessary or another major financial need appears later.
- Compare the cash-out mortgage with borrowing only the incremental amount. A HELOC or second mortgage can be more expensive on the new dollars while preserving an unusually valuable first-mortgage rate. The correct comparison is the cost of the entire household debt structure rather than one headline percentage.
Why Your Current Mortgage Rate Can Matter More Than the VA Cash-Out Rate
A cash-out refinance applies the replacement rate to the full mortgage that emerges from closing. If $320,000 of an existing mortgage is being replaced so that another $50,000 can be borrowed, the homeowner is making a financing decision involving roughly $370,000 plus applicable transaction amounts. Focusing only on the price of the new $50,000 understates the scope of the refinance.
This matters most when the existing first mortgage was originated during a much lower-rate period. Giving up an unusually cheap rate on hundreds of thousands of dollars can create a larger cost than the benefit gained from borrowing a smaller amount of cash at the new VA rate. The question becomes whether the household should reprice the whole mortgage to obtain the incremental money.
A first-and-second mortgage comparison becomes particularly useful in that situation because keeping the first mortgage can be an asset in itself. A junior lien should still be evaluated for rate risk, payment structure and fees, but the higher rate printed on the HELOC does not automatically make it more expensive overall. Only the new borrowing receives that junior-lien rate while the much larger first mortgage remains untouched.
What Is the VA Funding Fee for Cash-Out Refinancing?
The standard VA cash-out funding fee is currently 2.15% for first use of the VA home loan benefit and 3.3% after first use for borrowers who are not exempt. Unlike the purchase-loan schedule, the cash-out refinance percentages do not decline because the homeowner happens to leave more equity in the property. The current figures and exemption categories are published in the VA funding fee and closing cost schedule.
The difference between first and subsequent use can become substantial on a large mortgage. A simplified 2.15% calculation on $400,000 equals $8,600, while 3.3% equals $13,200, before considering the exact calculation basis used for the real loan. That gap is large enough that benefit-use history should be confirmed before deciding whether the refinance cost is acceptable.
Certain borrowers are exempt from the VA funding fee, including qualifying Veterans receiving or entitled to receive compensation for service-connected disabilities and other specified categories. An exemption can materially alter both cash needed and the final mortgage balance, particularly on a large Type II cash-out loan. The lender should confirm exemption status through the VA process rather than estimating it from memory.
VA Loans Do Not Add Monthly Mortgage Insurance
VA-backed mortgages do not impose monthly mortgage insurance in the manner associated with FHA or some low-equity conventional financing. For a borrower moving from an FHA mortgage carrying monthly MIP into VA financing, eliminating that insurance expense can create a meaningful improvement even before cash-out proceeds are considered. VA itself identifies the absence of monthly mortgage insurance as one of the program’s significant features.
That does not mean an FHA-to-VA cash-out refinance is automatically cheaper. The new interest rate, funding fee, closing costs, mortgage amount and term still need to be compared with the mortgage already in place. Removing one recurring expense can be valuable while another part of the transaction becomes more expensive.
Does a VA Cash-Out Refinance Require an Appraisal?
Yes. The lender orders a VA appraisal because VA reasonable value is central to the maximum loan calculation and the lender needs an acceptable property value before finalizing cash-out capacity. The official VA cash-out application guidance specifically describes the appraisal as part of the refinancing process.
A lower appraisal can change the transaction even when the homeowner’s income and credit remain unchanged. If the plan assumed $600,000 of reasonable value and the appraisal supports $550,000, available financing can fall materially depending on the lender’s LTV limit. The cash target should therefore retain enough flexibility to survive a valuation result below the homeowner’s original estimate.
Online estimates can still be useful for early scenario planning, but they should not be treated as committed proceeds. A contractor deposit, tuition payment or debt settlement should not depend entirely on an expected cash figure that has not survived appraisal and underwriting. The practical borrowing number becomes reliable only as the lender resolves those variables.
How Long Do You Have to Wait for a VA-to-VA Cash-Out Refinance?
VA’s federal cash-out seasoning requirement applies when the mortgage being refinanced is itself VA guaranteed. Current VA guidance uses a 210-day seasoning framework together with payment-history requirements, and lenders need the actual loan dates and payment record rather than an informal estimate based on when the home was purchased. The controlling seasoning provisions are contained in the current VA refinancing seasoning guidance.
For Type I VA-to-VA refinancing, the first monthly payment due date on the existing VA mortgage generally needs to be at least 210 days before the new note date, and six consecutive monthly payments need to have been made in full in the months they were due. The consecutive-payment requirement makes the servicing history important because simply having six payments posted somewhere in the loan history does not necessarily prove the required sequence. A lender should confirm the actual eligibility date from its payment ledger.
When the debt being replaced is not VA guaranteed, VA’s federal VA-to-VA cash-out seasoning rule does not apply in the same manner. A private lender can still impose its own ownership, mortgage-age or seasoning policy, so a borrower refinancing a conventional or FHA mortgage should ask whether a quoted waiting period comes from VA or from that particular lender. The broader refinance timing guide can help separate those program-specific clocks.
Some Type I VA-to-VA Refinances Need a Lower Rate
Certain VA-to-VA Type I transactions have an additional interest-rate reduction test. When an existing fixed-rate VA mortgage is refinanced into another fixed-rate Type I cash-out mortgage, current VA rules generally require the replacement rate to be at least 0.50 percentage point lower than the existing rate. The applicable Type I requirements appear in the VA Type I interest-rate reduction guidance.
Moving from fixed financing to an adjustable-rate Type I refinance creates a larger required reduction under the applicable VA rule. That difference reflects the additional future rate uncertainty the borrower accepts when moving into adjustable financing. The rate test should therefore be applied according to the actual old and new mortgage structures rather than through one universal cash-out percentage.
These Type I-specific rules should not be copied onto every VA cash-out transaction. A Type II equity-withdrawal refinance and a refinance of non-VA debt operate under different parts of the framework, even though all cash-out refinances still need a recognized net tangible benefit. Classifying the transaction correctly comes before interpreting the rate test.
The 36-Month Recoupment Rule Is Not Universal to Every VA Cash-Out
VA’s specific 36-month fee-recoupment requirement applies to VA-to-VA Type I cash-out refinancing. The lender divides applicable refinance fees, expenses and closing costs by the reduction in monthly principal-and-interest payment, and the resulting recoupment period must fit the applicable VA limit. Current VA Type I fee-recoupment guidance explains the calculation and the items that can be excluded under the statutory test.
A Type II refinance should not be presented as though this identical 36-month statutory test automatically governs every equity-withdrawal transaction. That is one of the places where generic VA refinance articles frequently blur IRRRL, Type I and Type II rules together. The absence of that particular statutory recoupment test still does not make Type II costs unimportant.
I would calculate a household cost comparison for every cash-out refinance regardless of the formal VA category. When the current first-mortgage rate changes substantially, a simple “closing costs divided by payment savings” calculation can be too narrow because the borrower is deliberately increasing debt and may not be reducing the payment at all. Comparing total loan balance, interest structure, cash received and retained equity provides a much more realistic view.
What Is the VA Net Tangible Benefit Requirement?
VA requires cash-out refinancing to provide at least one recognized net tangible benefit rather than existing solely as another mortgage transaction. Current rules allow several types of qualifying improvement, including circumstances involving a lower interest rate, lower principal-and-interest payment, elimination of monthly mortgage insurance, improved residual income, a shorter loan term, an ARM-to-fixed conversion or another qualifying structural benefit. The current VA cash-out net tangible benefit framework explains these recognized outcomes.
The presence of one VA-recognized benefit does not automatically mean the transaction is personally attractive. A refinance can satisfy the program’s test because it removes mortgage insurance while simultaneously increasing the loan balance enough to create a questionable long-term result. Program compliance establishes that the transaction has a recognized benefit, while household analysis determines whether that benefit is worth the complete cost.
VA also requires the lender to present a comparison of important characteristics of the existing and proposed mortgage and disclose the amount of home equity being removed. That disclosure deserves as much attention as the advertised cash proceeds because both numbers describe the same transaction from opposite directions. Cash enters the homeowner’s balance sheet at the same time that unencumbered equity leaves it.
Type I, Type II, IRRRL or Second Mortgage?
| Option | Best Fit | Main Trade-Off |
|---|---|---|
| Type I VA cash-out | Replacing eligible debt without increasing the new loan above the payoff. | VA-to-VA transactions can face specific rate and recoupment protections. |
| Type II VA cash-out | Replacing debt and converting part of home equity into cash. | Creates a larger mortgage and reduces retained equity. |
| VA IRRRL | Improving an existing VA mortgage when meaningful cash-out is not needed. | Cannot serve as a normal equity-withdrawal transaction. |
| HELOC or second mortgage | Borrowing incremental cash while preserving a valuable existing first mortgage. | Junior-lien rates and payment structures may be less attractive on the new money. |
The strongest option depends on what needs to change. Someone who already has a VA mortgage and only wants a lower rate should compare the VA Streamline Refinance (IRRRL) guide before assuming a full cash-out refinance is necessary. Someone who needs substantial equity proceeds or wants to convert non-VA financing into VA has a different decision.
What Can VA Cash-Out Proceeds Be Used For?
VA does not prescribe a narrow list of approved household uses for ordinary cash received from the refinancing proceeds. The current lender handbook states that proceeds beyond what is required to refinance the eligible mortgage or recorded liens may generally be taken as cash, and VA does not require a letter explaining the intended use of every dollar. That flexibility allows the homeowner to decide whether the equity is being used for repairs, education, debt consolidation or another legitimate household objective.
Flexibility should not be confused with low financial risk. Equity converted into mortgage debt remains secured by the home even after the original spending has disappeared, so borrowing for short-lived consumption can leave decades of repayment behind. The intended purpose should be valuable enough to justify placing that additional amount inside a long-term secured obligation.
Using VA Cash-Out to Consolidate High-Interest Debt
Consolidating high-rate credit-card or personal-loan debt can improve monthly cash flow because mortgage financing can carry a substantially lower interest rate than unsecured revolving debt. It can also improve residual income, which is one of the outcomes recognized within VA’s broader net tangible benefit framework. The immediate monthly relief can be meaningful for a household carrying expensive unsecured balances.
The risk is that unsecured debt becomes secured through the home while the repayment period may become dramatically longer. A $35,000 credit-card balance that could have been eliminated in several disciplined years can remain buried inside a 30-year mortgage if the borrower simply makes the required payment. Rebuilding the card balances afterward can leave the household with a larger mortgage and another round of unsecured debt.
Using VA Cash-Out for Home Improvements
Necessary repairs can provide a clearer reason for using equity because the proceeds are directed back toward the property. Roofing, structural repairs, accessibility work or replacement of major building systems can solve real housing problems while avoiding more expensive forms of short-term borrowing. The project budget should still be defined before the maximum available cash is requested.
Renovation cost and resale value are not automatically equal. A $60,000 improvement can create substantial lifestyle value while adding less than $60,000 to market value, and some highly personal upgrades can provide little financial recovery at sale. The borrowing decision should therefore reflect both the usefulness of the project and the cost of financing it.
VA Cash-Out Requires Full Underwriting
VA cash-out refinancing is not a streamlined underwriting process. The lender evaluates credit, employment, income, recurring obligations, residual income and the complete proposed housing payment before approving the mortgage. The official VA consumer guidance also notes that lenders commonly request recent pay information, W-2s and other supporting documents during the process.
Property value alone therefore cannot determine the loan amount. A home can support a $500,000 mortgage from a valuation perspective while the household’s qualifying income supports a smaller obligation. The final mortgage is determined by whichever meaningful constraint becomes binding in the actual file.
What Happens to a HELOC or Second Mortgage?
The new VA-backed mortgage must hold first-lien position. A second mortgage or HELOC that remains after closing therefore needs to remain subordinate to the replacement VA mortgage, and the junior lienholder must agree to that position. The subordination process can create additional documentation, cost and closing time.
The presence of a second lien also creates a decision opportunity rather than merely a paperwork issue. Paying it off inside a new VA mortgage can simplify the household debt structure, while keeping it separate may preserve a shorter repayment period or other favorable terms. Compare the balances and repayment schedules instead of assuming consolidation is automatically better.
How to Compare VA Cash-Out Rates
There is no single permanent “best VA cash-out rate” because the rate a borrower receives depends on market conditions, lender pricing, credit characteristics, loan amount, discount points and the complete transaction. VA itself advises borrowers to contact several private lenders because the Department guarantees eligible loans but does not originate the mortgage directly or set one universal retail refinance rate. Current-rate intent therefore needs fresh lender data rather than an evergreen article pretending one quoted percentage will remain correct indefinitely.
Compare quotes using approximately the same loan amount, term and cash proceeds. A lender providing $120,000 of cash cannot be judged against one providing $60,000 simply by comparing their interest rates because the underlying transactions are different. Standardizing the requested proceeds makes the Loan Estimates much more meaningful.
Discount points and lender credits deserve particular attention. One lender can advertise a noticeably lower rate by charging thousands of dollars upfront, while another can offer a slightly higher rate with enough credit to reduce closing expense. The best structure depends partly on how long the borrower expects to keep the replacement mortgage.
The Four Numbers That Reveal the Real Decision
Before signing, calculate maximum financing capacity, net cash received, whole-loan repricing cost and retained equity. Maximum financing tells you what the program and lender may allow, while net cash tells you what will actually arrive after the transaction obligations are handled. Those first two numbers prevent gross home equity from being confused with spendable proceeds.
Whole-loan repricing then shows what happens to the mortgage you already have. Retained equity finishes the analysis by showing how much ownership cushion remains after the cash is removed. A refinance becomes much easier to evaluate when all four numbers appear together instead of being discussed in separate lender conversations.
A personalized mortgage refinance calculator can help compare the payment and longer-term mortgage effect once an actual lender quote is available. For a cash-out transaction, however, the calculation should also record the cash received and equity remaining because payment alone cannot describe the full change in household wealth. A manageable payment can still accompany a much larger mortgage balance.
When a VA Cash-Out Refinance Has a Strong Case
The case becomes stronger when the borrower has a clear use for the cash, qualifies comfortably and is not surrendering an unusually valuable existing mortgage without compensation. Refinancing a non-VA mortgage into VA financing can also be attractive when doing so removes monthly mortgage insurance or materially improves the overall mortgage structure. A funding-fee exemption can improve the economics further.
A well-defined home improvement or disciplined consolidation of extremely expensive debt can provide a coherent reason for converting equity into secured financing. The new mortgage should still leave enough cash reserves and enough home equity to protect the household against an unexpected move, repair or income disruption. Borrowing less than the maximum can therefore make a strong transaction even stronger.
When VA Cash-Out Can Be a Weak Decision
The refinance becomes difficult to justify when a very low-rate first mortgage must be replaced simply to obtain a relatively small amount of new money. Repricing $300,000 or $400,000 of inexpensive existing debt to borrow another $40,000 can cost more than preserving the first mortgage and accepting a higher rate on the incremental borrowing. The comparison needs to include both debts rather than treating the new-money rate as the only variable.
Cash-out is also questionable when the proceeds have no defined purpose or when nearly every available dollar of equity is removed because the lender permits it. Home equity is household wealth and a financial cushion, while cash-out turns part of that wealth back into an obligation secured by the property. Eligibility to borrow and a good reason to borrow remain different questions.
Frequently Asked Questions About VA Cash-Out Refinancing
Can a VA cash-out refinance go to 100% LTV?
The VA program’s regular cash-out framework can permit a mortgage amount up to 100% of VA reasonable value, with a financed funding fee also required to fit within that value boundary. Individual lenders may impose lower maximum LTV limits, while entitlement and full underwriting can also constrain the actual loan amount. The 100% program ceiling should therefore be treated as an outer boundary rather than an automatic approval or a recommendation to remove all available equity.
What is Type I vs Type II VA cash-out refinancing?
Type I has a new loan amount, including the VA funding fee, that does not exceed the payoff amount of the debt being refinanced. Type II exceeds the payoff and can therefore convert part of the property’s equity into cash proceeds. The distinction matters because certain VA-to-VA Type I transactions have additional rate-reduction and fee-recoupment protections.
Can you refinance a conventional mortgage into a VA loan?
An eligible borrower can potentially refinance a conventional, FHA or other non-VA mortgage into VA-backed financing through the cash-out refinance framework. The borrower still needs the required VA eligibility, owner-occupancy compliance, appraisal and full lender underwriting. Compare the complete new VA mortgage with keeping the existing loan, particularly when the current first-mortgage rate is already unusually favorable.
How long do you have to wait for a VA cash-out refinance?
VA’s federal cash-out seasoning framework applies when an existing VA-guaranteed mortgage is being refinanced into another VA mortgage and includes a 210-day timing requirement together with payment-history conditions. Type I VA-to-VA refinancing specifically requires the applicable first-payment timing and six consecutive monthly payments under the current seasoning rule. A non-VA mortgage does not use the VA-to-VA seasoning rule in the same manner, although an individual lender can impose its own waiting period.
What is the VA cash-out funding fee?
The current standard cash-out refinance funding fee is 2.15% for first use of the VA home loan benefit and 3.3% after first use for borrowers who are not exempt. Certain Veterans, service members and surviving spouses can qualify for a funding-fee exemption under VA rules. The lender should verify benefit-use history and exemption status before the borrower evaluates the final refinancing cost.
Does VA cash-out require an appraisal?
A VA cash-out refinance uses a VA appraisal because reasonable value is central to determining allowable financing and equity withdrawal. A lower-than-expected valuation can therefore reduce the mortgage amount or cash proceeds even when the borrower’s financial qualification remains unchanged. Online property estimates are useful for preliminary planning but should not be treated as committed VA cash-out proceeds.
Can you use a VA cash-out refinance on a paid-off home?
Current VA lender guidance defines cash-out refinancing around an existing mortgage or another indebtedness secured by a recorded lien and states that a property without an existing mortgage or lien of record is not eligible for the standard VA cash-out guarantee. A homeowner with a completely free-and-clear property should therefore have the situation reviewed before assuming that ordinary VA cash-out treatment applies. Another financing structure may be required when there is no qualifying recorded debt to refinance.
Is a VA cash-out refinance better than a HELOC?
Neither option is automatically cheaper because a VA cash-out refinance replaces the entire first mortgage while a HELOC generally preserves the first mortgage and applies a separate rate only to the additional borrowing. Keeping the existing first mortgage can be valuable when its rate is substantially below current refinance pricing, even when the HELOC rate itself is higher. Compare the blended cost of the complete household debt structure, the required payments, fees and rate risk before choosing between them.
Next Steps Before You Apply
Start with the mortgage you already have rather than with the largest cash amount a lender says may be available. Record the current payoff, rate, remaining term and monthly principal-and-interest payment, then decide how much cash actually solves the financial objective. Those figures establish the control scenario against which every VA cash-out offer should be judged.
Next, ask lenders to quote approximately the same cash proceeds and loan term. Request the VA reasonable value assumption, base loan amount, funding fee, total mortgage amount, estimated cash to borrower and amount of equity remaining after closing as separate figures. When those numbers are separated clearly, it becomes much harder for a large cash figure or attractive rate to conceal what happened to the rest of the mortgage.
Then compare the cash-out refinance with the alternative of leaving the first mortgage alone. A second mortgage or HELOC deserves serious attention when the current first-mortgage rate is particularly valuable, while a full refinance becomes more persuasive when the existing mortgage itself also needs improvement. The correct comparison is the cost of financing the household after the transaction rather than the rate attached to only one component.
Finally, avoid treating VA’s maximum program leverage as a personal borrowing target. The strongest transaction can be well below the maximum when it provides enough money for the intended purpose while preserving a meaningful equity cushion and keeping the new mortgage comfortably affordable. When the cash has a defined use, the replacement financing improves the complete debt structure and the household is likely to keep the mortgage long enough to benefit, a VA cash-out refinance can be a powerful use of the VA home loan benefit without turning every available dollar of equity into new long-term debt.