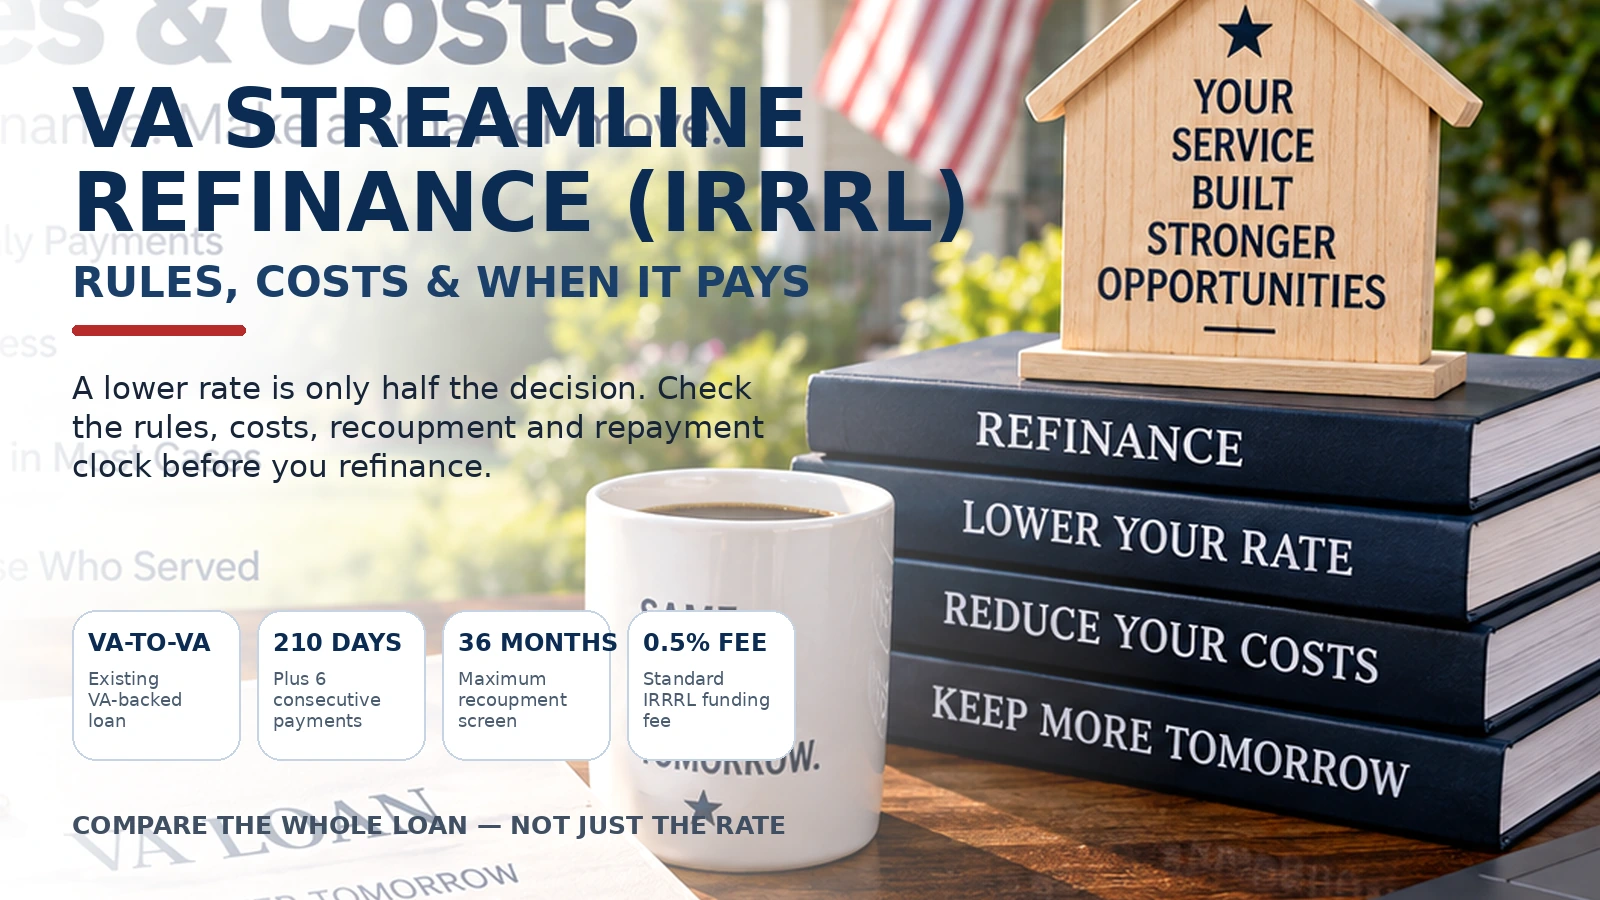
A VA Streamline Refinance, formally called an Interest Rate Reduction Refinance Loan (IRRRL), lets an eligible homeowner replace an existing VA-backed mortgage with another VA-backed loan that offers a lower borrowing cost or a more stable payment. The process can be simpler than a traditional refinance, but “streamline” does not mean every quote is automatically worth accepting.
The decision becomes much clearer when you compare the old rate, new rate, current payment, proposed payment, closing costs, new loan balance and the number of years you expect to keep the replacement mortgage. A lower advertised rate can still be a weak deal if you pay heavy discount points, finance thousands of dollars into the balance or restart the mortgage for much longer than necessary.
VA IRRRL Rules at a Glance
| IRRRL question | General rule | Why it matters |
|---|---|---|
| Existing mortgage | The mortgage being refinanced generally must already be VA backed. | An IRRRL is fundamentally a VA-to-VA refinance. |
| Seasoning | The first payment due date generally must be at least 210 days before the new closing, with six consecutive monthly payments made. | Both timing conditions matter before the refinance can be properly seasoned. |
| Appraisal | A standard IRRRL generally does not require the ordinary VA appraisal used for many other mortgage transactions. | This can reduce cost and remove property-value uncertainty from many transactions. |
| Rate benefit | A fixed-to-fixed IRRRL generally needs at least a 0.50 percentage-point rate reduction. Different standards can apply to other structures. | A small cosmetic rate change should not be enough to justify repeated refinancing. |
| Recoupment | When monthly principal and interest falls, applicable refinance costs generally must be recovered within 36 months under the VA calculation. | A refinance should not require years of savings simply to recover its transaction costs. |
| Cash out | An IRRRL is not the normal VA product for extracting home equity as spendable cash. | Borrowers who need equity proceeds should evaluate a VA cash-out refinance instead. |
What Is a VA IRRRL?
IRRRL stands for Interest Rate Reduction Refinance Loan, although homeowners and lenders commonly call it the VA Streamline Refinance. It replaces an existing VA-backed mortgage with another VA-backed mortgage and is primarily intended to reduce borrowing costs or create a more predictable payment structure. The VA Interest Rate Reduction Refinance Loan guidance explains that borrowers use the program to refinance an existing VA-backed home loan rather than obtain an entirely unrelated mortgage.
When the IRRRL closes, the replacement mortgage pays off the existing VA loan and becomes the new mortgage on the property. Certain closing costs and an applicable VA funding fee may be included in the replacement balance rather than being paid entirely out of pocket. That can reduce cash due at closing, although financing those expenses means the homeowner begins the new mortgage with a larger principal balance.
This distinction matters because “little cash due at closing” is not the same thing as “no cost.” The borrower may still pay the expense over time through a larger balance, a higher interest rate used to generate lender credits, or both. A useful IRRRL comparison therefore needs to show both the new payment and the new principal balance.
Who Can Use a VA Streamline Refinance?
The starting requirement is straightforward: the mortgage being replaced generally must already be VA backed. The IRRRL uses the VA loan already associated with the property rather than functioning as a general refinance program for conventional, FHA or USDA mortgages. Having VA home-loan eligibility by itself does not convert a non-VA mortgage into an IRRRL.
VA also uses a more flexible occupancy standard for this refinance than many borrowers expect. Under current VA IRRRL eligibility guidance, the borrower can generally certify that they currently live in the home or used to live there. That can make a streamline refinance possible even when the property is no longer the borrower’s present primary residence, although the actual transaction still needs to satisfy the lender’s process and the other applicable VA requirements.
Unusual ownership or borrower situations deserve individual review rather than assumptions. Changes in title, surviving-spouse situations, second mortgages and other complications can affect how the lender processes the transaction. If a second mortgage remains on the property, the lienholder may also need to agree to keep the new VA-backed mortgage in first-lien position.
An IRRRL Is Not a VA Cash-Out Refinance
The most important product distinction is what happens to the homeowner’s equity. An IRRRL is meant to improve an existing VA mortgage rather than convert accumulated equity into ordinary cash proceeds. A borrower whose main goal is paying off large debts, funding a renovation or pulling equity for another major expense is usually evaluating a different transaction.
That separate route is the VA cash-out refinance. Cash-out refinancing uses a different underwriting and property-value framework because the borrower may be increasing the mortgage balance to access equity. Mixing the two products can create confusion because the streamlined documentation and appraisal treatment associated with an IRRRL should not automatically be assumed for a cash-out transaction.
An escrow refund or other small amount received because of closing mechanics should also not be confused with cash-out refinancing. The core question is whether the refinance itself is being used to extract home equity. If it is, the borrower should evaluate the cash-out rules rather than trying to fit the transaction into the IRRRL structure.
How Long Do You Have to Wait Before a VA IRRRL?
VA applies a seasoning requirement to prevent extremely rapid repeat refinancing that provides too little benefit to the borrower. Under the standard rule, the due date of the first monthly payment on the mortgage being refinanced generally must be at least 210 days before the IRRRL closing date, and the borrower must also have made six consecutive monthly payments. The VA IRRRL policy guidance on loan seasoning makes clear that both requirements need to be satisfied.
The 210-day rule is commonly misunderstood because the clock is tied to the first payment due date, not simply to the original mortgage closing date. Suppose the purchase mortgage closed in January but the first scheduled payment was due in March. Counting forward from the January closing could make the refinance appear eligible sooner than it really is.
The practical approach is to use the actual mortgage statement and servicing history rather than estimating from the month in which the home was purchased. Your lender should be able to confirm the first payment due date, the payment sequence and the earliest closing date that satisfies the seasoning standard. Reaching six payments alone does not override the 210-day requirement.
The Six Payments Must Be Consecutive
The payment requirement is not simply a lifetime count of six payments made at any point after the mortgage began. VA seasoning guidance specifies six consecutive monthly payments on the mortgage being refinanced. That is why a borrower who has recently experienced delinquency, forbearance or another interruption should have the lender review the actual servicing record before assuming the loan is ready for an IRRRL.
This distinction also helps explain why two borrowers whose VA mortgages originated during the same month may not become eligible on exactly the same date. Their first payment due dates or payment histories can differ. The seasoning test belongs to the actual loan record rather than to a rough calendar estimate.
Even after the mortgage becomes technically seasoned, that does not prove refinancing is financially worthwhile. Seasoning determines when the transaction can be considered under the VA framework, while the rate benefit, refinance costs, recoupment period and term determine whether accepting the new loan makes sense for the household.
Does a VA Streamline Refinance Require an Appraisal?
One of the strongest practical advantages of a VA IRRRL is that the standard streamline transaction generally does not require the ordinary VA appraisal associated with a home purchase or many cash-out refinances. Removing the standard appraisal can reduce both cost and uncertainty, especially when the homeowner is refinancing for rate or payment reasons rather than trying to prove a new amount of available equity.
This can be particularly useful when property values have been flat or the homeowner is unsure what the home would appraise for today. A traditional refinance may depend heavily on current property value, while a standard IRRRL is built around replacing an already VA-backed mortgage. For a broader explanation of this distinction, see when refinancing without an appraisal is possible.
The safest wording is still that an appraisal is generally not required for a standard IRRRL, rather than promising that valuation can never become relevant. Certain loan structures, financed discount-point situations or lender-specific circumstances can create additional requirements. The lender should confirm what the particular transaction needs before the borrower assumes every streamline refinance will follow exactly the same documentation path.
How Much Lower Does the New VA IRRRL Rate Need to Be?
The rate test depends on the type of mortgage being refinanced and the type of mortgage replacing it. For the most common structure—a fixed-rate VA mortgage refinanced into another fixed-rate VA mortgage—the new interest rate generally must be at least 0.50 percentage point lower than the rate on the existing mortgage. VA’s IRRRL net tangible benefit guidance uses this threshold as part of the borrower-benefit standard.
For example, if the current fixed rate is 6.75%, the replacement fixed rate generally needs to be 6.25% or lower to clear that basic fixed-to-fixed test. A quote at 6.50% may still look lower when shown in an advertisement, but it would not satisfy the standard 0.50-point fixed-to-fixed reduction by itself.
The important distinction is that this is a minimum program screen, not a recommendation that every 0.50-point reduction is worth accepting. A borrower could technically meet the rate threshold and still receive a weak deal after discount points, lender fees, financed costs and a longer repayment term are included.
Fixed Rate to Adjustable Rate Has a Different Test
A fixed-rate VA mortgage refinanced into an adjustable-rate mortgage generally faces a much larger initial rate-reduction requirement. Under the VA framework, the initial rate on the new ARM generally needs to be at least 2.00 percentage points lower than the fixed rate being replaced. That higher threshold reflects the additional uncertainty the borrower accepts when moving from a stable fixed payment into an adjustable structure.
A homeowner with a 6.75% fixed mortgage, for example, would generally need an initial ARM rate of 4.75% or lower to satisfy that fixed-to-ARM rate test. The low introductory rate still should not be viewed in isolation because the future ARM adjustment structure can matter considerably after the initial period ends.
Discount points also deserve extra attention in a fixed-to-ARM IRRRL. VA guidance places specific limits around financed discount points and loan-to-value when points are responsible for producing the lower rate. In some of those cases, a property valuation may be needed to establish LTV even though a standard fixed-to-fixed IRRRL normally avoids the ordinary appraisal process.
What If You Are Refinancing an ARM Into a Fixed Rate?
An ARM-to-fixed refinance can produce a meaningful benefit even when the new fixed rate is not lower than the ARM’s current temporary rate. The advantage may be payment stability rather than an immediate rate reduction. That distinction matters because an adjustable loan can change over time while the fixed replacement provides a known rate for the remaining term.
This is one reason the phrase net tangible benefit is more useful than simply asking whether the rate goes down. VA refinance rules are intended to identify a real financial benefit to the borrower, but the form of that benefit can differ by loan structure. A fixed-to-fixed borrower usually expects a measurable rate reduction, while an ARM borrower may value certainty and protection from future adjustments.
The lender should be able to explain exactly what benefit supports the transaction. If the explanation is vague or consists only of “you can refinance now,” ask for the old and new loan side by side with the rate, principal-and-interest payment, term, costs and new principal balance shown clearly.
The 36-Month VA IRRRL Recoupment Rule
Rate reduction is only one part of the consumer-protection framework. VA also applies a recoupment standard to refinance costs. When an IRRRL lowers the borrower’s monthly principal-and-interest payment, the fees, closing costs and expenses included in the official calculation generally must be recovered through the monthly principal-and-interest savings within 36 months.
The basic calculation is straightforward:
Suppose the refinance creates $3,600 of costs that count toward the VA recoupment calculation and lowers monthly principal and interest by $150. Dividing $3,600 by $150 gives a recoupment period of 24 months. That is inside the 36-month screen.
If the same transaction produced only $75 of monthly savings, the recoupment period would be 48 months. That would exceed the standard 36-month limit and would require the lender to address the problem rather than simply presenting the lower rate as sufficient evidence that the refinance is beneficial.
Not Every Closing Cost Is Included in the VA Recoupment Calculation
The official VA recoupment calculation does not simply add every dollar shown at closing. VA guidance excludes certain categories from the statutory calculation, including the VA funding fee, escrow amounts and prepaid expenses such as insurance and taxes. That means the official 36-month number can differ from the homeowner’s broader personal break-even calculation.
This difference is important because borrowers often ask, “When will I actually recover everything this refinance costs me?” That household question can be broader than the federal recoupment test. If you paid prepaid interest, funded an escrow account or financed the VA funding fee, those dollars can still matter to your overall financial comparison even when they are treated differently under the VA recoupment formula.
The safest approach is to look at both numbers. First, ask the lender for the official VA recoupment calculation. Then make a second personal comparison that includes the costs and principal changes that matter to your own budget and expected holding period.
What Happens If the New Principal-and-Interest Payment Is the Same or Higher?
This is one of the most useful IRRRL rules to understand because it prevents a lender from solving an unattractive payment result simply by pointing to some other benefit. Under VA recoupment guidance, when the replacement IRRRL produces the same or a higher monthly principal-and-interest payment, the borrower generally cannot incur the ordinary fees, closing costs and expenses that would otherwise need to be recouped. Certain excluded categories, such as the VA funding fee, taxes and escrow-related amounts, are treated separately.
That creates a much stricter cost screen than many borrowers expect. If a quote raises principal and interest while also showing thousands of dollars in ordinary lender and refinance charges, the transaction deserves immediate scrutiny. The lender should be able to explain how the quote complies with the applicable IRRRL rules before the borrower focuses on any marketing claim about future flexibility or convenience.
An ARM-to-fixed transaction can still create a legitimate benefit through payment stability, but that does not remove the need to understand the cost structure. Stability can be valuable. Paying large ordinary refinance fees for a same-or-higher payment is a different question.
VA IRRRL Funding Fee
For borrowers who are not exempt, the standard VA funding fee for an IRRRL is currently 0.5% of the loan amount. The VA funding fee and closing-cost guidance lists IRRRLs separately from VA cash-out refinancing, which carries a different funding-fee structure.
On a $300,000 IRRRL, a 0.5% funding fee would equal $1,500. A borrower may be able to pay that amount at closing or finance it into the replacement mortgage. Financing reduces the immediate cash requirement, but it also means paying interest on the funding fee as part of the new principal balance.
| Example IRRRL amount | 0.5% funding fee | What to remember |
|---|---|---|
| $200,000 | $1,000 | Financing it increases the replacement balance. |
| $300,000 | $1,500 | The fee is excluded from the statutory recoupment calculation. |
| $400,000 | $2,000 | Funding-fee exemption can materially change the quote. |
Who May Be Exempt From the VA Funding Fee?
Some Veterans, service members and surviving spouses qualify for an exemption from the VA funding fee. VA identifies several qualifying situations, including certain borrowers receiving or eligible to receive compensation for a service-connected disability and certain surviving spouses receiving Dependency and Indemnity Compensation. Other qualifying categories can also apply.
Do not assume the funding fee is correct simply because it appears on the first worksheet you receive. If you believe you qualify for an exemption, ask the lender to verify your status before you compare the final loan amount. An unnecessary funding fee can change the new balance, monthly payment and long-term interest calculation.
Funding-fee status is particularly important when comparing lenders because one lender may initially produce a worksheet using the standard 0.5% fee while another has already verified the exemption. Those two documents are not yet comparable until the underlying assumptions match.
What Other Closing Costs Can an IRRRL Include?
A streamline refinance can still carry ordinary mortgage transaction expenses even when no appraisal is required. Depending on the lender and state, the quote may contain lender or origination charges, title or settlement costs, recording charges, credit-related fees, discount points and other permitted closing expenses. Prepaid interest and escrow funding may also affect the amount due at closing even though they are not treated the same way as ordinary refinance costs in the VA recoupment calculation.
The key is to separate these charges instead of looking only at the total cash-to-close figure. One lender may offer a lower rate with expensive discount points. Another may charge fewer upfront fees but offer a slightly higher rate. A third may provide lender credits that reduce cash due today while increasing the interest rate you pay over time.
This is why the Consumer Financial Protection Bureau’s explanation of points and lender credits is useful when shopping IRRRL quotes. Points generally trade more upfront cost for a lower interest rate, while lender credits generally reduce upfront cost in exchange for a higher rate.
Discount Points Can Make a Low Rate Look Better Than It Really Is
A discount point normally equals 1% of the loan amount. On a $300,000 mortgage, one point equals $3,000. If one lender advertises 5.50% with two points while another offers 5.75% with no points, the 5.50% quote is not automatically cheaper. The borrower is effectively paying $6,000 upfront for the lower rate before considering any other lender charges.
The correct question is how long the monthly savings created by those points take to recover their additional cost. If paying $6,000 reduces the monthly payment by only $70, the point-specific break-even period is more than seven years. A borrower who expects to move or refinance again in four years may receive little practical benefit from paying that much for the lower headline rate.
When comparing lenders, ask each one to provide a quote with the same number of points. A zero-point comparison is especially useful because it exposes the lender’s pricing without allowing one offer to appear artificially attractive because the borrower is paying more upfront to buy down the rate.
Lender Credits Work in the Opposite Direction
Lender credits reduce the amount the borrower needs to pay toward closing costs, but they are usually connected to accepting a higher interest rate. This structure can make sense when the borrower expects to keep the replacement mortgage for a relatively short period or wants to minimize cash due at closing. It can be less attractive when the borrower expects to keep the loan for many years and will therefore pay the higher rate for a long time.
A “no-closing-cost IRRRL” should therefore be examined carefully. The costs do not necessarily disappear. The lender may be paying some of them through pricing built into a higher interest rate, or the costs may be financed into the new balance. Our guide to no-closing-cost refinancing explains why reducing upfront cash and reducing total borrowing cost are two different goals.
The most useful lender comparison is not “Which quote has the smallest cash-to-close number?” It is “Which quote gives me the best combination of rate, APR, points, lender fees, payment and cost over the period I realistically expect to keep the loan?”
Why the New Loan Balance Matters
One of the easiest ways for a refinance to appear more attractive than it really is is to hide financed costs inside the replacement principal. The homeowner sees a lower payment, but the new mortgage balance quietly increases because lender charges, permitted closing costs and the funding fee are being added to the amount owed.
Imagine a borrower with a $285,000 balance who finances approximately $2,600 of ordinary refinance costs plus an estimated $1,425 funding fee. The replacement note could begin around $289,025 before any other permitted adjustments. A lower rate may still make that transaction worthwhile, but the comparison should use the actual new note amount rather than pretending the borrower is refinancing only $285,000.
This is why the Loan Estimate matters so much. The borrower needs to know not only what the new monthly payment will be but also how much debt will exist immediately after closing.
A Lower Payment Can Still Hide a Longer Repayment Clock
A monthly payment reduction does not always mean the borrower has reduced the overall cost of the mortgage. If the existing mortgage has 18, 22 or 27 years remaining and the IRRRL resets the loan to a new 30-year term, part of the payment reduction may come from stretching repayment across additional years rather than from the interest-rate reduction alone.
Consider an illustrative borrower with a $285,000 balance, 27 years remaining and a 6.875% rate. The remaining principal-and-interest payment is roughly $1,937 per month. If that borrower refinances approximately $289,025 into a new 30-year mortgage at 6.375%, the principal-and-interest payment falls to about $1,803 per month.
The monthly reduction looks attractive at roughly $134. However, the new scheduled repayment period is three years longer. If both loans were held for their full remaining terms, the total scheduled principal-and-interest payments on the replacement loan could actually exceed the remaining scheduled payments on the existing mortgage. The refinance may still make sense for other reasons, but the payment alone does not tell the whole story.
Compare the Clock, Not Just the Payment
Before accepting a refinance because the payment falls, ask the lender to show the new loan using more than one term if those options are available. A borrower with 22 years left, for example, may want to compare a new 20-year or 25-year structure with a fresh 30-year loan rather than assuming the longest available term is automatically best.
A shorter replacement term can produce a higher monthly payment than a 30-year refinance while still reducing the total amount of interest paid over time. That trade-off can be worthwhile for a household whose priority is becoming mortgage-free sooner rather than maximizing immediate monthly cash flow.
The best term is therefore not universal. It depends on how much payment relief the household needs today, how long the borrower expects to own the property and how important faster principal reduction is relative to monthly flexibility.
When a VA IRRRL Usually Makes Sense
A VA Streamline Refinance tends to be strongest when several favorable conditions appear together rather than when only one number improves. The new mortgage should provide a real benefit, the transaction costs should be modest relative to that benefit, and the borrower should expect to keep the replacement loan long enough for the refinance to produce value. A clear rate reduction combined with manageable fees and little unnecessary term extension is generally much more compelling than a low-rate offer supported by expensive points.
The transaction can also make sense when the borrower’s priority is payment stability. Someone moving from an adjustable-rate VA mortgage into a fixed-rate mortgage may value certainty even when the immediate payment reduction is modest. In that case, the benefit should still be described specifically in terms of the payment structure, cost of the refinance and length of time the borrower expects to keep the loan.
A good refinance solves a meaningful mortgage problem. It may reduce monthly principal and interest, eliminate uncertainty from an adjustable rate, lower the effective cost of borrowing or create enough monthly flexibility to justify the transaction. The stronger the benefit and the shorter the cost-recovery period, the easier the decision becomes.
When a VA IRRRL May Not Be Worth It
An IRRRL becomes much less attractive when the refinance costs consume most of the expected savings. A borrower who saves $80 per month but incurs several thousand dollars in qualifying costs may technically receive a lower payment while gaining very little practical benefit for years. If the borrower expects to sell, pay off the mortgage or refinance again before reaching break-even, the transaction may never have enough time to repay its own cost.
The case also weakens when the new mortgage balance rises substantially because fees and the funding fee are being financed. That increase can be easy to overlook because financed costs do not require the borrower to write a large check at closing. The debt is still real, and the borrower pays interest on the additional principal for as long as it remains outstanding.
Another warning sign is a payment reduction created mainly by restarting a partly paid-down mortgage at 30 years. The monthly payment may fall even when the new rate advantage is modest because the debt is being spread across more months. Payment relief can still be useful, but the borrower should recognize that the lower payment and lower total borrowing cost are not automatically the same result.
A Short Break-Even Period Is Usually Better
Break-even tells you how long the refinance needs before the accumulated monthly savings recover the meaningful transaction costs. A 12-month break-even gives the borrower much more room to benefit than a 34-month break-even, particularly when the future ownership period is uncertain. The closer break-even gets to the time you expect to sell or refinance again, the less margin you have for the transaction to create real value.
For example, a homeowner expecting to keep the mortgage for eight more years may be comfortable with a 24-month break-even because approximately six years remain after the initial recovery period. A homeowner expecting to move in two and a half years would have a very different decision. The same refinance can therefore be sensible for one borrower and weak for another even when the rate and lender fees are identical.
This is why break-even should be paired with a realistic holding period rather than treated as a standalone score. Nobody knows the future perfectly, but a reasonable estimate is far more useful than assuming every refinance will be held for 30 years. If you already expect a move, retirement, downsizing or another major mortgage change, include that possibility in the calculation.
The Four Numbers I Would Compare First
If a lender gives you a long page of refinance figures, begin with four numbers before you evaluate anything else. The first is the monthly principal-and-interest change, because that tells you the immediate payment effect. The second is the relevant refinance cost, because monthly savings are not true net savings until the transaction has recovered what it cost to create them.
The third number is the new mortgage balance. This exposes financed costs that can otherwise disappear inside a lower monthly payment. The fourth number is the number of months you realistically expect to keep the replacement mortgage, because the holding period determines whether the savings have enough time to exceed the transaction cost.
| Number to compare | What it tells you | What can go wrong |
|---|---|---|
| Monthly P&I change | Shows the immediate monthly cash-flow difference. | A lower payment may partly come from extending the term. |
| Relevant refinance costs | Helps estimate how long savings need to recover the transaction expense. | Points and lender charges can make a low rate expensive. |
| New loan balance | Shows how much debt you actually owe immediately after refinancing. | Financed costs can quietly increase principal. |
| Expected holding period | Shows how much time you have to benefit after break-even. | Selling or refinancing too soon can eliminate much of the expected benefit. |
Once those four numbers look reasonable, move into the deeper comparison. Review APR, rate-lock period, discount points, lender credits, future principal balances and the amount of scheduled interest under the two mortgage paths. The first screen tells you whether the offer deserves more attention, while the second tells you how good the offer really is.
Rate and APR Answer Different Questions
The mortgage interest rate primarily tells you how interest accrues on the outstanding principal. APR attempts to reflect the interest rate together with certain loan charges, which can make it useful when comparing similarly structured mortgage offers. The Consumer Financial Protection Bureau’s explanation of rate versus APR is useful because the two percentages should not be treated as interchangeable.
A lender can advertise a very attractive interest rate while charging enough points or other finance charges to produce a noticeably higher APR. That does not automatically make the offer bad, but it tells you that obtaining the lower rate carries a meaningful cost. The longer you expect to keep the mortgage, the more time a paid-down rate has to produce savings; the shorter the holding period, the more carefully you should examine large upfront charges.
APR is also not a complete lifetime-cost calculator. It relies on assumptions and does not replace a comparison of actual cash due, financed costs, monthly payment and your expected holding period. Use it as another comparison signal rather than as the sole answer.
How to Compare VA IRRRL Lenders Properly
VA-backed does not mean every lender offers the same rate, points or fees. IRRRLs are made through private banks, mortgage companies and credit unions, and VA itself encourages borrowers to compare lenders because terms and fees can vary. Shopping is therefore part of the refinance decision rather than an optional extra step.
The comparison only works when the quotes are built on similar assumptions. Ask each lender to quote the same approximate loan amount, same mortgage term, same rate-lock period and same number of discount points. If Lender A shows 5.75% with two points while Lender B shows 6.00% with zero points, you are not yet comparing equivalent pricing.
I would ask for a zero-point version from each lender whenever practical. You can then compare the lenders’ underlying pricing before deciding whether paying points makes sense. After that, ask for any alternative structure you are seriously considering, such as a lender-credit option or a shorter term.
What to Compare on the Loan Estimate
Once you receive formal Loan Estimates, put them next to each other rather than reading each one independently. Compare the interest rate, APR, discount points, origination charges, lender credits, estimated cash to close and projected principal-and-interest payment. The CFPB’s Loan Estimate comparison guidance provides a useful framework for making those documents easier to evaluate.
Pay particular attention to charges that differ from one lender to another. Some third-party items may be similar regardless of lender, while origination charges, points and lender credits can reveal meaningful differences in pricing. When one lender appears dramatically cheaper, verify that the rate-lock period and loan structure are actually equivalent before assuming you found the winner.
Also compare the lender’s estimate of the final loan amount. Two offers can produce similar monthly payments while financing very different amounts of closing costs into the mortgage. A lower starting principal is valuable because it reduces the amount on which future interest is charged.
Do You Need Perfect Credit for a VA IRRRL?
The VA streamline structure does not create one universal minimum credit score that every IRRRL borrower must meet. Lenders can still use their own underwriting standards or overlays, so one company may be comfortable with a borrower profile that another will not accept. This is another reason a denial or unattractive quote from one lender does not necessarily describe the entire IRRRL market.
Credit can also influence pricing even when the basic VA framework does not prescribe a single score cutoff. A stronger borrower profile may make it easier to obtain favorable pricing or satisfy a particular lender’s requirements. Avoid any article or advertisement that promises every borrower the same result solely because the mortgage is VA backed.
The practical question is not whether you have a mythical “VA IRRRL credit score.” Ask each lender whether it applies a minimum score, debt-to-income standard, payment-history requirement or other overlay beyond the basic VA program rules. That gives you a real comparison rather than relying on a generic number from a marketing page.
Use Streamline Savings Compass Before You Accept a Quote
The calculator below is designed to bring the important IRRRL questions into one place. Enter your current balance, rate and remaining term, then add the proposed refinance rate, points, lender charges and other applicable costs. The experience estimates the new principal-and-interest payment, funding-fee exposure, recoupment period, new loan balance and the effect of your expected holding period.
It also checks the major seasoning and rate-benefit screens based on the information you enter. A result marked for review does not mean a refinance is automatically prohibited, because the exact transaction still depends on the loan structure and lender documentation. It does tell you which question needs a clearer answer before you move forward.
The local comparison section does not invent lenders or ratings. Enter your city, ZIP code, neighborhood or area to open ordinary Google Search and Google Maps results, then paste the real lenders you find into the comparison area. This gives you a structured way to compare rate, APR, points, fees, VA specialization, licensing checks and other practical differences.
Streamline Savings Compass
See whether a VA IRRRL appears to improve your mortgage after you compare rate, payment, points, lender fees, 36-month recoupment and the amount added to the new loan.
Current VA loan
Begin with the mortgage you already have.
Proposed IRRRL quote
Enter the new lender quote and how the costs are being handled.
Rules, timing and your holding period
Screen the main federal issues before you judge the quote.
Find and compare nearby VA refinance lenders
Search ordinary Google results, then paste the lenders you want to compare.
- Use the same loan amount, term and lock period with each lender.
- Ask each lender for a zero-point version of the quote.
- Confirm whether they actively handle VA IRRRL loans.
Compare three to five nearby lenders
Questions to Ask Before You Lock an IRRRL Rate
A rate lock turns the refinance from a general shopping exercise into a much more specific transaction, so this is the point where vague answers should disappear. Ask the lender to show exactly which rate, points, credits, costs and lock period you are accepting. If the lender cannot explain how those items connect to the new payment and loan balance, keep asking questions before you commit.
- Can you show me the same quote with zero discount points? This makes it much easier to see whether the lower rate is being purchased through a large upfront charge.
- What is the official VA recoupment period? Ask the lender to identify which costs are included and which are excluded from the calculation.
- How much will my mortgage balance increase at closing? Separate ordinary financed costs from the VA funding fee.
- What is the exact rate-lock period? Ask whether an extension costs money if the loan fails to close before the lock expires.
- What is the net tangible benefit for this transaction? The lender should be able to explain the answer in plain language rather than relying on a generic refinance claim.
- Is the lower payment partly caused by extending my term? Ask for the remaining repayment period on the current loan beside the term on the replacement loan.
- Are you applying any lender requirements beyond the VA minimums? Credit-score, debt-to-income and documentation overlays can differ between lenders.
What Documents Should You Keep From the Refinance?
Keep the Loan Estimates from the lenders you seriously considered, even if you ultimately reject some of them. Those documents make it easier to remember which lender offered which rate, points and fee structure once multiple phone calls begin to blur together. The comparison also gives you evidence if the pricing changes materially later in the process.
For the lender you choose, retain the final Closing Disclosure, your rate-lock confirmation and any document showing the lender’s IRRRL recoupment or benefit calculation. If the funding fee is waived because you qualify for an exemption, keep the documentation supporting that treatment as well. Mortgage records are much easier to review later when the important assumptions are preserved together.
After closing, compare the first new mortgage statement with the final loan documents. Confirm the principal balance, interest rate and principal-and-interest payment match what you expected. A streamline process should reduce complexity, not reduce the borrower’s responsibility to verify what actually closed.
Professional Perspective: The Best IRRRL Is the One That Improves the Mortgage, Not the Advertisement
The most common refinance mistake is evaluating the new loan in isolation. A borrower sees 5.875%, a lower monthly payment and a phrase such as “streamlined closing,” then decides whether the offer looks attractive. The better method is comparative: what exactly do you have today, what exactly will replace it, what does the transition cost and how long will you live with the result?
A half-point rate reduction can be meaningful on a large balance, but it is not automatically enough to justify expensive points or another 30-year repayment clock. A slightly smaller rate reduction with low fees can sometimes create a stronger household result. An ARM-to-fixed refinance can also be valuable because of stability even when the immediate savings are not dramatic.
The program rules create useful protections, but they cannot make the personal decision for you. Your expected holding period, need for monthly payment relief, tolerance for financed costs and preference for faster mortgage payoff still matter. The best refinance is the one whose benefit remains visible after those trade-offs are placed on the same page.
Key Takeaways
- An IRRRL is a VA-to-VA refinance. The mortgage being replaced generally needs to be VA backed.
- Seasoning has two parts. The first payment due date generally must be at least 210 days before closing, and six consecutive monthly payments generally must have been made.
- A standard IRRRL usually avoids the ordinary appraisal process. Special structures can still create valuation requirements.
- Fixed-to-fixed refinancing generally requires at least a 0.50 percentage-point rate reduction.
- Fixed-to-ARM refinancing generally requires a larger initial rate reduction.
- The 36-month recoupment test matters. A lower rate is not enough when the qualifying costs take too long to recover.
- The standard IRRRL funding fee is 0.5% for a non-exempt borrower.
- Financed costs are still costs. Watch the new mortgage balance rather than judging only cash due at closing.
- Compare the repayment clock. A lower payment may partly result from restarting the loan at a longer term.
- Shop multiple lenders on equivalent assumptions. Compare rate, APR, points, fees, credits, lock period and new loan amount.
A Simple Decision Framework Before You Refinance
By the time you reach the final decision, you should be able to explain the proposed IRRRL without relying on the lender’s sales language. You should know what is changing, what the change costs, how quickly those costs are recovered, how much debt you will owe after closing and whether the new repayment schedule fits the way you expect to use the property.
A useful decision sequence is to check eligibility first, then the financial benefit, then the cost structure and finally the holding period. This order prevents an attractive advertised rate from dominating the decision before the more important questions have been answered.
| Decision stage | Question to answer | What a strong answer looks like |
|---|---|---|
| 1. Eligibility | Is the current mortgage VA backed, properly seasoned and otherwise suitable for an IRRRL? | The lender can clearly document the existing VA loan, payment history and applicable seasoning dates. |
| 2. Benefit | What exactly improves after refinancing? | The rate falls enough to satisfy the applicable rule, the payment improves, or the loan becomes materially more stable. |
| 3. Cost | What am I paying in points, lender charges, other costs and financed principal? | The costs are transparent, reasonable and do not require an excessively long recovery period. |
| 4. Recoupment | How quickly do monthly P&I savings recover the applicable refinance costs? | The official IRRRL calculation satisfies the applicable VA requirement, and your personal break-even also fits your plans. |
| 5. Repayment clock | Am I extending the mortgage substantially? | Any term extension is intentional and justified by the payment relief or other benefit you are receiving. |
| 6. Holding period | Will I probably keep the replacement mortgage long enough for it to pay off? | Your expected ownership or refinance horizon leaves meaningful time after break-even. |
If several of those answers are unclear, the correct next step is usually more comparison rather than a faster closing. IRRRLs can be efficient transactions, which makes it especially important that speed does not replace scrutiny.
Frequently Asked Questions About VA IRRRLs
What does IRRRL stand for?
IRRRL stands for Interest Rate Reduction Refinance Loan. It is commonly called the VA Streamline Refinance and is designed to replace an existing VA-backed mortgage with another VA-backed mortgage that provides an eligible borrower benefit, such as a lower borrowing cost or a more stable payment structure.
Do I need to have a VA loan already to use an IRRRL?
Yes. An IRRRL is generally a VA-to-VA refinance, so the mortgage being replaced needs to be an existing VA-backed home loan. If your current mortgage is conventional, FHA, USDA or another non-VA loan, an IRRRL is not the normal refinance route.
How long do I have to wait before getting a VA IRRRL?
The mortgage generally must satisfy both seasoning conditions before the refinance closes: the due date of the first monthly payment on the existing loan must be at least 210 days before the new closing date, and six consecutive monthly payments must have been made on the mortgage being refinanced.
Does a VA IRRRL require an appraisal?
A standard VA IRRRL generally does not require the ordinary VA appraisal used for many purchase and cash-out transactions. Certain refinance structures involving valuation or financed discount points can create additional requirements, so the lender should confirm what applies to the specific loan.
Does a VA IRRRL require a credit check?
The streamline framework can involve less underwriting than many traditional refinances, but borrowers should not assume that every lender uses identical credit procedures. Private lenders can apply their own requirements and overlays, so ask the lender whether it requires a credit report, minimum score or additional underwriting for the quote being offered.
How much lower must my rate be for a VA IRRRL?
For a fixed-rate VA mortgage refinanced into another fixed-rate mortgage, the new rate generally must be at least 0.50 percentage point lower than the existing rate. A fixed-to-adjustable IRRRL generally requires an initial rate reduction of at least 2.00 percentage points. Other structures can have different tangible-benefit considerations.
What is the VA IRRRL 36-month recoupment rule?
When an IRRRL lowers monthly principal and interest, the qualifying fees, closing costs and expenses used in the VA calculation generally must be recovered through the monthly principal-and-interest savings within 36 months. Certain items, including the VA funding fee, escrow amounts and qualifying prepaid expenses, are excluded from that statutory calculation.
What if my new IRRRL payment is the same or higher?
When the replacement IRRRL produces the same or a higher monthly principal-and-interest payment, VA recoupment guidance generally does not allow the borrower to incur ordinary fees, closing costs or expenses that would otherwise need to be recouped, apart from specifically excluded items. A lender offering this structure should be able to explain both the borrower benefit and the cost treatment clearly.
What is the VA funding fee for an IRRRL?
The standard VA funding fee for an IRRRL is 0.5% for borrowers who are not exempt. The fee can generally be paid at closing or financed into the replacement mortgage. Some eligible Veterans, service members and surviving spouses are exempt from paying the funding fee.
Can I roll VA IRRRL closing costs into the loan?
Certain permitted closing costs and the VA funding fee can generally be included in the new IRRRL balance. Financing costs can reduce the amount of cash needed at closing, but it also increases the principal balance and can increase the amount of interest paid over time.
Can I get cash out with a VA IRRRL?
An IRRRL is not the standard VA cash-out product and is not intended for extracting home equity as ordinary spendable cash. Borrowers who want to access equity should evaluate a VA cash-out refinance instead and compare its different appraisal, underwriting and cost requirements.
Can I refinance a second mortgage with an IRRRL?
An IRRRL is used to refinance the existing VA-backed first mortgage rather than to cash out or pay off unrelated junior debt. If a second mortgage remains on the property, the holder may need to agree to subordinate its lien so the replacement VA-backed mortgage remains in first position.
Should I pay discount points on a VA IRRRL?
Paying discount points can make sense when the lower rate produces enough monthly savings and you expect to keep the mortgage long enough to recover the added upfront cost. Ask for a zero-point version of the quote first so you can calculate how long the points themselves take to break even.
Is a no-closing-cost VA IRRRL really free?
Usually no. A lender may cover eligible closing costs through lender credits tied to a higher interest rate, or permitted costs may be financed into the new mortgage balance. The borrower should compare the interest rate, new principal balance and long-term cost instead of treating low cash due at closing as proof that the refinance has no cost.
Can I use an IRRRL if I no longer live in the property?
VA IRRRL eligibility generally allows the borrower to certify that they currently live in or used to live in the property securing the loan. This makes the occupancy standard more flexible than many purchase-loan situations, although the lender still needs to verify that the specific transaction satisfies all applicable requirements.
Can a VA IRRRL restart my mortgage at 30 years?
A replacement IRRRL can use a new mortgage term permitted by the transaction, which means a borrower with fewer than 30 years remaining could end up extending the repayment period. The lower monthly payment should therefore be compared with the remaining term on the current loan and the scheduled cost of the replacement mortgage.
How many lenders should I compare for an IRRRL?
There is no required number, but comparing at least three reasonably equivalent offers can make lender pricing differences easier to see. Request quotes within a tight time window and keep the loan amount, term, points and rate-lock period as similar as possible so the comparison is meaningful.
Is the lowest VA IRRRL rate always the best offer?
No. A very low rate may require expensive discount points or come with a less attractive fee structure. Compare the interest rate with APR, points, lender charges, lender credits, monthly savings, recoupment period, new principal balance and expected holding period before deciding which quote provides the strongest overall value.
The Bottom Line
A VA Streamline Refinance can be one of the more efficient ways to improve an existing VA-backed mortgage, particularly when the borrower can lower the rate or replace an adjustable payment with a stable fixed structure without taking on excessive transaction costs. The lighter appraisal and documentation framework can make the process easier, but convenience should never replace a proper comparison.
Start with the current mortgage rather than with a lender advertisement. Confirm the loan is eligible and seasoned, identify the benefit the new loan is supposed to provide, calculate how quickly the relevant costs are recovered and inspect the new principal balance. Then compare the remaining term on the current loan with the repayment period you are about to accept.
If the result is a meaningful rate or stability improvement, reasonable costs, a manageable new balance and enough time after break-even to benefit, an IRRRL can be a strong refinance option. If the deal only looks attractive because the lender highlights the payment while hiding expensive points, financed costs or a much longer repayment clock, keep shopping.
For borrowers focused specifically on finding the strongest pricing after understanding these rules, continue with our guide to how to get the best VA Streamline Refinance rate. If your real objective is accessing home equity rather than simply improving an existing VA mortgage, compare the separate 30-year VA cash-out refinance decision before choosing a loan structure.