Insurance transfers part of a financial loss to an insurer under a contract. The benefit might pay a hospital, replace earnings, repair a building, defend a claim or provide income for life. To understand what you are buying, finish this sentence in plain English: “If this happens, this coverage pays this person for this loss.” If you can fill in only the first blank, you still have a question for the insurer.
Consider a baker who breaks a wrist. The urgent care center wants payment for treatment. The baker still needs money for groceries during recovery. Customers who prepaid for cakes want to know whether their orders will arrive. All three concerns grew out of one accident. A health plan can address the medical bill while leaving the household budget and the bakery’s obligations largely untouched.
This U.S. guide explains 19 insurance benefits people encounter at home, at work and on the road. Some come bundled in one policy. Others require a separate contract or an endorsement, which changes an existing policy. The numbers help you find a benefit again. They carry no implication that a household needs 19 policies.
When someone dies, gets sick or needs help at home
1. Life insurance gives survivors time to adjust
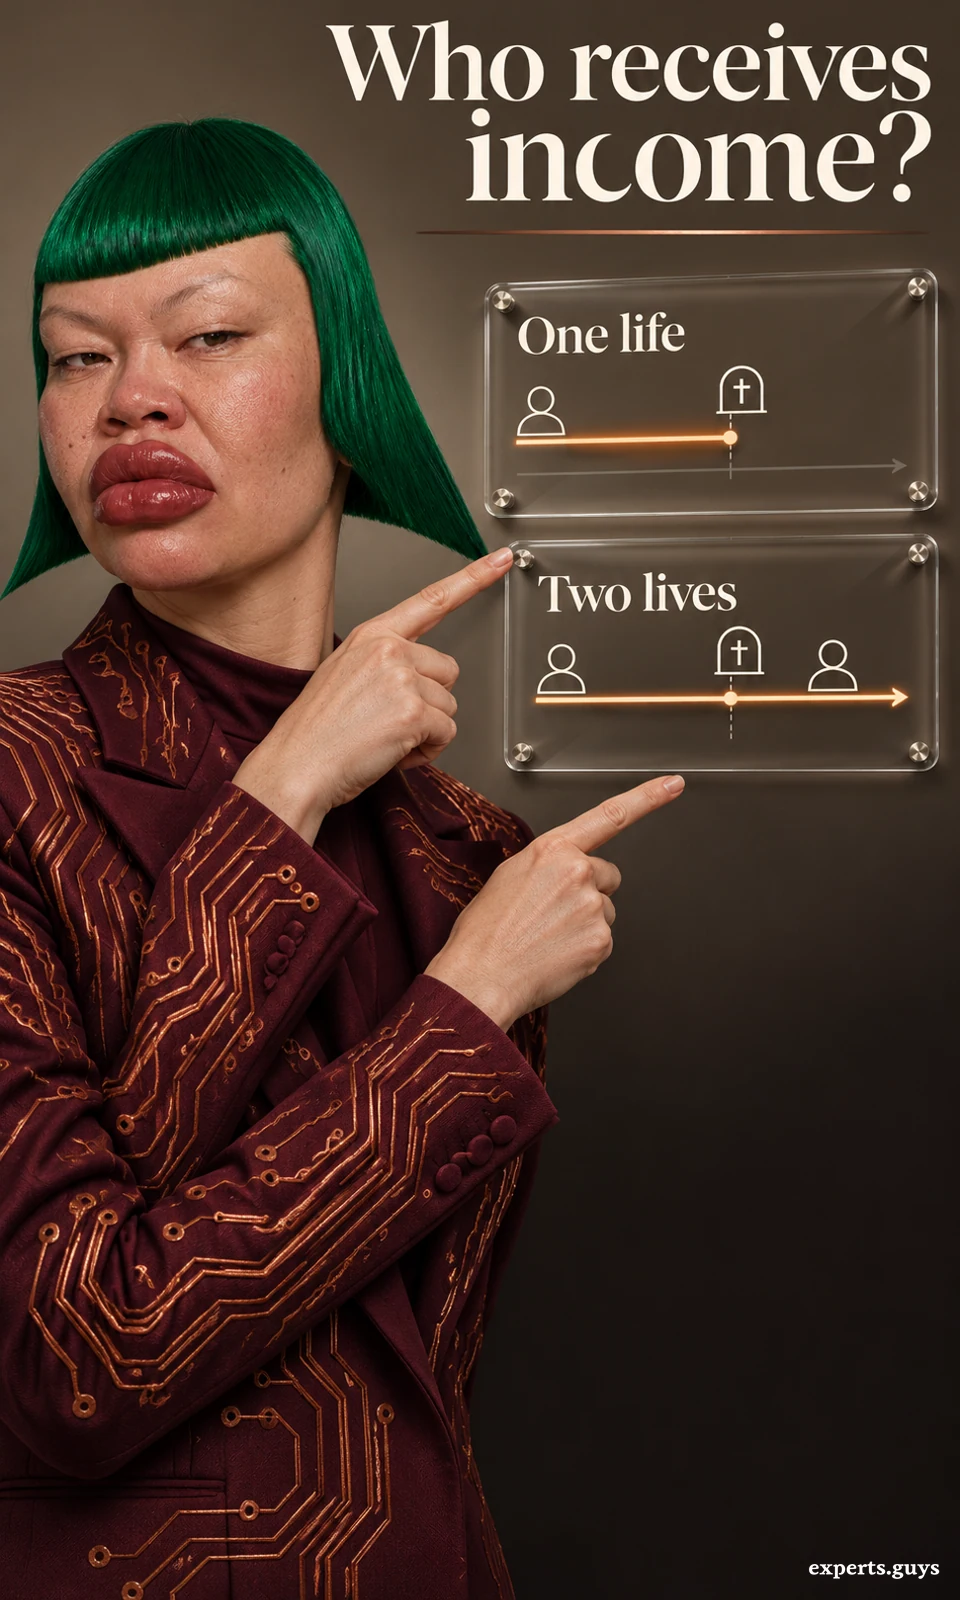
A death benefit can give a beneficiary money to keep a household running after the insured person dies while coverage is in force. Picture two parents who work opposite shifts so one is always home with their child. Losing the lower earner could mean paying for childcare, reducing the survivor’s hours or moving nearer a relative. Salary alone misses the service the family would have to replace. Think in terms of the choices the survivor would still have while rearranging that care.
Term coverage lasts for a stated period. Some permanent policies also accumulate cash value. A loan against that value is a different transaction from receiving an accelerated death benefit. An acceleration provision requires a qualifying event under the policy, and taking money early generally reduces what remains for beneficiaries. For a family counting on the entire face amount, the revealing number is the death benefit remaining after the proposed withdrawal, loan or acceleration. The NAIC consumer guide to life insurance explains the main policy structures.
2. Disability income insurance helps replace earnings
An editor who can read manuscripts after an injury but cannot type for more than a few minutes has two separate questions. Can she do the duties that earn her living? How does her policy define disability? A medical diagnosis helps explain the impairment. Eligibility also depends on the contract’s occupational definition, how much she can work and whether it provides a partial disability benefit. An ability to resume two mornings a week can have a different financial result from a return to full-time work.
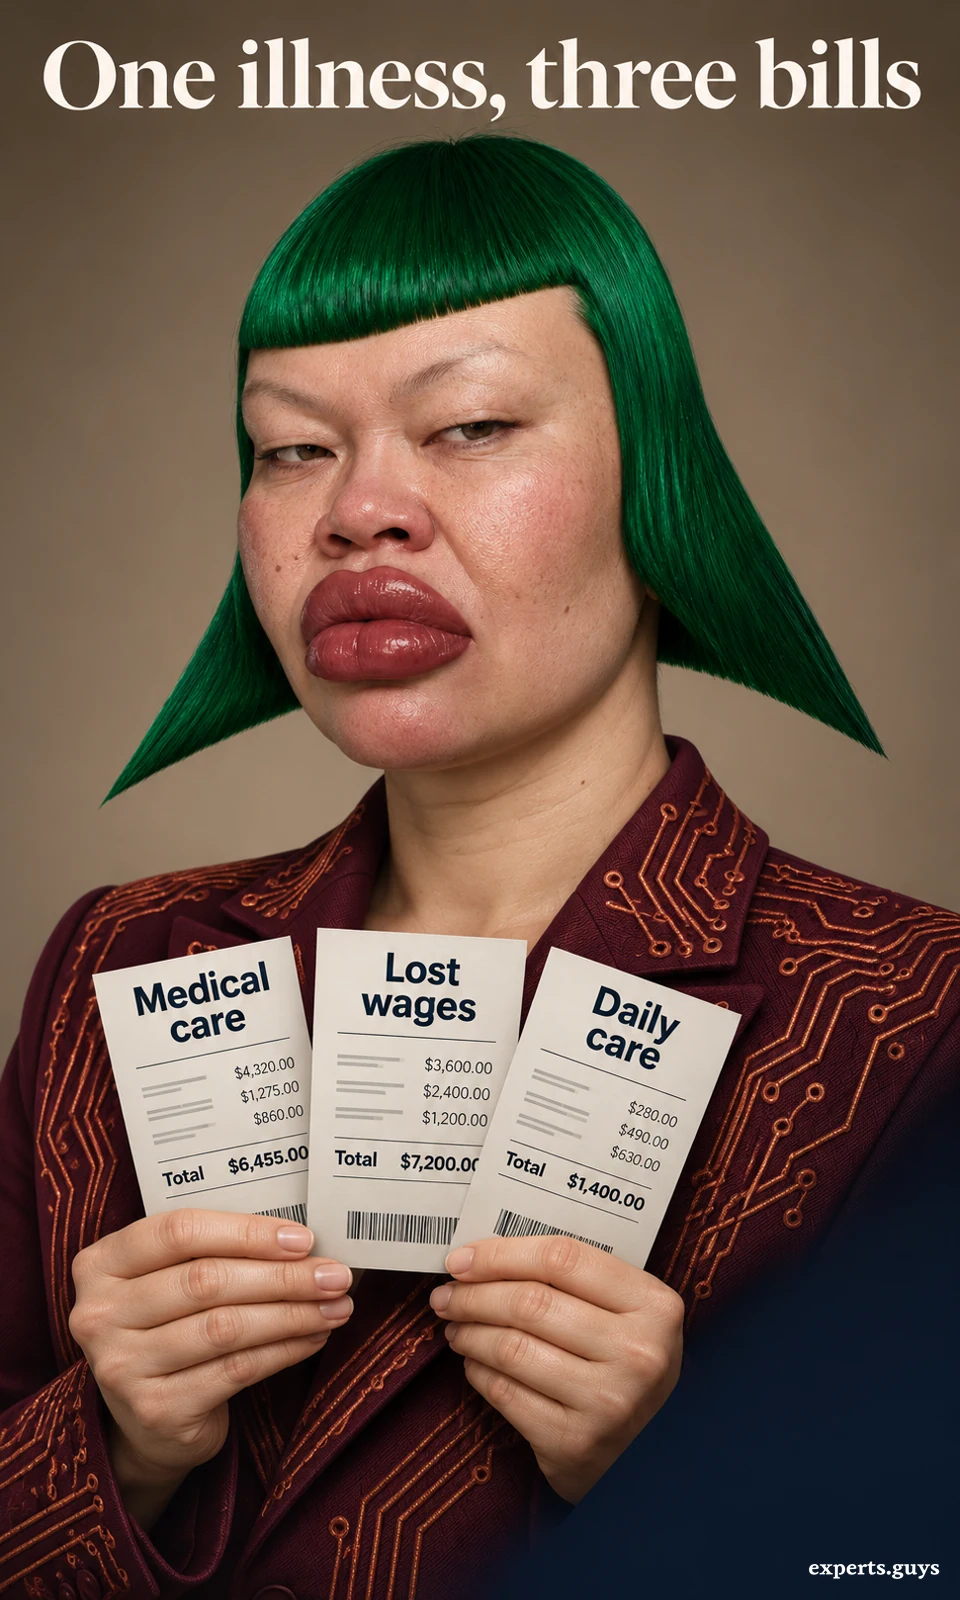
Timing matters even when eligibility looks clear. Imagine a policy with a 60-day elimination period and an employer that offers two weeks of paid leave. The family has several weeks to finance before a disability benefit could begin. A benefit described as a percentage of earnings may also have a monthly cap. Someone who earns a large commission each December would want to know which earnings period the insurer uses. A percentage on a brochure answers neither the timing question nor the commission question.
3. Health insurance shares eligible medical costs
For a covered appointment, the amount billed, the plan’s allowed amount and the patient’s share can be three different figures. A plan may apply a copayment, a deductible or coinsurance depending on the service. For example, 20 percent coinsurance on a hypothetical $500 allowed amount after the deductible is met gives a $100 patient share, assuming no other adjustment. Using the provider’s initial charge in that calculation could produce a very different expectation.
The out-of-pocket maximum has a particular job. It limits what you pay during the plan year for covered in-network care under the relevant rules. Premiums and uncovered services sit outside it. A household with a regular specialist appointment therefore needs the provider network and service terms as well as the headline maximum. U.S. Marketplace plans cover pre-existing conditions, yet the plan’s network and formulary can still affect where treatment is available and what a prescription costs. See HealthCare.gov’s explanation of the out-of-pocket limit and its Marketplace premium rules.
4. Long-term care insurance can pay for day-to-day assistance
A parent may be medically stable enough to live at home and still need another person there every morning. Bathing, dressing and transferring safely from bed to a chair take time. Long-term care coverage addresses qualifying care needs, subject to its benefit triggers, covered settings and available benefits. A diagnosis by itself does not tell the family whether the insurer will recognize that morning visit, a particular care provider or a residential placement.
| What changed? | Benefit to examine | Deciding detail |
|---|---|---|
| Provider treats illness | Health | Network, allowed charge and cost sharing |
| Illness reduces work hours | Disability income | Occupational definition and partial benefits |
| Daily activities require assistance | Long-term care | Care setting, trigger and waiting period |
Imagine two otherwise similar policies. One reimburses eligible documented expenses up to a daily limit. Under that design, buying a larger daily limit does little for a family relying entirely on an unpaid relative unless the contract also recognizes that arrangement. The other policy has different payment terms. The meaningful comparison is how each handles the care this household expects to use. The NAIC long-term care guide discusses home care, facilities, waiting periods and benefit limits.
5. An annuity can turn savings into a retirement income stream
An annuity is an insurance contract that can turn money paid to an insurer into a stream of payments. A lifetime income option addresses the possibility of living longer than a pot of savings lasts. That serves a different need from reimbursing the cost of an accident. A retiree whose pension already covers housing but leaves a monthly gap for food and utilities may find the payment schedule more informative than an advertised accumulation rate.
The payee and duration change the value of the promise. An income quote for one life and another that continues while either spouse lives describe different household budgets after the first death. Likewise, a period-certain option can change what is payable if someone dies early. Access to the original money may become restricted when payments begin. Ask for quotes with the same start date and survivor terms before comparing the monthly figures. The NAIC overview of annuity contracts distinguishes immediate and deferred arrangements.
When a home or its contents are damaged
6. Homeowners insurance can fund repairs and displacement
The place you own has a sale price, a mortgage balance and a cost to rebuild. A house on a valuable plot can sell for much more than the cost of replacing its walls and roof. A modest house with hard-to-source materials can surprise in the opposite direction. Dwelling coverage concerns the insured structure under the policy’s valuation terms. The amount still owed to the bank answers a different question. Lender acceptance of a policy tells you relatively little about what rebuilding would look like.
A covered fire can also make the house unusable before repairs begin. If additional living expense coverage applies, the household may recover qualifying increases above normal spending, within applicable limits. Suppose your normal food spending is $180 for a week and temporary arrangements increase it to $260. The extra $80 illustrates the kind of difference that matters. It is not a promise of reimbursement. Duration, documentation and the cause of displacement all affect the result. The NAIC homeowners coverage overview distinguishes dwelling, possessions and loss of use.
7. Renters insurance protects a tenant’s financial interests
After a kitchen fire, a landlord may arrange repairs to cabinets and wiring. The tenant still needs a bed, clothing and somewhere to stay. Renters coverage can address personal belongings, eligible additional living costs and liability, depending on the contract. The renter who hears “the building is insured” has learned something about the landlord’s property. Ownership of the damaged belongings is the missing fact.
- For the building, identify the dwelling limit and settlement terms.
- For a temporary move, identify qualifying extra expenses and the time limit.
- For belongings, establish ownership and any category limits.
Consider a shared apartment. One roommate owns the dining table, another brought an expensive camera, and both use a borrowed television. A single address tells you little about who qualifies as an insured or how the policy treats property belonging to others. The declarations and definitions identify covered people, while limits for categories of belongings can affect a high-value item. A reader considering specialist cover for an unusual possession can explore examples of unusual things people insure after identifying where the ordinary policy stops.
8. Flood insurance addresses a particular source of water
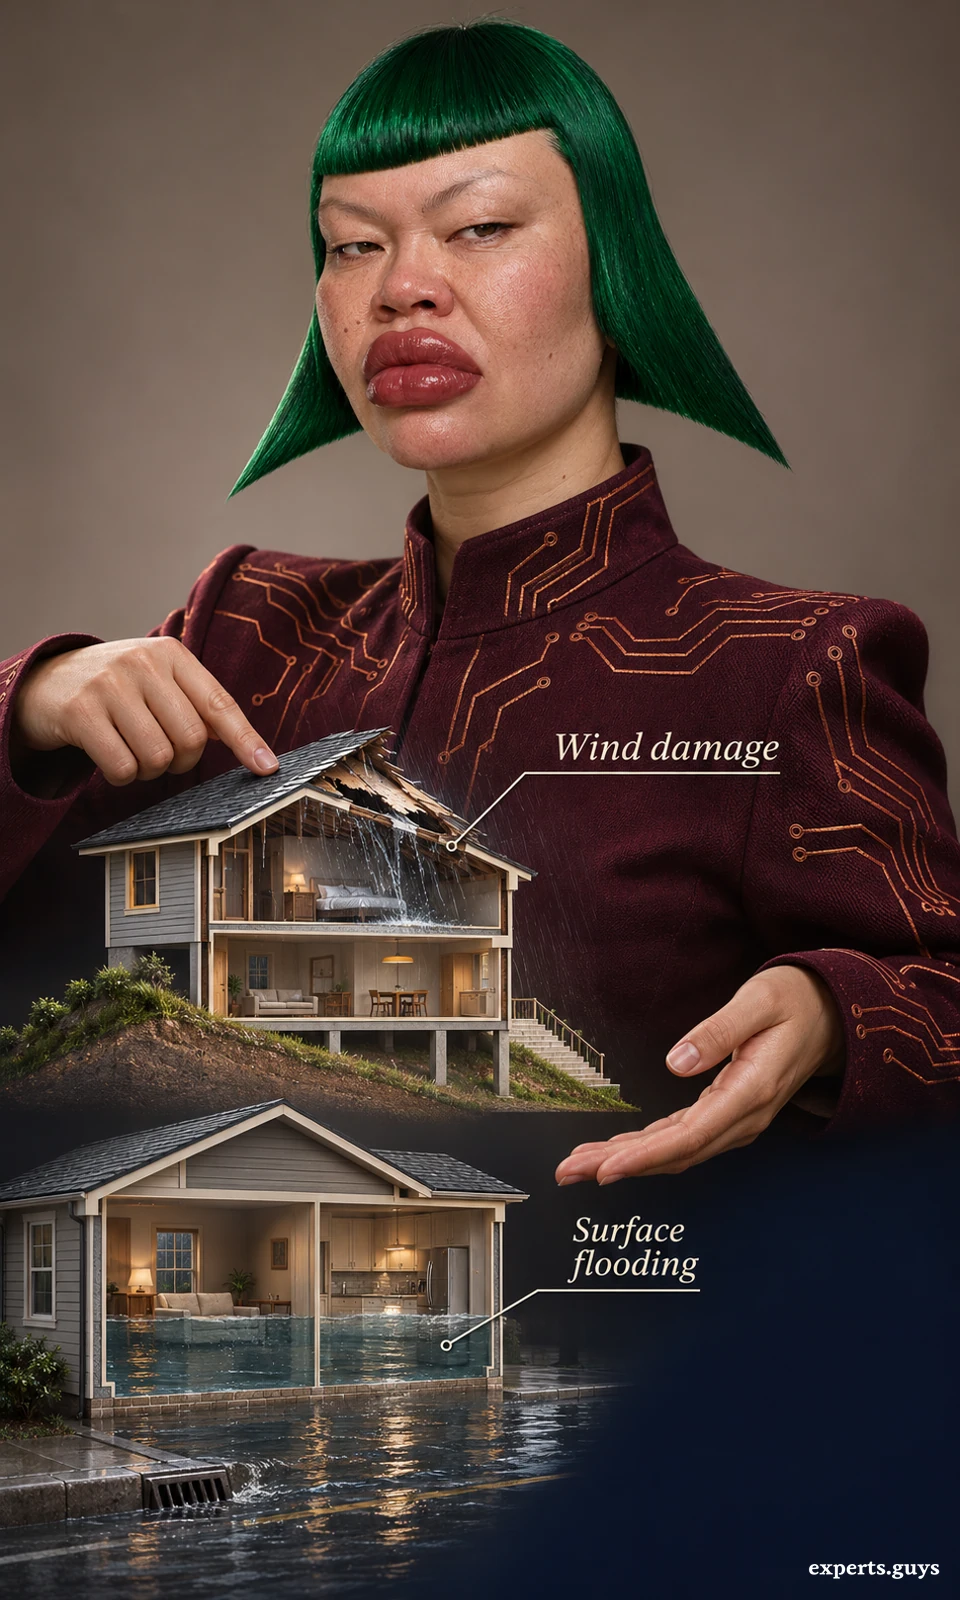
A storm can send rain through a wind-damaged roof and surface water through the front door on the same evening. “The house got wet” leaves out the fact that separates two coverage questions. Standard homeowners policies generally exclude flood. A flood contract uses its own definition of flooding and specifies building and contents protection. Water backing up through a drain introduces yet another issue. A neighbor’s successful claim for storm damage tells you little without knowing how the water entered.
In the National Flood Insurance Program, building and contents coverage are distinct. A homeowner with building-only coverage may have an insured furnace and an uninsured sofa in the same room, subject to the details of location and property classification. A renter may be primarily interested in contents. Temporary housing expenses also need separate attention because standard NFIP coverage excludes additional living expenses. FEMA’s building and contents coverage guide explains the distinctions and lists common exclusions.
9. Earthquake insurance can cover shaking damage
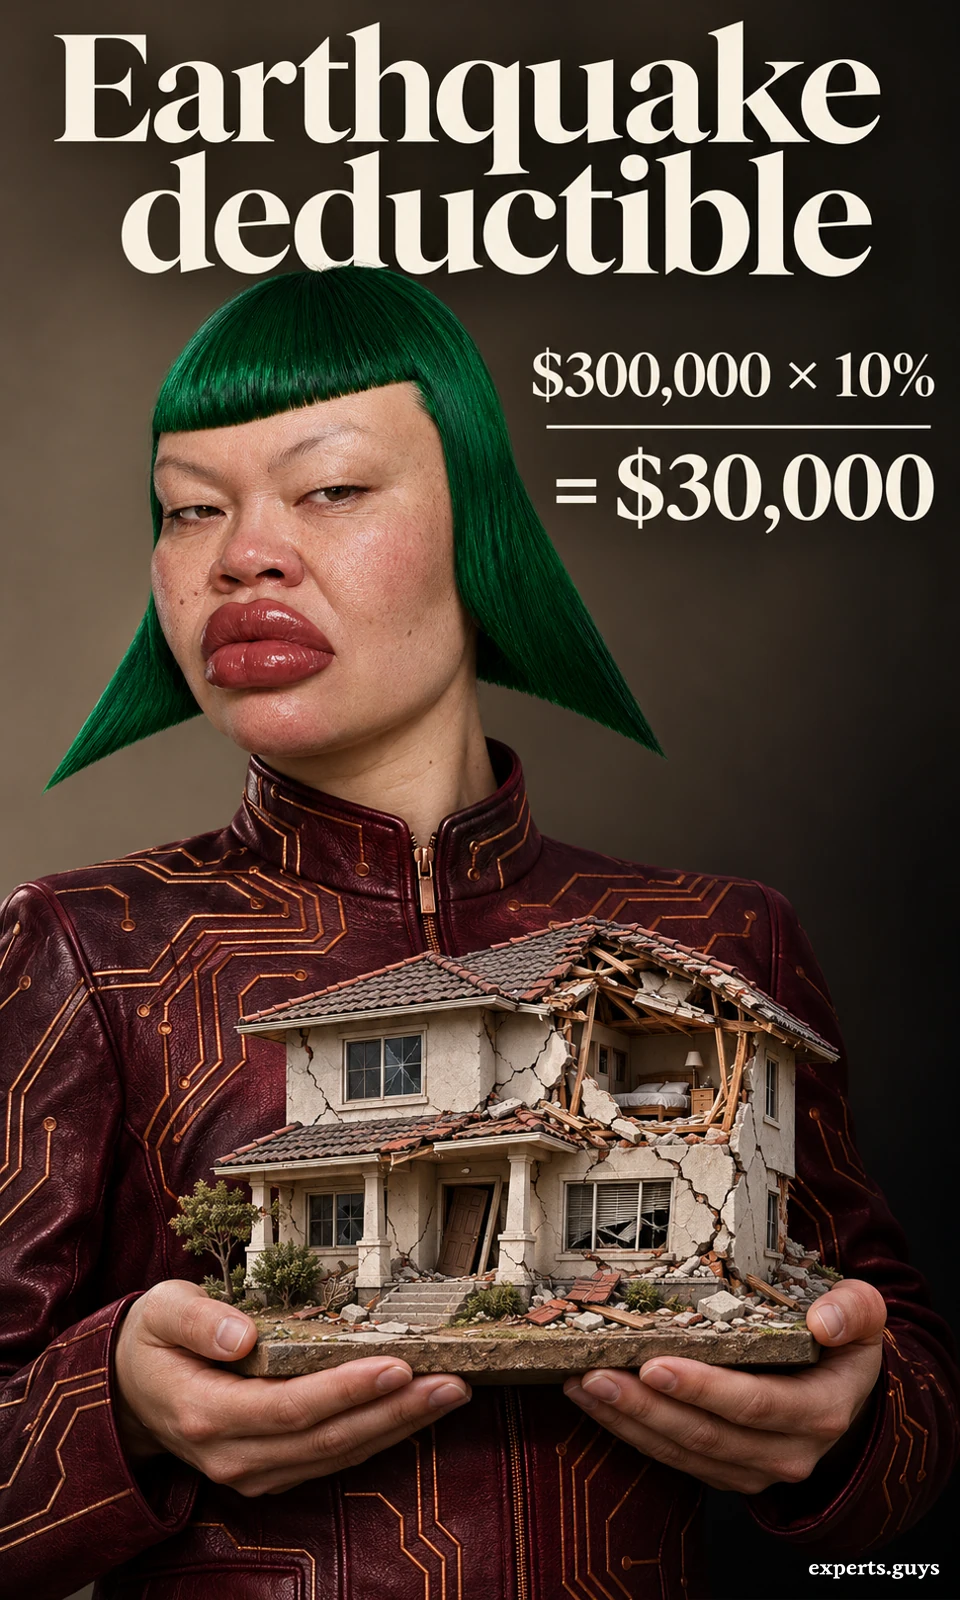
A house can look relatively intact above ground while movement has damaged the foundation. Standard homeowners contracts generally exclude earthquake damage. A separate policy or endorsement may cover qualifying damage, subject to its own deductibles and limits. For an owner with limited cash available for repairs, the deductible calculation can change the entire meaning of a quote. Read the base to which a percentage applies as carefully as the percentage itself.
Suppose a sample earthquake contract applies a 10 percent deductible to a $300,000 dwelling limit. That produces a $30,000 deductible for that part of the contract. It does not become $3,000 simply because the repair estimate is $30,000. Other property or loss-of-use terms may operate differently. Two neighbors can therefore have similar repair bills and very different amounts available to rebuild. The example shows why a buyer may value a policy as protection against severe structural loss while expecting to finance smaller repairs independently.
10. Wind coverage can respond to tornado damage
A tornado is a peril, or cause of loss. A homeowner may already have wind coverage in a broader policy, while another property may need separate wind protection or face a special deductible. A search for “tornado insurance” can miss the answer hiding in the windstorm endorsement. The NAIC guide to named perils and wind coverage explains why coastal homes in particular can have different arrangements.
Think about a storm that damages shingles, topples a fence and knocks out power for three days. Each consequence still needs a matching provision. The fence may fall under other structures. Spoiled food or a hotel stay during a utility outage presents a different question from the cost of replacing shingles. Calling everything “tornado damage” can hide an exclusion or a smaller limit. A precise inquiry describes the damaged object, how it was damaged and whether the home itself became uninhabitable.
11. Fire coverage can pay for property lost to a covered fire
A fire is another peril commonly included in broader property coverage. The presence of the word “fire” on two documents does not establish that you have twice the protection. One might insure a structure while another covers a tenant’s equipment inside it. A policy limited to specified perils can also differ materially from a broader homeowners form. The property description and valuation language tell you what the fire benefit could actually restore.
Imagine a hobbyist who keeps a kiln in a detached workshop. The shed, the kiln, items made for sale and a customer’s ceramic pieces are four different interests. If the hobby becomes a business, an insurer may treat some of those items differently even though the equipment stays exactly where it was. That change in use is worth discussing before relying on a household property limit. It also explains why a fire policy that satisfied a property owner may leave a tenant with a costly inventory problem.
When a vehicle, vessel or liability claim is involved
12. Auto insurance separates your car from harm to others
Back into a neighbor’s gate and you have two property losses. Damage to the gate may fall under property damage liability if you are legally responsible. Damage to your bumper raises a collision coverage question. A liability limit large enough to replace the entire gate does nothing by itself to fix your bumper. A separate issue arises if passengers or pedestrians suffer injuries. Even on the same declarations page, these coverages have different jobs.
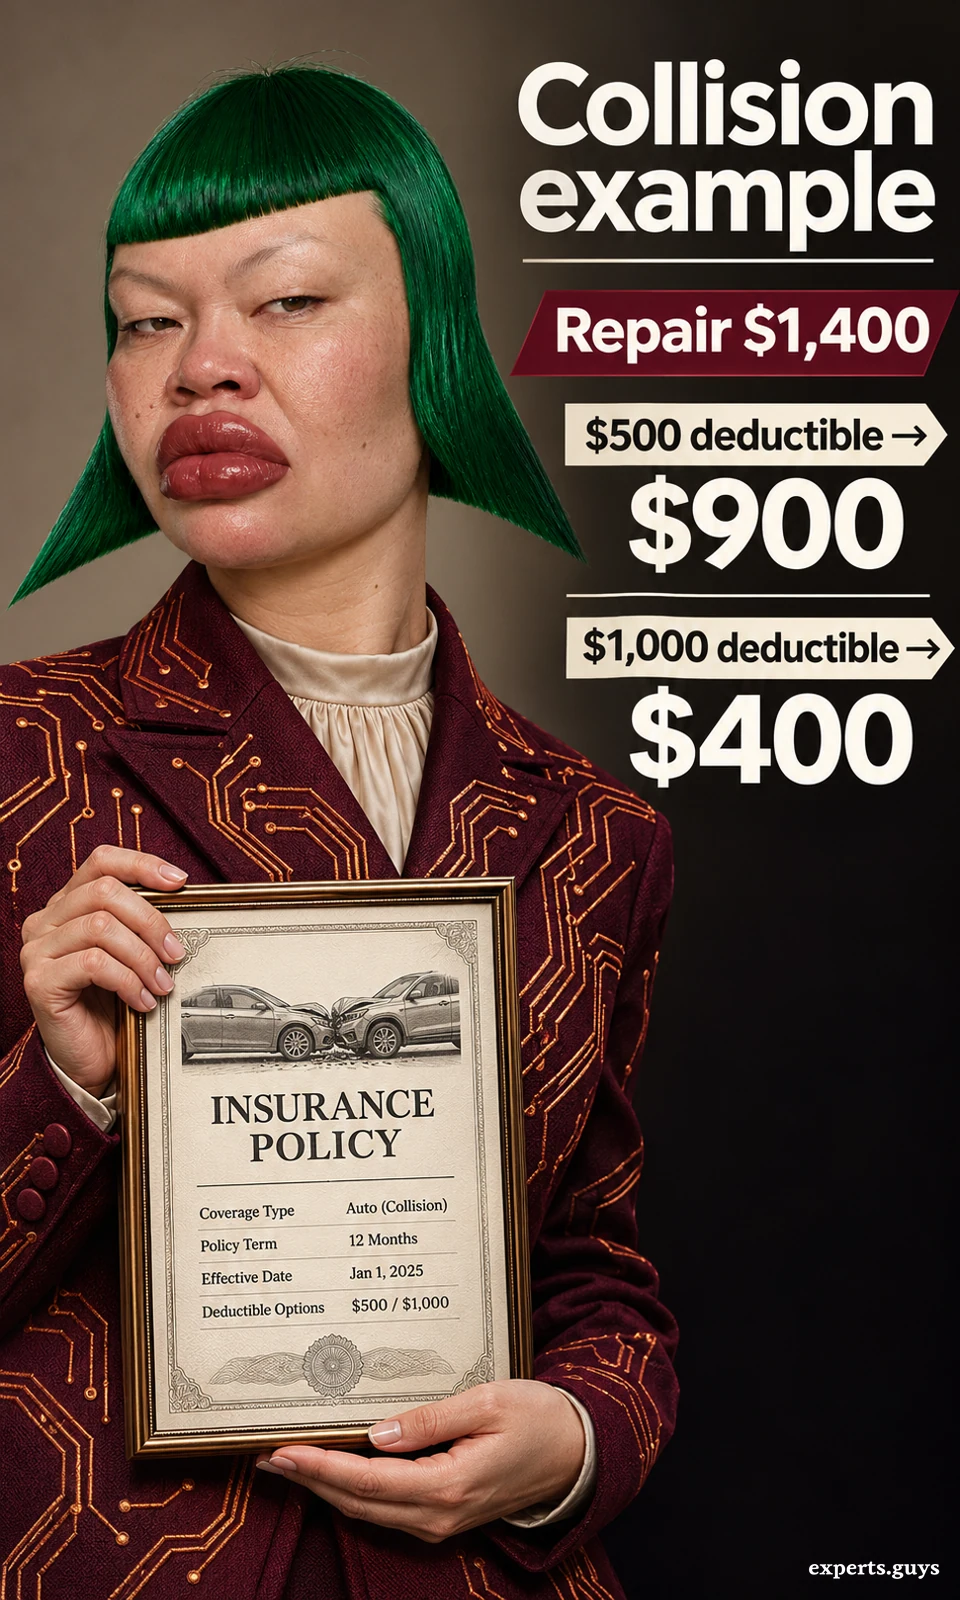
Compare two hypothetical collision options on an older car. With a covered $1,400 repair and a $500 deductible, a simple estimate gives a $900 insurer share. With a $1,000 deductible it gives $400, assuming identical terms and no valuation dispute. The difference in this claim is $500. Whether the premium savings matter enough depends on the household’s ability to cover that larger immediate expense. For flood, hail or theft of the vehicle, the relevant line is generally comprehensive. The NAIC guide to auto coverages describes the distinction.
13. Motorcycle insurance can protect a rider’s bike and liability
For a rider who has replaced the seat, added panniers and installed custom equipment, “the motorcycle” has a different meaning from the standard machine in a valuation guide. Physical damage coverage and the amount allocated to accessories deserve separate attention. Someone who cares most about a custom build may discover that the most important difference between quotes appears in a small equipment provision rather than in the headline liability limit.
A passenger adds another person whose injuries may have to be addressed. The applicable coverage depends on the circumstances, the policy and state law. A rider taking occasional weekend trips with a passenger has a concrete question to take to the insurer: which provision would address the passenger’s injury if the rider were responsible? That question can uncover a coverage difference that a comparison based on engine size, model year and annual premium would overlook completely.
14. Boat insurance can cover a vessel and boating liability
A boat spends time in several places: on a trailer, tied to a dock, on open water or in winter storage. The same physical object can encounter different coverage boundaries at each stage. A hull provision addresses damage to the insured vessel under its terms. Liability addresses qualifying harm to others. A buyer who only compares insured values may overlook the permitted navigation territory, use or storage conditions.
Picture borrowing a friend’s trailer for a trip to another body of water. A road accident could damage the trailer, the boat and someone else’s vehicle. An answer about towing liability alone leaves the first two items unresolved. Before a trip, give the insurer the departure point, destination, vessel and trailer ownership and intended use. Those details give the insurer something concrete to confirm. For an owner whose boat usually stays at the same marina, a change of location may matter more than the length of the trip.
15. Personal umbrella insurance extends qualifying liability protection
A serious injury claim can exceed the liability available on a home or auto policy. An umbrella can provide an additional layer for eligible claims and may include certain defense costs under its terms. It usually comes with requirements for underlying insurance. A family that changes its auto liability limit at renewal should check how that change interacts with the umbrella. A mismatch could leave a portion of a loss payable by the household.
Here is a simplified illustration. A covered liability loss totals $450,000. The applicable primary policy pays $300,000. The remaining $150,000 is the amount to examine under the umbrella, subject to coverage, attachment and available limits. If instead the family suffers $150,000 of hail damage to its own home, the existence of an umbrella does not turn that property loss into a liability claim. The NAIC umbrella insurance guide explains this boundary and common exclusions.
When a business has damaged stock, lost time or an injured person
16. Commercial property insurance helps replace business assets
A bakery leases a storefront but owns ovens, display cases and ingredients. The lease may split responsibility for the walls, glass, improvements and installed equipment between tenant and landlord. An owner who assumes the landlord’s building insurance will restore the entire working bakery could reopen to an empty shell. Commercial property coverage can protect the business’s insured equipment, inventory and other covered property at specified locations.
Seasonal stock makes the choice of limit especially important. A shop with $18,000 of goods most months may hold substantially more just before the holidays. A fixed limit that feels comfortable during a quiet month can leave a shortfall after a fire during the busiest week. Goods held for customers, goods in transit and equipment used off premises introduce different questions again. The useful comparison is the property at the location on the day of the loss, including who owns it and how the policy values it.
17. Business interruption insurance can support a covered shutdown
After a covered fire, a replacement oven may arrive long before a bakery can open its doors. Rent could continue while repairs are underway. Some expenses, such as ingredients for cakes the shop will never sell, might stop. Business income coverage commonly addresses lost net income and qualifying continuing expenses during a defined restoration period after a covered disruption. Treating every dollar of missed sales as a dollar of insured loss overstates what the policy is designed to pay.
Consider a bakery that expected $12,000 of sales over a short closure and would have spent $4,000 on ingredients and packaging for those sales. That leaves $8,000 before examining other saved expenses, continuing costs, the applicable waiting period and the policy’s calculation. Adding rent again without understanding how the calculation handled it could count the same expense twice. A closure caused only by weak demand raises a different issue because the usual property-damage trigger may be absent. The Insurance Information Institute’s business interruption guide explains restoration periods and extra expenses.
18. Workers’ compensation addresses qualifying work injuries
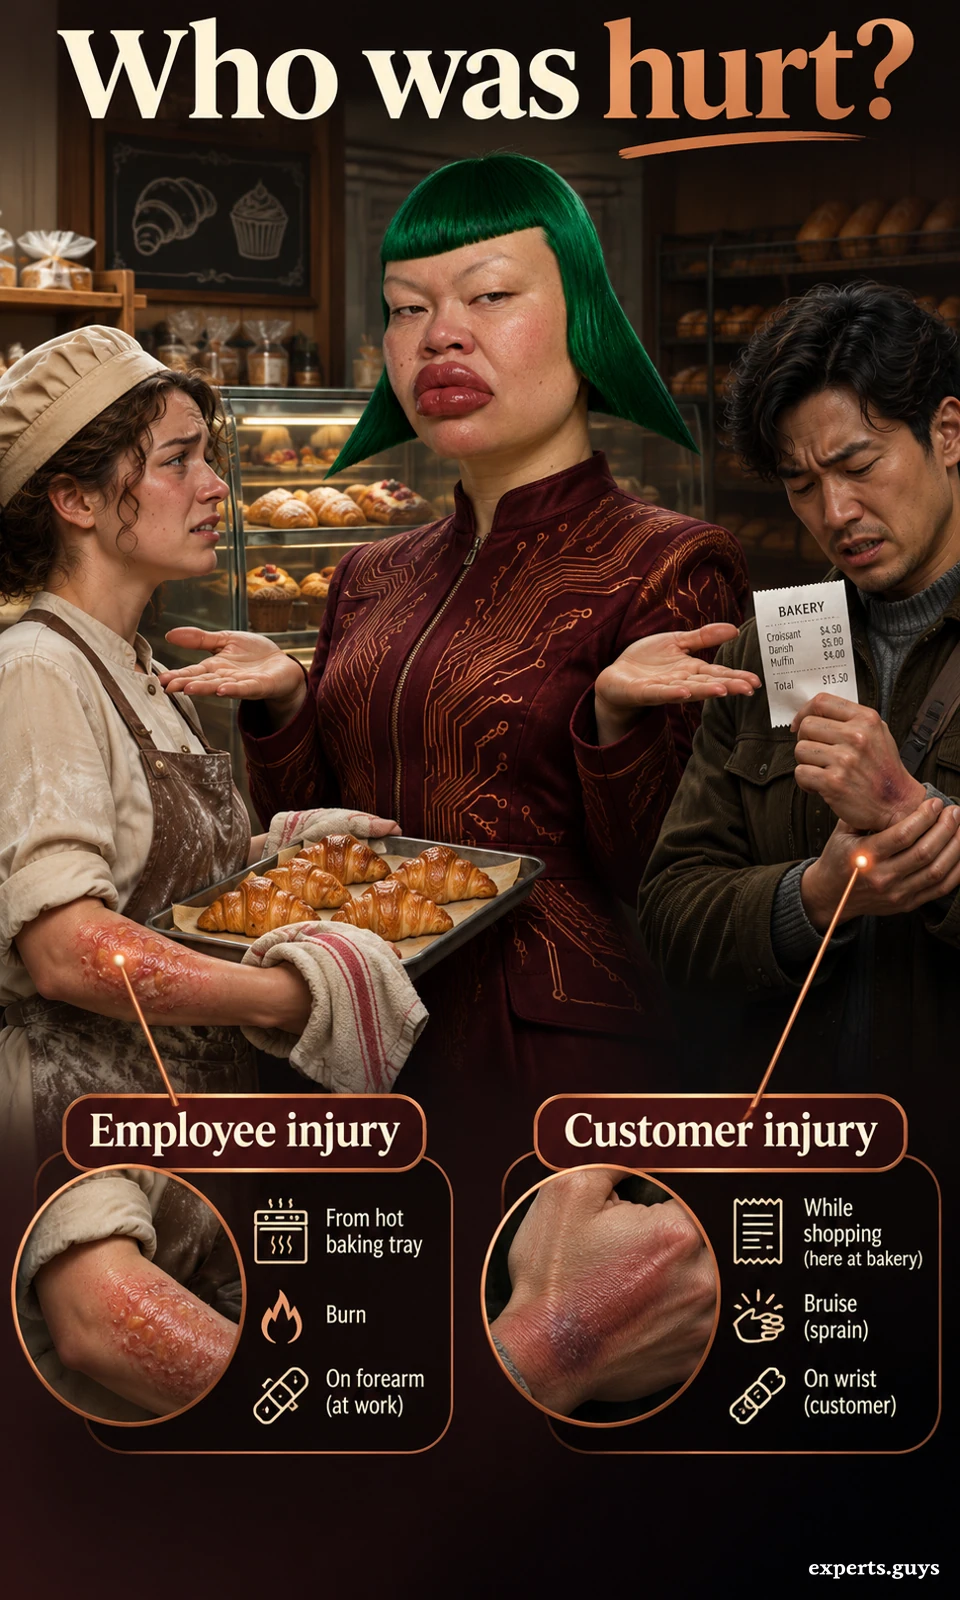
An employee slips carrying a tray during a shift. Medical treatment and time away from paid work can create immediate financial pressure. Workers’ compensation can provide medical and wage-related benefits for qualifying occupational injuries or illnesses under state rules. The employee’s status, the connection to work and the applicable jurisdiction matter. A worker injured while visiting the bakery as a customer on a day off presents a different set of facts.
For a small employer, the first hire can change obligations even if the business’s revenue barely changes. Calling someone a contractor in an agreement does not settle every classification question. A bakery that hires temporary staff for a festival needs to know which entity employs them and who arranged coverage. State requirements vary, so a national article cannot supply one employee-count threshold that works everywhere. The U.S. Small Business Administration’s business launch guidance places insurance alongside registration and employer responsibilities.
19. General liability insurance addresses harm to third parties
Now picture a customer slipping on the same bakery floor. The floor and the injury might be identical to the employee example, but the injured person’s relationship to the business has changed. A commercial general liability policy may respond to a covered claim alleging bodily injury or property damage for which the business is legally responsible. Defense can be a significant benefit even when the business disputes the allegation. Coverage depends on the claim and the contract.
A barista who spills coffee on a customer’s laptop illustrates the property damage side. A customer demanding repayment for an unpopular cake design presents a different kind of dispute. An unhappy customer, an unpaid invoice and an injury claim all cost a business time, yet they do not automatically trigger the same form of protection. Someone advising clients professionally or selling a specialized service may also need to ask about errors and omissions. The general liability label alone cannot establish coverage for a professional mistake.
| Bakery loss | Coverage to examine | Question to resolve |
|---|---|---|
| Oven destroyed | Commercial property | Who owns it and how is it valued? |
| Shop unable to open | Business income | Which expenses continued? |
| Employee injured during shift | Workers’ compensation | Was the injury work-related? |
| Customer alleges injury | General liability | What allegation triggers defense? |
How the same loss looks from two sides of a lease
A photographer rents a studio and installs lighting on ceiling tracks. A covered fire damages the fixtures, a client’s framed prints awaiting collection and the building’s plaster ceiling. The owner’s first conversation is about restoring the premises. The photographer’s first conversation is about keeping a booking for next week. If both parties simply ask whether the studio has fire insurance, each might get a reassuring answer while thinking about a completely different bill.
The lease identifies who agreed to repair particular parts of the studio. The policy identifies which property the insurer agreed to cover. Those documents can describe overlapping items in different ways. A fixture purchased by the tenant and permanently attached to the building raises a better question than “Do I have enough insurance?” The question is whether the applicable form includes that tenant improvement, how the insurer values the remaining interest in it and whose policy would handle the loss. A certificate showing that some insurance exists cannot answer all three.
Now suppose a neighboring studio offers a temporary room. The photographer can save the booking by renting lights for the afternoon. That decision reduces missed income but introduces a new expense. If the business has extra expense coverage, its terms may matter more for this particular booking than a large building limit. The studio owner, meanwhile, still needs the ceiling repaired. Neither party needs a list of nineteen quotes to understand this incident. Each needs an answer about the property, expense or income stream that belongs to them.
Frequently asked questions
Does “19 insurance” mean a specific policy?
Here it means 19 examples of financial protection. Several examples can sit inside one contract. Fire and wind damage may both be covered by a homeowners policy. A second contract might cover flood at the same address. Counting policies tells you little about which bills the household would actually be able to pay.
Can two people receive different benefits from the same accident?
Yes. A delivery van can damage a customer’s fence and injure its driver during work. The fence owner has a third-party property loss. The driver may have a work injury. The business may also have a damaged van. Each person’s relationship to the event determines which coverage wording deserves attention.
Does a medical out-of-pocket maximum cap all household costs?
No. It concerns eligible health plan cost sharing. Premiums, lost earnings and help with household chores can continue even after you reach the maximum. If a family sets aside just the maximum as its illness budget, a prolonged absence from work can still create a shortfall. Benefits available through work can change that calculation.
Will insurance pay today’s retail price for an old item?
That depends on the settlement terms. Replacement cost and actual cash value can produce different amounts for an older item. Replacement cost coverage can also have conditions governing when the full amount becomes payable. For a family replacing several appliances at once, the timing of the first payment may be as important as the final total.
What if my agent and lender use the phrase “full coverage” differently?
Ask each to name the coverage, limit and deductible they mean. A lender may be concerned with damage to financed property. A family may use the same phrase to mean protection against a large liability judgment. With a vehicle, compare the actual liability, collision and comprehensive entries. The shared phrase alone cannot settle the difference.
Is a tax saving an insurance benefit I can count on?
A policy benefit and a tax deduction are different things. Eligibility for a tax provision can depend on jurisdiction, who paid the premium and the type of arrangement. A buyer comparing U.S. health plans can assess covered care, networks and cost sharing without assuming a deduction. Any tax estimate belongs in a separate calculation using the rules for that person and tax year.
Next steps when a quote leaves a gap
Take one unresolved loss to the person issuing the quote. For the bakery owner, a good question is, “If the landlord restores the walls but my equipment is destroyed, which part pays for the equipment I lease, and how is it valued?” A reply identifying the coverage form, insured party and valuation provision gives the owner something specific to compare with the lease.
A household can do the same with a single sentence about the person whose finances would change. “My spouse could keep working, but we would have to buy childcare” describes a different need from “I would have to stop working to provide care.” If the answer changes when you switch the person or the bill, you have found the distinction that matters.