A lower refinance rate can be a good deal, but the rate alone does not tell you whether replacing your mortgage will save money. Compare the new rate with the APR, lender fees, points or credits, loan term, cash needed at closing, and how long you expect to keep the new loan before deciding.
The most useful comparison is an apples-to-apples comparison between your current mortgage and written offers for the same type of refinance. If one quote resets you to a much longer term, includes expensive points, rolls costs into the balance, or gives you cash out, a smaller monthly payment can hide a higher total cost.
The fast way to judge a refinance offer
Start with the written Loan Estimate rather than an advertised rate. For U.S. mortgages, the Loan Estimate gives you the interest rate, projected payment, closing costs, cash to close, APR and other features in a standardized format, which makes lender-to-lender comparisons much easier.
Use the interest rate to understand the cost of borrowing, but use the APR and loan-cost sections to see what you are paying to obtain that rate. Then check whether the new payment is lower because the loan is genuinely cheaper or simply because the repayment period has been stretched over more years.
| What to compare | What it tells you | What can mislead you |
|---|---|---|
| Interest rate | The rate charged on the loan balance. | A low rate may require points or higher upfront costs. |
| APR | A broader annualized measure that includes the rate plus certain loan charges. | It is not a perfect comparison when loan types or adjustable-rate structures differ. |
| Monthly principal and interest | How the new loan changes the core mortgage payment. | A longer term can lower the payment while increasing years of interest. |
| Loan costs and cash to close | What you must pay or finance to complete the refinance. | “No-closing-cost” usually means the cost is shifted into a higher rate or larger balance. |
| Loan term | How long the new repayment schedule lasts. | Restarting a 30-year term can make a payment look attractive while extending debt. |
| Break-even period | How long it may take monthly savings to recover upfront refinance costs. | A simple break-even calculation does not capture every long-term cost or cash-out difference. |
1. Compare the same loan before you compare the rate
A rate comparison only works when the offers are genuinely comparable. Ask each lender for the same loan purpose, similar term, similar loan amount, similar points or credits, and a similar rate-lock period; otherwise you may be comparing different products rather than different prices.
Timing matters as well because mortgage rates can move between the day one lender prepares a quote and the day another lender does. If the offers were produced on different days, check whether both rates are locked and whether either quote includes points, credits or conditions that explain the difference.
This is why shopping multiple lenders can be worthwhile even when the market headline rate looks settled. The lender-specific price can still differ, and the better offer may come from lower fees, fewer points or more favorable credits rather than from a dramatically lower headline rate.
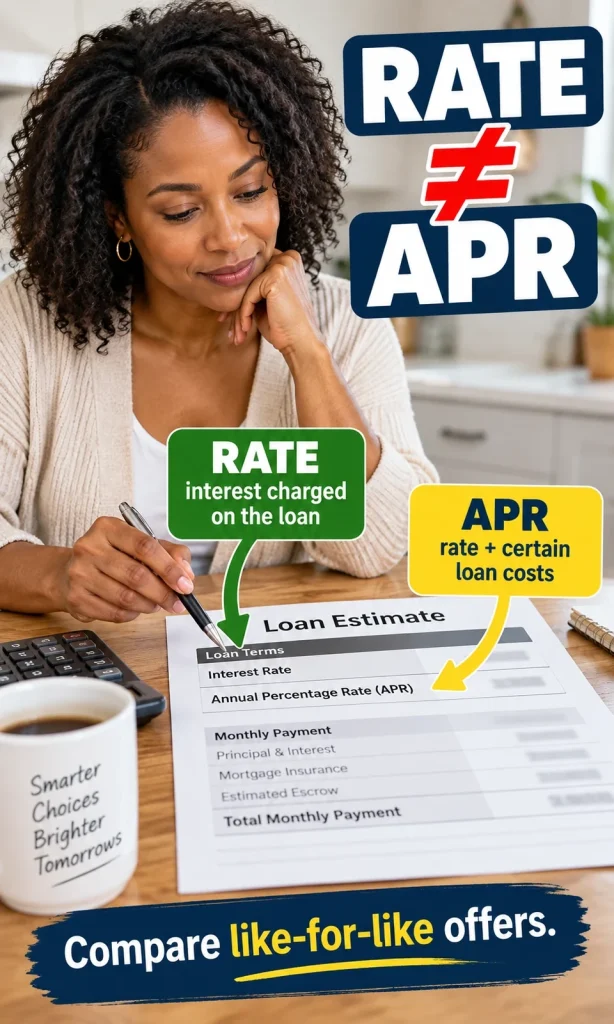
2. Read the interest rate and APR together
The interest rate shows the annual cost of borrowing the principal, while APR includes the interest rate plus certain fees and charges associated with obtaining the mortgage. The Consumer Financial Protection Bureau explains the difference between mortgage rate and APR, and the two numbers are designed to answer different questions.
If Offer A has a slightly lower rate but a noticeably higher APR than Offer B, look closely at points and lender charges. A borrower who keeps the mortgage for many years may recover the extra upfront cost, while someone likely to move or refinance again sooner may never reach that point.
3. Do not confuse a lower payment with a cheaper mortgage
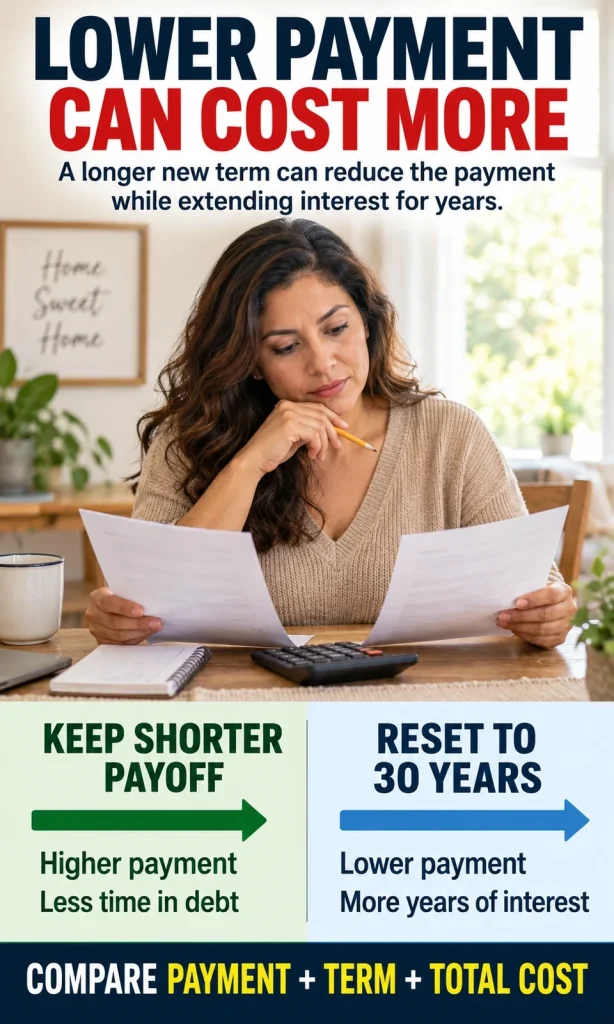
Monthly payment is important because the new loan has to fit your cash flow, but payment is not the same as total cost. If you have 18 years left on your mortgage and refinance into a new 30-year loan, the new payment can fall even when the new loan keeps you paying interest for substantially longer.
Compare the new term with the remaining term on your current mortgage, not with the term your current loan had when you first took it out. If you want the lower rate without a major term reset, ask whether a shorter refinance term or additional principal payments would keep the payoff schedule closer to your existing plan.
A shorter term may increase the monthly payment even when the rate is lower, but it can also reduce the amount of time interest accrues. That trade-off is why the strongest refinance choice is not automatically the offer with the smallest monthly number.
4. Calculate the break-even period before you pay points or closing costs
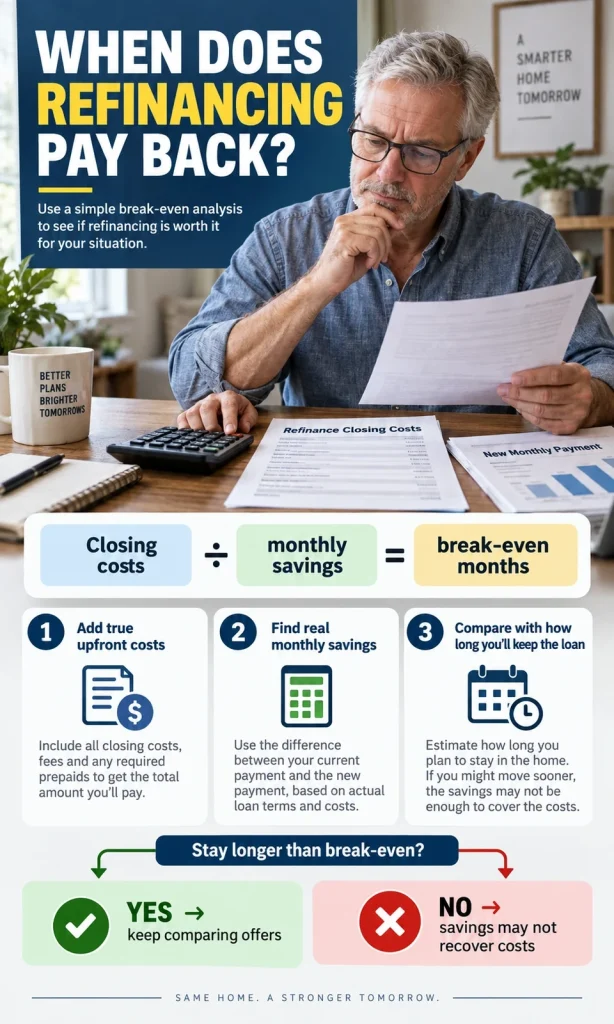
A basic refinance break-even estimate divides the costs you pay upfront by the monthly savings created by the new loan. If a refinance costs $4,800 and reduces principal-and-interest payments by $200 per month, the simple break-even period is about 24 months, so the offer becomes more interesting if you reasonably expect to keep the loan beyond that point.
Use true upfront costs in the numerator, including lender charges, required points and any prepayment penalty that actually applies. Do not treat prepaid taxes, insurance or escrow funding exactly like lender fees when you are comparing economic cost, because some prepaid amounts would have been paid regardless of the refinance.
The simple formula is useful for screening offers, but it should not be the only test. A new loan with a longer term, financed closing costs or a cash-out amount can change the balance and total interest enough that a monthly-savings break-even number looks better than the full comparison.
5. Check closing costs, points and lender credits separately
Closing costs are not a single fee, so look at which charges actually vary between lenders. Origination charges, points and lender credits can materially change the economics, while some third-party services may be similar regardless of which lender you choose.
A discount point is an upfront charge paid in exchange for a lower rate, while a lender credit typically reduces upfront cost in exchange for a higher rate. Ask for the same offer with and without points or credits so you can compare the cash required today with the payment and interest you would carry later.
If an offer is marketed as a no-closing-cost refinance, check exactly where the costs went. They may be covered by lender credits tied to a higher rate or added to the new balance, which means you are still paying for the refinance in another form.
6. Check for a prepayment penalty before replacing the old mortgage
Not every mortgage has a prepayment penalty, but refinancing normally pays off the old loan in full, so an applicable penalty can change the decision. The Loan Estimate for a new mortgage identifies whether that new loan has a prepayment penalty, while your existing note, closing documents or servicer can tell you whether the mortgage you are paying off includes one.
The CFPB guidance on prepayment penalties notes that these charges usually apply only under specific conditions and time periods. Do not assume a fixed percentage or a universal formula because the amount and trigger depend on the loan terms and applicable rules.
If your current mortgage does have a penalty, add it to the cost side of the refinance analysis before you compare savings. A rate reduction that looks attractive without the penalty can become uneconomic once the actual payoff cost is included.
7. Use the five-year cost and your own expected holding period
The Loan Estimate includes comparison information that can help you see how much interest and fees you would pay over an initial period, but your own expected holding period matters more than a generic benchmark. If you expect to sell, move, refinance again or pay the mortgage off early, compare offers over that realistic time horizon instead of assuming every loan will be held to maturity.
For the period you expect to keep the loan, estimate the interest paid, upfront costs, payment difference and remaining balance under each option. This catches situations where one loan wins on monthly payment but loses on cumulative cost, and it also shows when paying points needs more time than you are likely to give the loan.
- Short expected hold: lower upfront costs often matter more because there is less time to recover points or fees.
- Long expected hold: a lower rate can become more valuable because the monthly interest advantage has more time to accumulate.
- Uncertain plans: compare a short and a long scenario instead of betting on one exact move date.
- Term reset: compare the balance remaining after your expected hold period, not only the monthly payment.
8. Treat cash-out refinancing as a different decision
A cash-out refinance does more than replace the existing mortgage because it also increases the amount you borrow and reduces home equity. The rate may still be attractive, but the decision should account for the extra principal, the purpose of the cash, and the additional interest created by financing that amount over a mortgage term.
If the goal is debt consolidation or renovation, compare the refinance with alternatives rather than assuming mortgage debt is automatically cheaper. Securing additional debt against the home changes the risk, and stretching a short-term expense over many years can make a low monthly payment expensive in total dollars.
For a broader explanation of the process, see how mortgage refinancing works. If your main goal is to change the payment without replacing the mortgage, it may also be worth comparing a mortgage recast versus refinance where your loan and servicer permit it.
9. Run the offer against your actual mortgage
A useful refinance comparison should show more than the new monthly payment. It should compare the current loan with the proposed rate, new term, upfront costs, financed costs, expected holding period and remaining balance so you can see whether the offer improves the part of the mortgage that matters to you.
Use the interactive experience below to model your current mortgage and up to two refinance offers. It is designed to show payment change, simple break-even, interest-and-cost impact over your expected holding period, term-reset warnings and the difference between paying costs upfront and financing them into the new balance.
Mortgage refinance decision support
Refinance Offer
Reality Check
Compare your current mortgage with up to two refinance offers. See payment change, break-even timing, term-reset risk, and the interest-and-cost impact over the years you expect to keep the loan.
Your comparison
What changes if you refinance?
How to read the break-even result
The simple break-even calculation divides cash paid upfront by monthly principal-and-interest savings. If the new payment is not lower, use the time-horizon cost and remaining-balance comparison instead.
Why term reset matters
A new 30-year loan can reduce the monthly payment even when you already have far fewer than 30 years left. A longer payoff period is a trade-off, not automatic savings.
Cash-out changes the comparison
If you add cash-out, you are borrowing more money. The experience still shows the payment and interest effect, but a cash-out offer is not a pure apples-to-apples rate-and-term replacement.
10. Common refinance comparison mistakes
Most poor refinance comparisons are not caused by difficult mathematics; they come from comparing different assumptions. Keep the loan amount, purpose, term, lock status and points structure clear, then check how each change affects the result before you decide.
- Choosing the lowest advertised rate: the offer may require points, stronger borrower qualifications or a different lock period.
- Comparing quotes from different days: market movement can make a lender look cheaper or more expensive for reasons unrelated to its pricing.
- Ignoring the remaining term: restarting a long term can lower the payment while extending debt.
- Treating all closing cash as a sunk cost: prepaid taxes, insurance and escrow funding are different from lender fees and points.
- Ignoring financed costs: adding costs to the new balance reduces the cash needed at closing but increases the amount on which interest is charged.
- Using only a simple break-even number: it may miss term reset, cash-out, balance differences and long-run interest.
- Assuming 20% equity is always required: refinance eligibility and loan-to-value limits vary by program, loan purpose and borrower profile.
Questions people ask before refinancing
1. How much lower does my mortgage rate need to be before refinancing makes sense?
There is no universal rate-drop rule because closing costs, remaining term, loan balance and expected holding period change the answer. Compare the actual dollar savings with the costs and use a break-even and time-horizon analysis rather than waiting for a specific rate difference.
2. Is APR more important than the mortgage interest rate?
APR is broader because it includes the interest rate plus certain costs, but it should not replace the rate in your analysis. Read both numbers together and make sure the loan type, term and assumptions are comparable before treating one APR as clearly better.
3. Is a no-closing-cost refinance really free?
No. The costs are commonly offset with a lender credit tied to a higher rate or added to the loan balance, so compare the resulting payment, interest and balance with an offer that charges costs upfront.
4. Should I refinance into another 30-year mortgage?
It can be reasonable when cash-flow flexibility is the priority, but compare it with your current remaining term because a new 30-year schedule can extend the time you remain in debt. If you can afford a higher payment, ask for shorter-term alternatives as well.
5. How many refinance quotes should I get?
Get enough written offers to see whether pricing is meaningfully different, and make the requests close together so market movement does not distort the comparison. Multiple Loan Estimates also give you leverage to ask lenders whether they can improve a rate, fee or credit.
6. Can I refinance without an appraisal?
Sometimes. Eligibility depends on the loan program, property, automated underwriting result and lender requirements, so see the separate guide to whether you can refinance without an appraisal.
Decision summary
Use mortgage and refinance rates as the starting point, not the decision itself. The better refinance is the offer that performs best for your actual loan balance, remaining term, fees, expected holding period and financial goal after you account for the costs required to obtain it.
Before committing, compare standardized Loan Estimates, verify any prepayment penalty, separate points and credits from the rate, calculate a realistic break-even period, and check what happens to your balance over the years you expect to keep the loan. If the lower payment comes mainly from restarting the clock or financing costs, treat that as a trade-off rather than automatic savings.