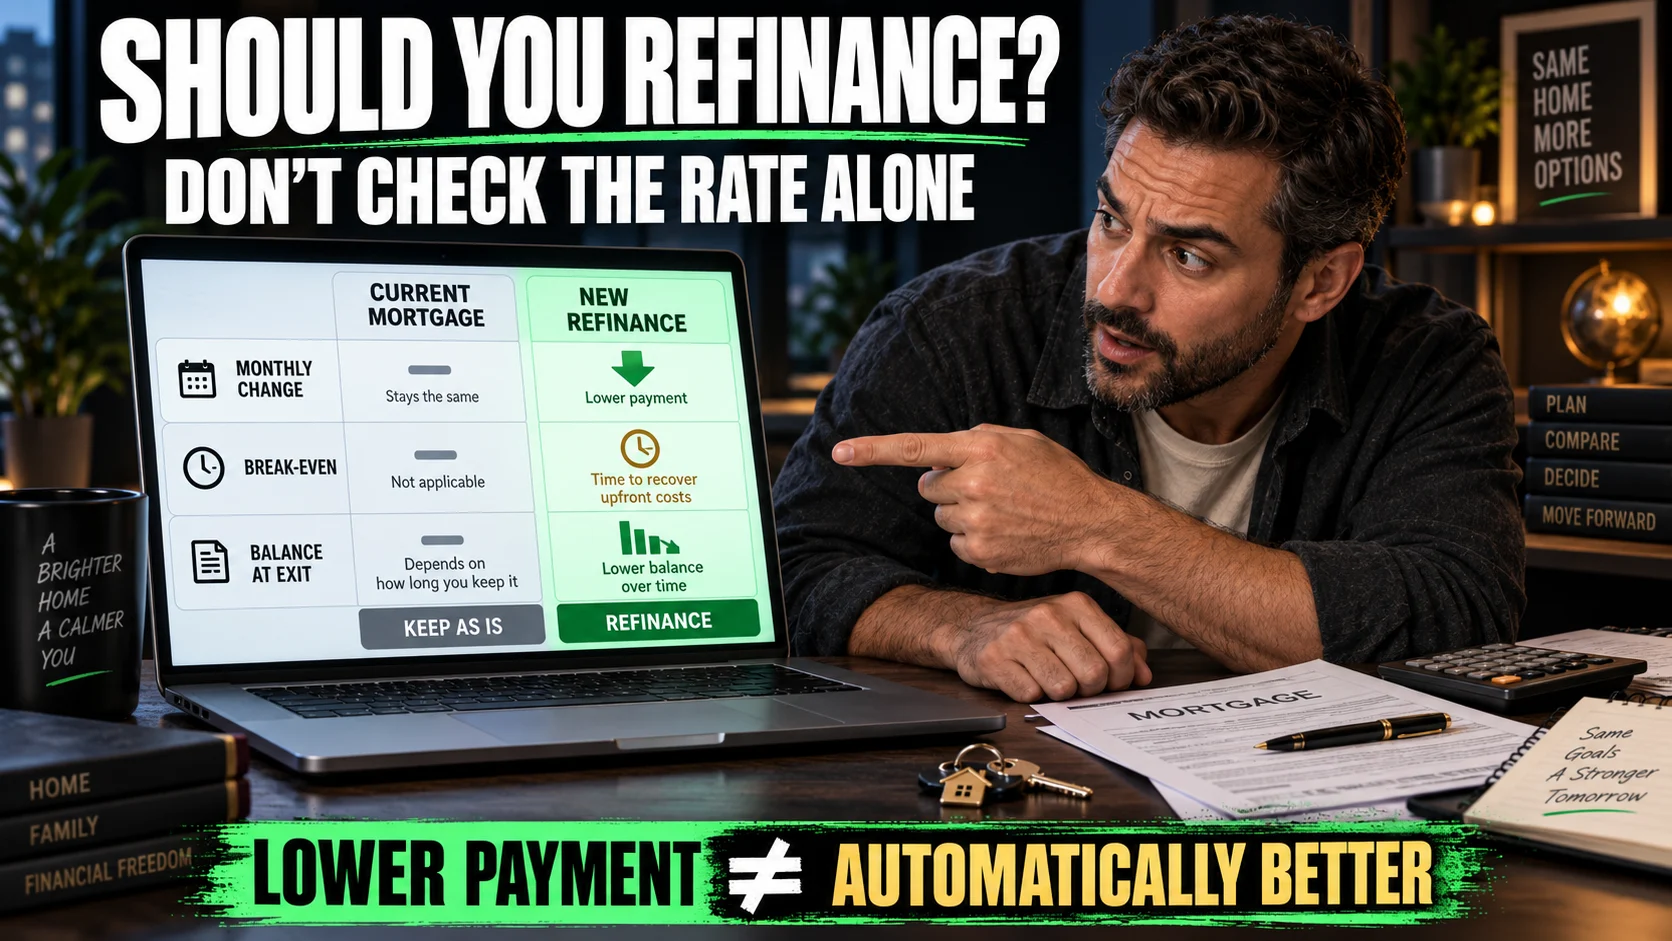
A refinance is worth considering when the new loan mproves more than the first monthly payment. The useful calculation compares the payment change, permanent refinance costs, how long you expect to keep the loan, and the mortgage balance you may still owe when you sell or refinance again. A lower payment can be a real saving, but it can also come from stretching the debt over a longer new term.
The calculator below is designed for that fuller comparison. Enter the mortgage you have now and a real refinance quote when you have one, then use the result to see whether the proposed loan lowers monthly cost, recovers its fees within your holding period, and leaves you with a reasonable balance at the point you expect to exit.
| If Your Main Goal Is… | The First Number to Check | What Can Change the Answer |
|---|---|---|
| Lower monthly payment | New principal and interest compared with your current principal and interest. | A longer term can lower the payment while slowing principal payoff. |
| Recover closing costs | Permanent refinance costs divided by monthly savings. | Points, lender credits, financed costs, and how long you keep the new loan. |
| Reduce borrowing cost | Interest and permanent costs over your expected holding period. | The new term, mortgage insurance, points, and whether costs are financed. |
| Build equity faster | Mortgage balance at the date you expect to sell or refinance again. | Restarting a long amortization can leave more principal outstanding. |
Refi Decision Lab
Compare the mortgage you already have with a proposed refinance using payment change, permanent closing costs, simple break-even, interest over your holding period, and the balance you may still owe when you exit.
Find refinance lenders in your area
Search the public web without an API key, then bring real candidates back here for a structured side-by-side comparison.
Compare up to three real lender offers
Use the same loan type and similar lock timing when possible. Ratings and reviews are shown for context but are not used as a substitute for pricing or licensing checks.
What a Mortgage Refinance Calculator Should Actually Tell You
A basic refinance calculator often stops after comparing one payment with another. That is useful, but it is incomplete because refinancing creates a new loan with its own term, interest schedule, closing costs, points, lender credits, and sometimes mortgage insurance. The stronger calculation asks whether the new structure is better during the period you realistically expect to keep it.
There are therefore two different questions hiding inside the word savings. Cash-flow savings describe how much the required monthly loan payment falls, while financing-cost savings describe whether interest, mortgage insurance, and permanent refinance costs are actually lower over the holding period you choose. A refinance can pass one test and fail the other.
The balance at exit is the third part of the decision. If you refinance a mortgage with 18 years remaining into a new 30-year loan, the monthly payment may fall partly because the same debt is being spread over a much longer period. Looking at the balance after five or seven years makes that trade-off visible instead of letting the first payment carry the whole decision.
Use Your Current Payoff, Not the Original Loan Amount
Start with the mortgage balance that would actually need to be paid off now. The amount you originally borrowed may be substantially higher than your current unpaid principal, and using the original figure can distort the new payment, points, loan-to-value ratio, and closing-cost comparison. Your latest mortgage statement is a reasonable starting point, while the lender’s formal payoff figure will be more precise when the transaction is underway.
You also need the remaining term rather than the original term. A borrower who is eight years into a 30-year mortgage does not have 30 years left on the existing loan, so comparing it with a new 30-year refinance means comparing roughly 22 years of remaining amortization with a fresh 30-year schedule. That difference is one of the main reasons a refinance can produce a smaller payment without producing the best long-run result.
Monthly Savings Are Useful, but They Are Only the First Test
For a fixed-rate mortgage, principal and interest can be modeled from three inputs: current principal, interest rate, and months remaining. The proposed refinance uses the new principal, new rate, and new term. If mortgage insurance applies to either loan, include it separately because a change in PMI or MIP can materially alter the monthly result even when the interest-rate difference looks modest.
Property taxes and homeowners insurance usually belong outside the core refinance-savings calculation because refinancing does not automatically change what the property is taxed or insured for. They still matter to the household budget, but comparing one mortgage structure with another is clearer when the loan payment is separated from costs that may continue regardless of lender. Prepaid taxes, prepaid insurance, and escrow deposits can also increase cash needed at closing without being the same thing as a permanent loan fee.
How to Calculate Refinance Break-Even
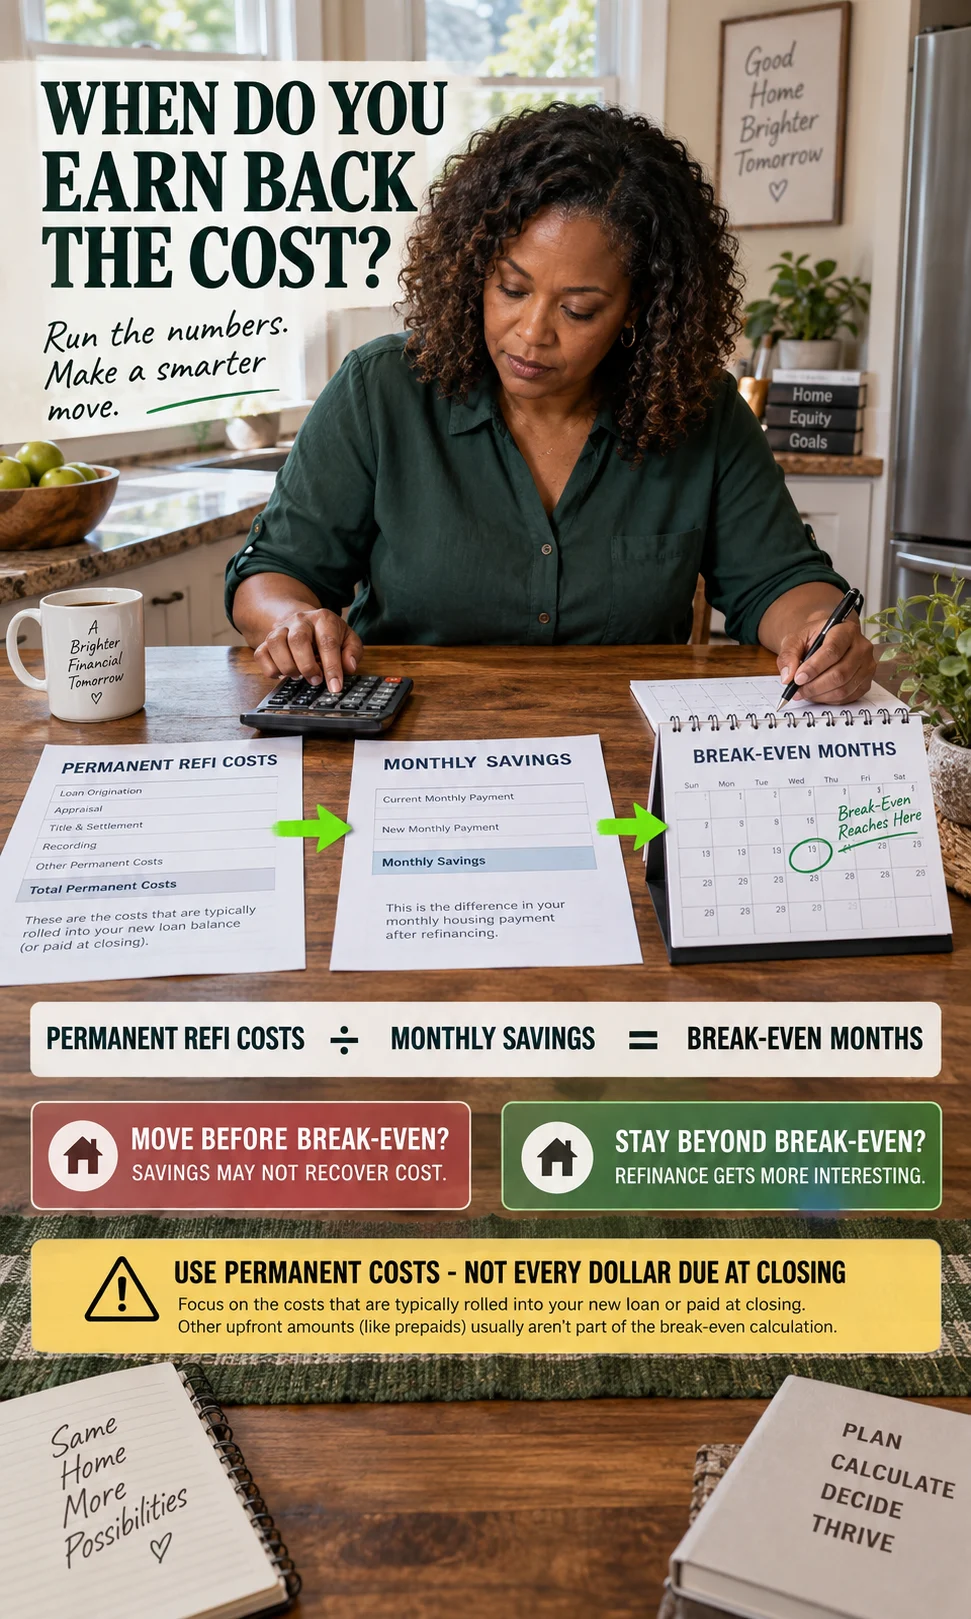
The familiar simple break-even formula is permanent refinance costs divided by monthly savings. If permanent costs are $6,000 and the new payment saves $250 a month, the simple payback is about 24 months. If you expect to replace or sell the property before that point, paying those costs for the payment reduction deserves much closer scrutiny.
The formula is useful because it converts a pile of closing charges into a time test, but it should not be treated as the final answer. It does not tell you how much principal each loan has paid down, and it can be distorted when the new loan carries a much longer term. That is why the calculator also compares interest and the balance remaining at your selected exit date.
When you compare written offers, the Loan Estimate comparison framework is especially useful because it separates the loan amount, rate, monthly payment, origination charges, lender credits, cash to close, and longer-horizon cost information. Use those figures instead of relying only on an advertised rate or a verbal quote.
Permanent Closing Costs and Prepaids Should Not Be Mixed Together
Closing day can require a large amount of cash even when the permanent price of refinancing is much smaller. Origination charges, appraisal or valuation fees, title charges, recording charges, and discount points can represent permanent transaction costs, while prepaid interest, homeowners insurance, taxes, and escrow funding can be timing items associated with closing. Mixing everything into one break-even numerator can make the refinance appear more expensive than it really is.
The reverse mistake is just as common. Borrowers sometimes exclude points or lender fees because they are being financed into the replacement loan rather than paid with cash at closing. Financing a cost does not make it disappear; it increases the starting loan balance and can add interest to that cost over time.
The calculator therefore treats modeled permanent refinance costs as part of the cost comparison whether you pay them upfront or add eligible costs to the new principal. Prepaids and escrow funding are shown as cash-to-close items, but they are not automatically treated as permanent borrowing costs.
How Discount Points Change the Calculation
A discount point is generally expressed as a percentage of the loan amount, with one point equal to 1% of that amount. Paying points can reduce the offered interest rate, but the size of the rate reduction is not fixed across lenders, loan products, or market conditions. The decision therefore depends on the actual rate difference you receive and how long you expect to keep the loan.
That makes points another break-even problem. Paying more upfront for a lower rate is more likely to make sense when the loan will be kept long enough for the lower payment and interest cost to recover the extra upfront charge. The points and lender credits guidance recommends comparing versions of the same loan with and without those pricing adjustments across more than one plausible holding period.
Do not enter a generic point assumption just because another borrower paid one point. Enter the actual points shown in the quote you are evaluating, then rerun the calculator for the zero-point or lender-credit alternative if the lender can provide it. That shows what the pricing trade is doing instead of treating the lowest advertised rate as automatically cheapest.
Lender Credits Reduce Cash Today but Usually Trade Against Rate
Lender credits can offset some closing costs, which is useful when preserving cash is a priority. In many rate-credit structures, the borrower accepts a higher rate in exchange for those credits, so the transaction shifts part of the price from closing day into the monthly payment. A so-called low-cost refinance can therefore be financially different from a truly lower-cost loan.
If this trade is central to your decision, compare the full structure in the no-closing-cost refinance guide. The calculator on this page lets you enter the lender credit directly so you can see how much permanent cost remains after that credit and whether the associated rate still works over your holding period.
Why the New Mortgage Balance Matters
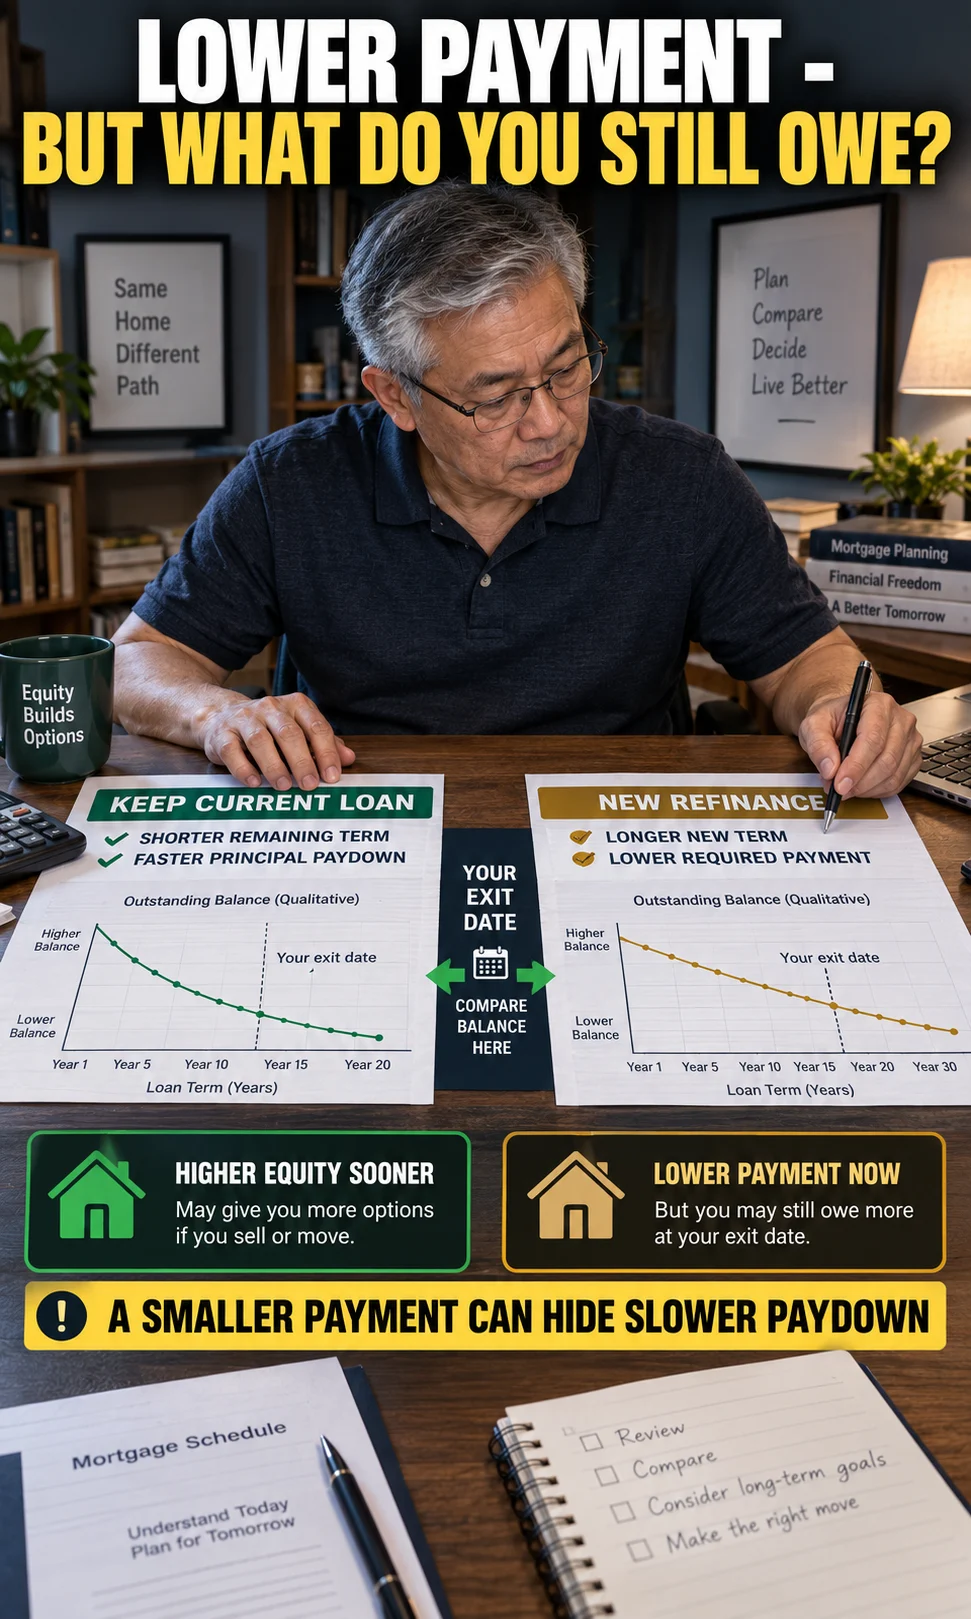
A refinance can start with a larger principal than the balance you owe today. That can happen because eligible closing costs are financed, a cash-out amount is added, or the new structure includes another financed amount. The new payment must therefore be judged against the debt being created, not only against the old payment.
For rate-and-term refinancing, a noticeably higher balance at exit is often a clue that the lower payment is partly being purchased with slower amortization. That does not make the refinance automatically wrong, because some households intentionally prioritize monthly cash flow. It does mean the payment reduction should be described accurately rather than presented as pure savings.
For cash-out refinancing, the comparison changes again because the borrower is intentionally receiving additional money. A higher balance may be expected, so the decision should focus on the amount of equity converted to debt, the rate applied to the entire new mortgage, and whether another borrowing structure would preserve a valuable first mortgage. The calculator flags cash-out entries so the monthly-savings result is not mistaken for an apples-to-apples rate-and-term comparison.
Holding Period Is More Useful Than Asking Whether You Will Stay Forever
Most homeowners do not need to predict the exact day they will sell. They do need a realistic range for how long they may keep the replacement mortgage before selling, refinancing again, paying it off, or making another major housing decision. Testing several holding periods makes the comparison more durable than relying on a single optimistic forecast.
Run the numbers once using the shortest period you can realistically imagine, again using your most likely period, and a third time using a longer period. A refinance that looks strong under all three is more robust than one that works only if you keep the loan for an unusually long time. Freddie Mac’s refinancing cost guidance likewise treats refinance costs as part of the financial decision rather than separating them from the payment benefit.
When a Lower Rate Can Still Produce a Weak Refinance
A lower note rate is valuable, but it can be overwhelmed by the rest of the transaction. Paying heavy points, restarting a long term, financing large closing costs, or adding mortgage insurance can reduce or eliminate the advantage. The rate is therefore an input to the decision rather than the decision itself.
This is especially important when the current mortgage already has a short remaining term. A new 30-year refinance may cut the required payment dramatically even if the new rate is only modestly lower, but the borrower could remain in debt many years longer. Compare the new loan with a shorter-term refinance before assuming the 30-year quote is the best version of the deal.
What If Refinancing Raises the Payment?
A refinance that increases the payment can still have a legitimate purpose. A borrower might move from a long remaining term into a 15-year loan, replace an adjustable-rate structure with a fixed loan, eliminate a risk they no longer want, or intentionally accelerate principal repayment. In those cases, the higher payment should be evaluated against the specific benefit being purchased.
If the refinance raises both the payment and modeled financing cost without solving another meaningful problem, the calculator should make that visible. There is no need to force a refinance simply because a new rate quote exists. The broader mortgage refinance guide is the better place to compare reasons for refinancing beyond payment savings.
What If You Can Lower the Payment Without Refinancing?
Homeowners with a large amount of cash sometimes have another option: apply a substantial principal payment to the existing mortgage and ask whether the servicer allows a recast. A recast keeps the existing mortgage and recalculates the required payment on the lower principal balance, while a refinance replaces the loan. If your current rate is attractive and the main objective is a lower required payment, compare the two structures before giving up the existing mortgage.
The mortgage recast vs refinance comparison explains that decision in detail. The key distinction is whether the mortgage itself needs to change or whether you only need the payment to recognize a lower balance.
Do You Need an Appraisal for the Refinance?
Do not automatically add a full appraisal fee just because you are refinancing. Some conventional transactions can receive an automated collateral alternative, and certain streamlined government refinance programs can operate without a traditional appraisal when their rules are met. The lender’s underwriting route, loan program, transaction type, and property information determine what is actually required.
If avoiding a traditional appraisal materially affects your cost or timing, review the refinance without an appraisal guide before ordering one independently. The practical point is to confirm the lender’s collateral route first, because an appraisal is not merely a line item to add automatically to every refinance calculation.
How to Compare Three Refinance Offers Fairly
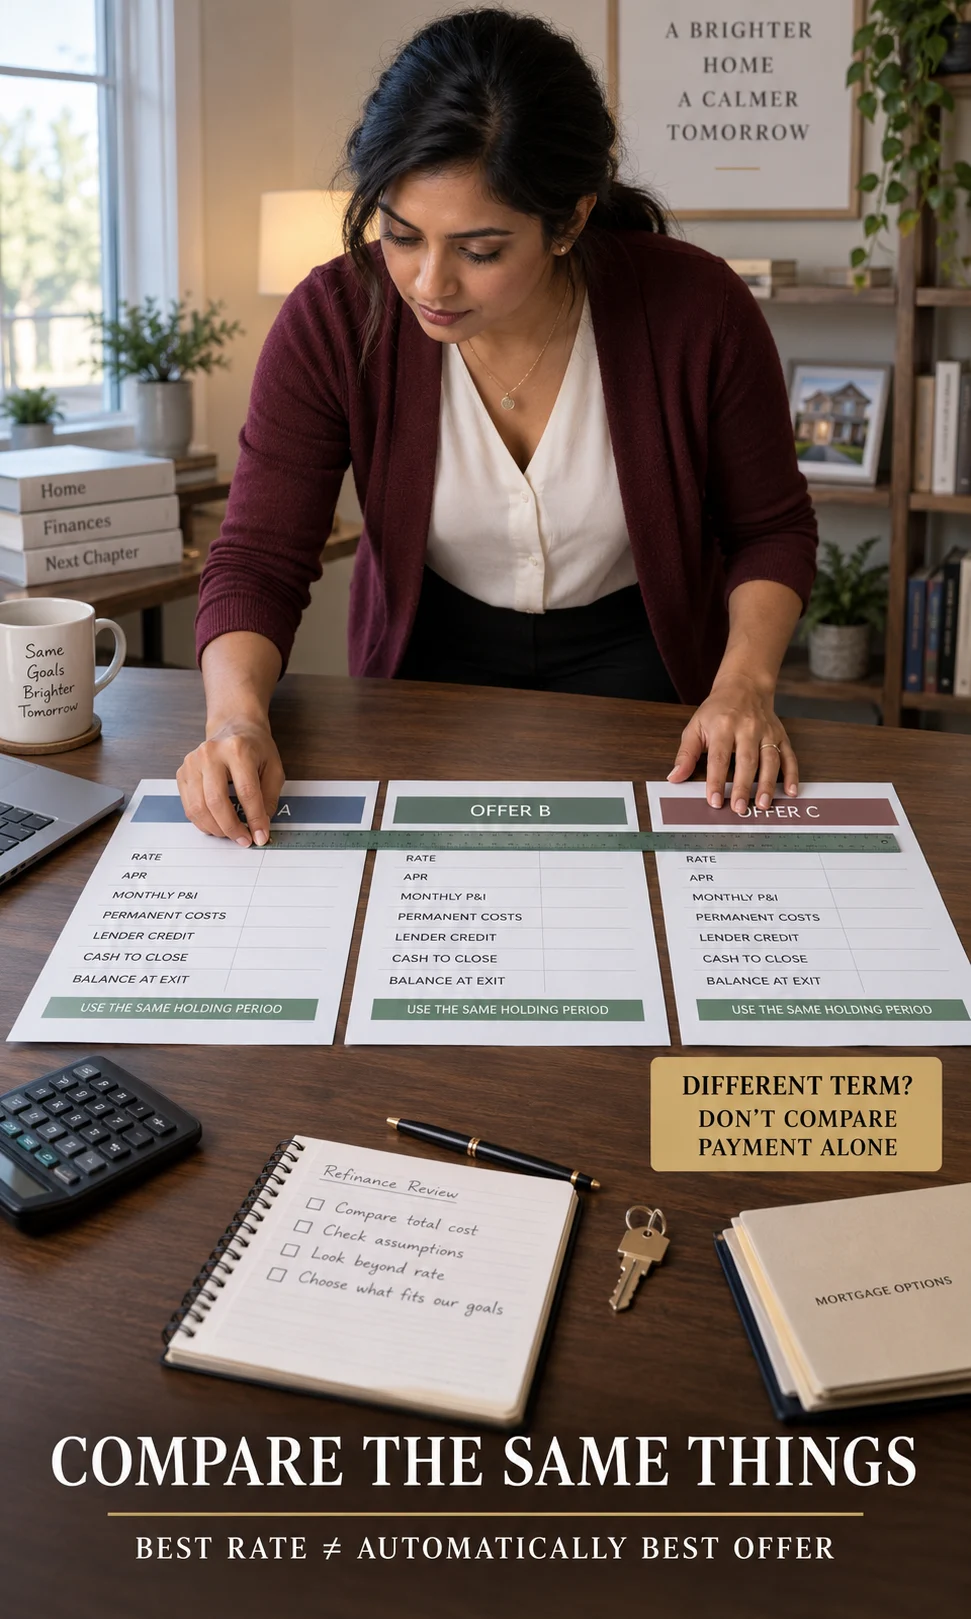
Comparing lenders is useful only when the offers are similar enough to be compared. A quote with a 15-day lock and heavy discount points is not the same product as a zero-point quote with a 45-day lock, even when the headline rate looks better. Ask each lender for the same loan purpose, similar term, similar lock timing, and the same approach to points or credits where possible.
- Note rate: the contractual interest rate used to calculate principal and interest.
- APR: a broader standardized cost measure that includes certain finance charges, but it should still be read with the actual Loan Estimate.
- Origination charges: lender-controlled fees that deserve close comparison.
- Points: upfront charges tied to the rate option.
- Lender credits: credits that reduce closing costs and may be connected to a higher rate.
- Cash to close: the amount you are expected to bring after costs, credits, prepaids, escrow, and other adjustments.
- Rate-lock period: whether the quoted pricing is likely to remain available through your expected closing date.
- Balance after your holding period: how much debt each structure leaves outstanding when you expect to exit.
The interactive comparison section lets you enter up to three real candidates from your own search results or Loan Estimates. It does not create lender names, ratings, review counts, licensing status, or availability because those details should come from information you actually found and verified.
Common Mortgage Refinance Calculator Mistakes
Using the Original Mortgage Amount
Your original loan amount is historical. A refinance pays off the balance you owe now, so using the original principal can overstate the proposed loan and distort the payment comparison. Start with the current unpaid principal or lender payoff figure instead.
Treating Every Closing-Day Dollar as a Permanent Cost
Prepaid taxes, insurance, and escrow funding can increase cash to close without representing the same kind of expense as an origination charge or discount point. Separate them so the break-even calculation is not inflated. The calculator shows prepaids in cash due while excluding them from its modeled permanent-cost total.
Ignoring Financed Costs
Rolling eligible costs into the new loan can reduce cash needed today, but it also increases principal. The borrower then pays interest on that larger balance unless the amount is paid down early. Enter financed costs honestly instead of treating a zero-upfront-cost refinance as a zero-cost transaction.
Comparing a New 30-Year Loan With a Much Shorter Remaining Term
This is one of the easiest ways to manufacture an attractive payment. The new mortgage may look cheaper every month because principal is being repaid more slowly. Compare the balance at your expected exit date and ask for a shorter-term quote before making the decision.
Using a Rate Advertisement Instead of a Real Quote
Advertised rates can assume a particular credit profile, property, loan amount, occupancy, points, or other conditions. A calculator becomes much more useful once you replace example numbers with the actual terms offered to you. The final decision should be based on the written loan structure rather than the most attractive number in an advertisement.
When the Numbers Usually Support a Refinance
The strongest rate-and-term refinance cases tend to share the same structure. The new loan reduces monthly cost, the permanent fees are recovered comfortably inside the expected holding period, the new term does not create an unacceptable balance at exit, and the borrower is not giving up a valuable feature of the existing mortgage. None of those conditions requires a magic interest-rate reduction.
A smaller rate drop can work when costs are low and the loan is kept long enough, while a much larger rate drop can still disappoint if points, fees, or term extension are excessive. Use the calculator to find the relationship between the numbers rather than relying on a rule such as “refinance only when the rate falls by one percentage point.”
When the Numbers Suggest Waiting
Waiting deserves consideration when the new monthly cost is not lower, break-even arrives after your likely exit date, the refinance leaves much more principal outstanding, or the quote depends on expensive points that your holding period cannot recover. A refinance can also be premature when you are close to another financial change that could alter the loan amount, property ownership, or time you expect to remain in the home.
Waiting does not require predicting future mortgage rates. It simply means the transaction available today does not yet solve enough of your problem to justify replacing the current mortgage. You can keep the current loan and compare again when your numbers or the available offers materially change.
Frequently Asked Questions
How do I calculate whether refinancing is worth it?
Compare the current mortgage with the proposed refinance using monthly principal and interest, mortgage insurance if applicable, permanent refinance costs, the number of months you expect to keep the new loan, and the balance remaining at that point. A refinance is more compelling when the payment benefit and financing-cost benefit both survive your realistic holding period rather than appearing only because the new term is longer.
What is the refinance break-even formula?
The simple formula is permanent refinance costs divided by monthly savings. If the permanent costs are $6,000 and the new payment saves $250 a month, simple break-even is about 24 months. Check the balance at exit as well, because a longer new term can create a smaller payment while leaving more principal outstanding.
Should I include escrow and prepaids in refinance break-even?
Do not automatically treat every escrow deposit or prepaid item as a permanent refinance cost. They can affect the cash you need at closing, but taxes, insurance, prepaid interest, and escrow funding have different economic treatment from origination fees or discount points. Separate them in the calculation and confirm the actual figures on the Loan Estimate.
Does financing closing costs make a refinance free?
No. Financing eligible costs reduces the amount of cash you may need upfront, but it adds those costs to the mortgage principal and can add interest over time. A lender-credit structure can also reduce cash at closing while being paired with a higher interest rate, so compare the full pricing rather than the upfront bill alone.
How many lenders should I compare for a refinance?
Three written offers give you a practical starting point for comparing rate, APR, origination charges, points, lender credits, cash to close, and lock terms. Make the loan structures as similar as possible so you are comparing lender pricing rather than three different mortgage products.
Can refinancing save money if I plan to move soon?
It can, but a short holding period makes upfront costs more difficult to recover. Run the calculator using the earliest date you could realistically move and compare that result with your most likely holding period. If the transaction works only under a much longer assumption, the savings case is fragile.
Why can a refinance lower my payment but leave me owing more later?
A new refinance can restart amortization over a longer term. Spreading principal across more months can reduce the required payment even when the rate reduction is modest, but principal may be repaid more slowly. Compare the mortgage balance at your expected exit date to see whether the lower payment is partly being purchased with slower equity growth.
Next Steps
Run the calculator first with the quote you are actually considering, then repeat it with a shorter holding period and a longer one. If the result still looks attractive, request comparable Loan Estimates from several lenders and replace every example field with the written terms from those offers. The strongest refinance is the one that still works after the rate, costs, term, mortgage insurance, cash to close, and balance at exit are all viewed together.
If the new loan only looks good because the payment is smaller, investigate why before committing. A genuine improvement should solve the reason you are refinancing without hiding the cost in a longer term, a larger balance, expensive points, or a holding period you are unlikely to reach.