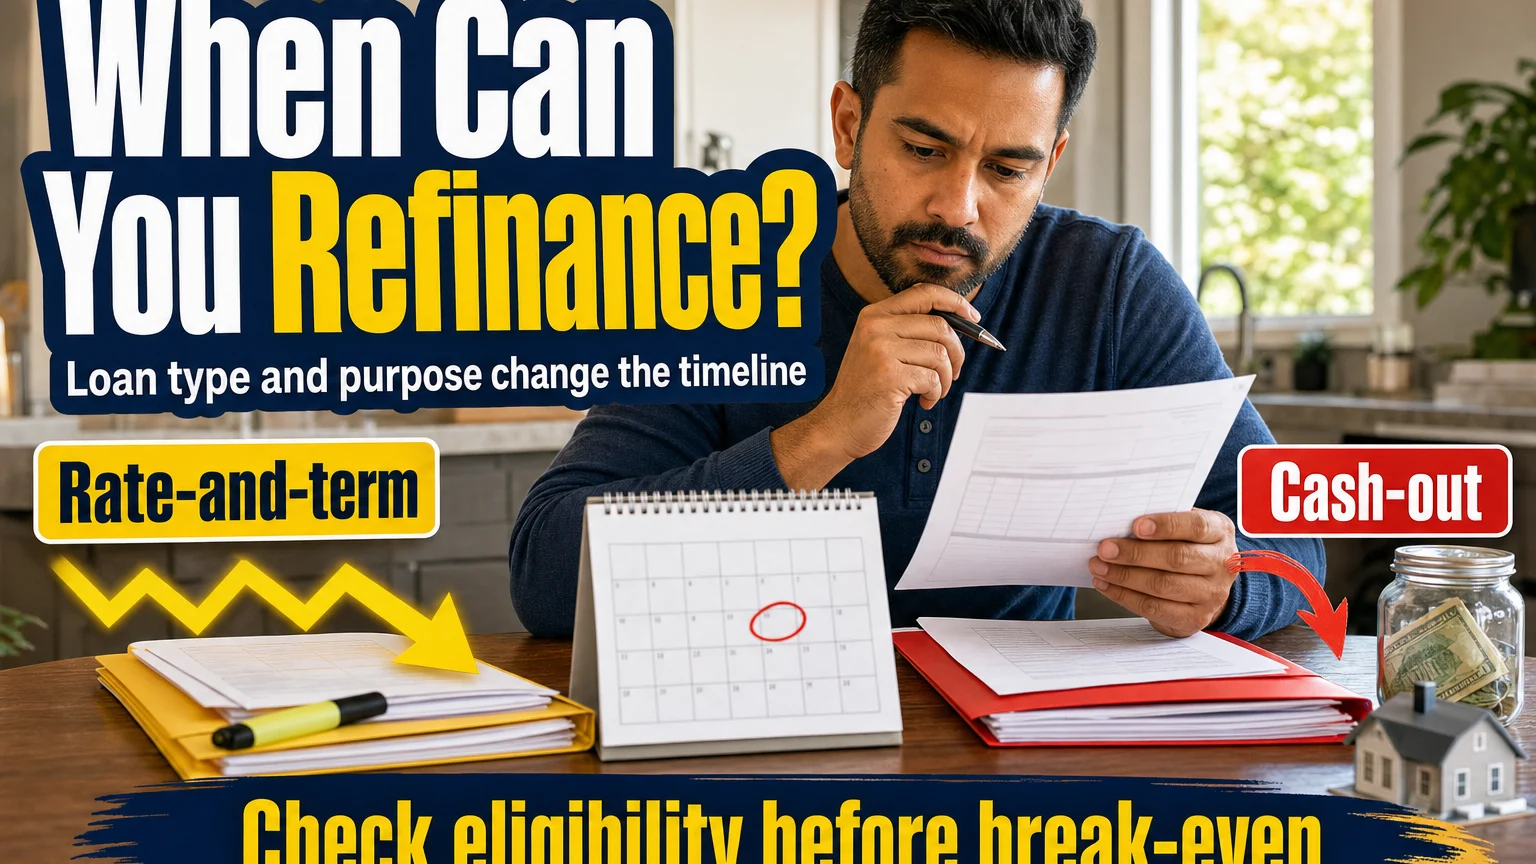
You may be able to refinance a mortgage surprisingly soon after buying a house, but there is no single waiting period that applies to every homeowner, lender, or refinance type. A conventional rate-and-term refinance can follow one timing framework, while conventional cash-out, FHA, VA, and USDA refinances can apply their own seasoning or ownership requirements. The useful question is therefore not simply how many months have passed since closing, because the purpose of the new refinance determines much of the answer.
This distinction matters when mortgage rates fall shortly after a home purchase. A homeowner can close on a new house, watch market rates move lower a few months later, and understandably wonder whether the original mortgage can already be replaced. In some situations the answer may be yes, but qualifying for another mortgage and making a financially worthwhile decision remain two different questions.
The same issue appears when the homeowner wants cash rather than merely a lower rate. A refinance designed primarily to replace the existing first mortgage with better pricing can have different eligibility requirements from a cash-out refinance that increases the debt and extracts equity. Current Fannie Mae rules, for example, distinguish limited cash-out refinances from cash-out transactions, with the latter generally requiring an existing first mortgage being paid off through the transaction to be at least 12 months old, subject to specific exceptions. Fannie Mae cash-out refinance requirements
Homeowners also need to separate the earliest date a refinance might be permitted from the earliest date it actually makes sense. Buying a home and then refinancing several months later can create another round of closing costs before the purchase mortgage has been in place long enough to produce much value. A refinance that saves $150 per month but costs $6,000 to complete has a very different case from one that saves $700 per month with minimal new costs.
For someone considering a refinance in 2026, I would therefore begin with four facts: the mortgage you currently have, the type of refinance you want, the amount the new transaction will cost, and how long you expect to keep the replacement mortgage. Once those pieces are known, the calendar becomes much easier to interpret. The answer is usually less about reaching an arbitrary anniversary and more about whether your particular loan has become eligible and economically worth replacing.
How Soon Can You Refinance?
Choose the refinance you are considering, enter the dates from your current mortgage, and get an estimated timing checkpoint together with a simple cost-recovery check.
Your Mortgage Dates
Your Timing Result
The timing result will appear here after the required fields are available.
- The applicable timing checks will appear here.
Cost Recovery
Eligibility and financial value are separate questions, so the calculation checks both.
Prepare Before You Apply
- Current mortgage statement and payoff information.
- Original closing date and first-payment due date.
- Recent payment history.
- Income, asset and debt documentation requested by the lender.
- Realistic refinance costs and a comparable new payment estimate.
Property value, equity, credit, income, underwriting, payment history and lender overlays can still affect whether a refinance is available.
Is There a Universal Waiting Period Before You Can Refinance?
No universal federal rule requires every homeowner to wait six months, one year, or another fixed period before every possible mortgage refinance. Waiting periods and seasoning requirements depend on the mortgage being refinanced, the replacement loan, the purpose of the transaction, and sometimes the investor or lender purchasing the new mortgage. A lender can also apply requirements that are more restrictive than the minimum requirements of a particular mortgage program.
That is why two neighbors who purchased homes during the same week can receive different answers about refinancing. One may have a conventional mortgage and only want to reduce the rate, while the other may have an FHA mortgage and want an FHA Streamline or may be trying to take substantial cash from recently acquired equity. The refinance names sound similar, but their rules and underwriting objectives can be very different.
The broad mortgage refinance guide is useful when the main question is whether replacing the mortgage makes financial sense. This page is narrower because the focus is whether the mortgage has existed long enough for the proposed transaction and what changes when the home was purchased recently. Keeping those questions separate prevents a borrower from mistaking an attractive refinance calculation for guaranteed eligibility.
How Soon Can You Refinance a Conventional Mortgage After Buying?
A conventional rate-and-term or limited cash-out refinance may sometimes be available relatively soon after purchase, depending on the mortgage, investor requirements, lender underwriting, title ownership, and complete transaction. Fannie Mae’s current limited cash-out guidance allows a new first mortgage to pay off an existing first mortgage and does not impose the same general 12-month existing-first-mortgage seasoning requirement that appears in its cash-out refinance rules. The lender still has to determine that the transaction satisfies the applicable eligibility and underwriting requirements. Fannie Mae limited cash-out refinance requirements
That does not mean every lender will refinance a mortgage immediately after purchase. Individual lenders can impose their own minimum time-on-title, payment-history, or loan-seasoning requirements, and the company that originated the purchase mortgage may have its own restrictions or incentives affecting an extremely fast refinance. The homeowner therefore needs an answer from the lender offering the proposed refinance rather than relying entirely on a general conventional-loan rule.
There is also a practical problem with refinancing almost immediately. The costs of the purchase mortgage were only recently paid, so replacing that mortgage creates another financial transaction before the first set of costs has had much time to be recovered. Even when the new loan is permitted, the borrower should calculate how much the rate or payment needs to improve before two mortgage closings within a short period become worthwhile.
Conventional Rate-and-Term and Cash-Out Refinancing Are Different
The distinction between a rate-and-term style refinance and a cash-out refinance is central to this question. A homeowner trying to replace the existing mortgage with better pricing is primarily restructuring the same housing debt, while a cash-out borrower is increasing or restructuring secured debt in order to remove equity from the property. The additional leverage is one reason cash-out transactions can have stricter seasoning and ownership requirements.
Fannie Mae’s current cash-out guidance generally requires an existing first mortgage being paid off through the cash-out refinance to be at least 12 months old, measured from the existing loan’s note date to the new loan’s note date. The same guidance generally requires at least one borrower to have been on title for at least six months before disbursement, while providing specified exceptions for circumstances such as inheritance, legal awards of property, and qualifying delayed-financing transactions. Current conventional cash-out seasoning and ownership rules
This means the answer to “Can I refinance six months after buying?” can change depending on what the borrower means by refinance. Replacing a conventional first mortgage without meaningful equity extraction can be evaluated differently from asking a lender to turn newly accumulated or recently purchased equity into cash. Borrowers should describe the purpose of the transaction before asking the lender for a waiting-period answer.
Refinance Timing by Mortgage Type
The major refinance categories do not all use the same clock, which is why a single six-month rule can mislead homeowners. Some transactions focus on the age of the mortgage, some require a particular payment history, some include ownership or occupancy conditions, and lenders can still apply additional requirements. The table below should therefore be used as a starting framework before confirming the exact transaction with the proposed lender.
| Refinance Type | Important Timing Consideration | What to Confirm |
|---|---|---|
| Conventional limited cash-out / rate-and-term | Can potentially be available without the general 12-month existing-first-mortgage rule used for Fannie Mae cash-out transactions. | Lender seasoning, ownership, underwriting, appraisal, and investor requirements. |
| Conventional cash-out | Fannie Mae generally requires an existing first mortgage being paid off through the transaction to be at least 12 months old, with specified exceptions. | Existing loan age, time on title, LTV, equity, and whether an exception applies. |
| FHA Streamline | Seasoning includes payment-count and elapsed-time requirements on the FHA mortgage being refinanced. | Current FHA insurance, payment history, seasoning, and net tangible benefit. |
| FHA cash-out | Current FHA policy generally requires the property to have been owned and occupied as the borrower’s principal residence for the preceding 12 months, subject to stated exceptions. | Occupancy history, payment history, equity, appraisal, and FHA underwriting. |
| VA refinance of an existing VA loan | Applicable VA seasoning rules use both elapsed time and consecutive monthly payments. | Whether the current loan is VA-guaranteed, payment history, transaction type, and benefit requirements. |
| USDA refinance | Current USDA guidance includes minimum seasoning and payment-history requirements for refinance options. | Existing USDA loan, seasoning, payment history, interest-rate requirement, and chosen refinance route. |
The table also explains why a homeowner should not tell a lender only, “I bought the house five months ago.” The lender also needs to know what mortgage currently exists and what the homeowner wants the new mortgage to accomplish. Those additional facts determine which timing framework actually matters.
How Soon Can You Do an FHA Streamline Refinance?
An FHA Streamline Refinance applies to an existing FHA-insured mortgage and uses its own seasoning and eligibility framework. HUD’s current consumer guidance explains that the mortgage being refinanced must already be FHA insured, must be current, and the transaction must provide a net tangible benefit to the borrower. The Streamline name refers to the documentation and underwriting process rather than meaning that the homeowner can automatically refinance immediately after purchase. HUD’s FHA Streamline Refinance guidance
FHA seasoning has historically required at least six payments on the FHA-insured mortgage being refinanced, at least six full months since the first payment due date, and at least 210 days since the mortgage being refinanced closed before the relevant case-number stage. Homeowners should confirm the current detailed rule with the lender against the latest version of HUD Handbook 4000.1 because FHA updates and consolidates its policy there. Current FHA Single Family Housing Policy Handbook 4000.1
The calendar should therefore be calculated from the actual mortgage dates rather than translated casually into “about six months.” Closing date, first-payment due date, and payment count can produce different milestones, which means reaching one condition does not necessarily mean the mortgage has reached every condition. A lender experienced with FHA Streamlines should calculate the earliest viable timeline using the actual loan history.
How Soon Can You Get an FHA Cash-Out Refinance?
FHA cash-out refinancing has a different purpose and therefore a different framework from FHA Streamline refinancing. HUD’s FHA Handbook states that cash-out transactions are limited to owner-occupied principal residences and generally require the property securing the cash-out refinance to have been owned and occupied by at least one borrower as a principal residence for the 12 months before case-number assignment, subject to the handbook’s stated exceptions. The policy also contains mortgage-payment-history requirements that need to be satisfied. FHA cash-out refinance ownership and occupancy requirements
This is why a homeowner who purchased a house three months ago should not assume an FHA cash-out refinance is available simply because the property appears to have appreciated. Equity is only one part of the qualification structure, while occupancy history and other FHA requirements still matter. A rapid increase in estimated property value does not erase the program’s timing rules.
The distinction is especially useful for homeowners who say they want to “refinance my FHA mortgage” without describing the goal. Someone seeking a lower rate through an FHA-to-FHA Streamline is asking one question, while someone seeking $50,000 of cash from the property is asking another. The lender needs the purpose before the timing answer can be meaningful.
How Soon Can You Refinance a VA Loan?
VA refinancing of an existing VA-guaranteed mortgage also uses seasoning rules that prevent certain rapid serial refinances. Current VA lender guidance states that applicable VA-to-VA refinancing seasoning involves both elapsed time and a minimum number of consecutive mortgage payments. The VA handbook describes a VA-guaranteed loan as seasoned when the applicable time requirement and six consecutive monthly-payment requirement have been satisfied. VA refinancing loan seasoning requirements
For IRRRL transactions, VA guidance has used a standard requiring at least six consecutive monthly payments and at least 210 days after the first payment due date before the new refinance closes. The program also applies requirements beyond seasoning, including net tangible benefit and other transaction standards, so reaching the calendar milestone does not automatically mean the refinance should or can close. VA IRRRL seasoning guidance
VA borrowers should therefore avoid reducing the rule to “seven months after closing.” The actual first-payment due date and payment history matter, and circumstances such as forbearance can make an apparently simple calendar estimate inaccurate. Ask the VA-approved lender to identify the qualifying date from the actual servicing record.
How Soon Can You Refinance a USDA Mortgage?
USDA refinance transactions also require the existing loan to become sufficiently seasoned before the refinance can proceed. A USDA procedure update issued in 2025 clarified that refinance options under the guaranteed program require the existing loan to have closed at least 180 days before submission to the agency, while payment-history requirements also apply. The applicable streamline, streamlined-assist, or other refinance route can add its own requirements. Current USDA refinance seasoning guidance
This is a useful example of why older online articles can become unreliable. USDA refinance rules have changed over time, so an article repeating an older 12-month rule for every USDA refinance can miss later policy updates. Borrowers should verify the current handbook and lender interpretation rather than using an old mortgage blog as the final eligibility source.
The lender should also confirm whether the homeowner’s current mortgage qualifies for the particular USDA refinance being discussed. Program names such as streamlined and streamlined-assist describe specific transaction structures rather than interchangeable shortcuts. The current mortgage, payment record, proposed rate, and other program conditions still need to fit.
Can You Refinance One Month After Buying a House?
In a narrow conventional rate-and-term scenario, the rules may not create the same universal one-year wait that applies to certain cash-out transactions. That does not mean refinancing one month after purchase is common or easy, because the new lender still has to underwrite the borrower, property, mortgage payoff, title, and complete refinance. The lender or investor may also have its own minimum seasoning policy even when the broader mortgage program does not impose the waiting period the borrower expected.
The economics are usually the bigger concern. The homeowner has just paid purchase-related mortgage costs and may now face appraisal, title, origination, recording, prepaid items, and other costs associated with another transaction. A rate decline needs to be meaningful enough to overcome the fact that the homeowner is effectively paying for mortgage financing twice within a very short period.
There can still be circumstances where an exceptionally rapid refinance makes sense. A borrower may have used temporary financing to complete a purchase, or market conditions may have changed sharply after the original rate was locked. The transaction should be evaluated on its actual savings rather than rejected simply because the purchase was recent.
Can You Refinance Three Months After Buying?
Three months gives the homeowner more payment history and more time to evaluate the mortgage, but it still does not create universal refinance eligibility. Conventional rate-and-term financing can have different timing possibilities from FHA, VA, USDA, and cash-out structures. The lender needs to identify the applicable mortgage category before a three-month answer is useful.
At this stage, the borrower also has better information about actual homeownership costs. Property taxes, insurance, HOA charges, utilities, repairs, and the true monthly mortgage cash flow have started replacing the estimates used before closing. This can change the refinance objective because a homeowner who originally wanted a shorter term may discover that monthly flexibility is more valuable after seeing the complete housing budget.
A three-month refinance still deserves a strict break-even calculation. If the new loan saves $200 per month but costs $5,000, the simplified break-even period is 25 months before accounting for differences in principal repayment. Someone expecting another move within two years may therefore find that an eligible refinance remains economically weak.
Can You Refinance Six Months After Buying?
Six months is an important milestone for several refinance rules, but it should not be treated as a universal green light. Some conventional cash-out ownership rules reference six months on title while the existing first mortgage can still be subject to a longer seasoning requirement, and FHA or VA transactions can involve payment counts plus elapsed-time requirements. Reaching six months after the purchase date alone does not prove that every relevant condition has been met.
This is also the point where borrowers can become overly confident about appreciation. A home purchased six months ago may appear to be worth substantially more based on nearby listings or automated estimates, but a lender can use its own required valuation process when underwriting the refinance. The refinance amount therefore needs to be based on a defensible property value rather than the homeowner’s preferred estimate.
Financially, six months can provide enough history to make the original mortgage easier to evaluate. You now know how the payment fits the household budget, whether the chosen term feels appropriate, and whether the original rate is genuinely far above current offers. Those practical observations can be more useful than refinancing simply because six months have passed.
Can You Refinance After Owning the House for One Year?
One year can open additional refinance possibilities that were unavailable during the first months of ownership. For example, Fannie Mae’s general conventional cash-out requirement for an existing first mortgage being paid off through the transaction uses a 12-month loan-age requirement, subject to its listed exceptions. FHA cash-out rules also generally look for a 12-month ownership and principal-residence occupancy history under the standard policy. Conventional cash-out refinance eligibility after 12 months
That still does not mean a homeowner automatically qualifies on the first anniversary. Credit, income, employment, debts, property value, LTV, mortgage-payment history, and lender requirements remain part of the underwriting process. The anniversary removes one potential timing obstacle without eliminating the rest of the mortgage application.
A year of ownership can also improve the quality of the financial decision. The homeowner has experienced a full cycle of property expenses and can compare the current mortgage against alternatives using real household data rather than purchase-stage estimates. If the refinance is being considered for cash-out purposes, the borrower can also make a more informed decision about how much equity should remain in the property.
Why Did Your Lender Tell You to Wait Six Months?
The lender may be applying a rule specific to the loan program, the investor that will own the refinance mortgage, or the lender’s own internal underwriting policy. A mortgage company can impose requirements that are more conservative than the broad minimum rule a borrower found online. The lender may also be referring to a payment-history requirement rather than a simple ownership requirement.
Another possibility is that the borrower and lender are discussing different refinance types. A homeowner may ask about refinancing generally while the loan officer assumes the homeowner wants cash out, or the borrower may have an FHA or VA mortgage whose program-specific seasoning matters. Asking the lender to identify the exact rule usually resolves the apparent contradiction.
A useful follow-up question is, “What date or event are you waiting for?” Ask whether the issue is the note date, first-payment due date, number of mortgage payments, property ownership, occupancy, or the lender’s own seasoning policy. A specific answer makes it much easier to determine whether waiting is mandatory or merely the lender’s preferred structure.
Why Did Another Lender Say You Can Refinance Immediately?
Different lenders can legitimately produce different answers because they may sell loans to different investors, apply different overlays, or interpret the proposed transaction differently. One lender may have a product capable of refinancing the mortgage relatively quickly, while another requires more seasoning before it will originate or purchase the same general type of loan. The difference does not automatically mean one lender is wrong.
The loan structures may also be different even when both companies use the word refinance. One quote might be a limited cash-out conventional transaction while another is being priced as cash-out, or one lender may be proposing a different loan program entirely. Compare the transaction descriptions before comparing the waiting periods.
This is another reason the Loan Estimate becomes important once formal applications are underway. Compare interest rate, APR, origination charges, lender credits, mortgage insurance where applicable, cash to close, and the complete payment rather than selecting the lender solely because it promises the earliest possible closing. CFPB guidance for comparing Loan Estimates
Can You Refinance Immediately After Buying a House With Cash?
A cash buyer faces a different situation because there may be no purchase mortgage to refinance. The homeowner may instead want to place a mortgage on a recently purchased free-and-clear property and recover part of the cash used for the acquisition. Conventional guidelines can provide a delayed-financing exception for qualifying recent cash purchases when the transaction satisfies the detailed requirements.
Fannie Mae’s delayed-financing rules allow certain borrowers who purchased the property within the previous six months to complete a transaction without waiting for the ordinary cash-out framework that would otherwise create additional timing restrictions. The exception has detailed documentation and transaction requirements, so it should not be interpreted as permission to buy any property in cash and automatically borrow against it the following week. Fannie Mae delayed-financing exception requirements
This strategy is particularly relevant in competitive property markets where a buyer deliberately uses cash to strengthen the purchase offer and intends to restore some liquidity afterward. The homeowner should discuss delayed financing with a lender before the purchase when possible because the source of the original purchase funds and transaction documentation can matter. Planning before closing is much easier than reconstructing evidence after the property has already been acquired.
Does Your Original Lender Care If You Refinance Quickly?
The mortgage contract controls whether the borrower can pay off the loan, while applicable prepayment provisions determine whether leaving early creates an additional charge. Many ordinary consumer mortgages do not contain the kind of early-payoff penalty borrowers fear, but that should be confirmed from the actual Note and closing documents rather than assumed. If the loan does contain an applicable charge, the penalty belongs in the refinance economics from the beginning.
The original lender may also have business reasons to dislike extremely rapid payoff because the loan was expected to remain outstanding long enough to generate value. Those business considerations do not automatically create a contractual prohibition that does not otherwise exist, but they can influence lender policies, pricing, or relationships. The homeowner’s responsibility is to follow the mortgage agreement and the requirements of the new financing.
If an early-payoff provision exists, use the mortgage prepayment penalty guide before assuming the lower refinance rate tells the complete story. Add the old-loan exit cost to the new-loan closing costs and recalculate break-even. A cheap new mortgage can become expensive when leaving the old one costs thousands of dollars.
The Purchase Mortgage Costs Have Not Disappeared
One of the biggest mistakes in rapid refinancing is pretending that the original mortgage closing happened too recently to matter. Origination charges, discount points, title-related expenses, appraisal costs, and other amounts paid during the purchase remain part of the household’s financial history even if a new refinance opportunity appears immediately afterward. Replacing the loan does not refund those earlier costs unless a specific transaction credit or arrangement actually does so.
Those earlier costs are largely sunk once they have been paid, so they should not automatically prevent the homeowner from accepting a much better mortgage. Refusing a financially superior refinance does not bring the purchase-closing expenses back. The previous costs still matter as evidence of how much the household is spending to obtain and replace financing within a short period.
The new refinance therefore needs to stand on its own from today forward while still being viewed in the context of the recent transaction history. A homeowner who repeatedly pays mortgage costs every few months can consume much of the benefit created by slightly lower rates. The guide to how often you can refinance your mortgage covers that repeated-refinance problem separately.
Calculate the New Refinance Break-Even Point
The simple starting calculation is:
New refinance costs ÷ monthly savings = simple break-even months
Suppose the new refinance costs $4,800 and reduces the comparable mortgage payment by $300 per month. The simplified break-even period is 16 months, which means the borrower needs roughly 16 months of $300 monthly savings to recover the $4,800 transaction cost. That calculation is more informative than saying that rates have fallen by a certain percentage.
A rapid refinance deserves an additional question: how long do you realistically expect to keep this new mortgage? If another move, sale, or refinance is reasonably likely before month 16, the transaction may never move beyond its simple break-even point. If the homeowner expects to remain for seven years, the mortgage has much more time to create value after the cost is recovered.
The Break-Even Formula Is Only the First Test
Monthly payment savings can be created by changing the amortization period as well as by lowering the rate. A new 30-year mortgage replacing a recently originated 30-year mortgage will not create a dramatic term reset when only a few months have passed, but the effect becomes more important as more time passes before refinancing. The borrower should still compare the structure rather than assuming every lower payment represents interest savings.
Compare the projected loan balance after the same future period under both mortgages. If the new mortgage produces a lower payment but leaves a significantly higher balance five years later, part of the apparent savings came from slower principal repayment. That may be acceptable when monthly flexibility is the objective, but it should be identified correctly.
Points and lender credits can also change the comparison. Paying points can make a refinance rate look attractive while increasing the amount that needs to be recovered, while lender credits can reduce upfront cost in exchange for different pricing. Use the expected holding period to decide which structure fits instead of chasing the lowest advertised rate.
How Much Lower Should the New Rate Be?
There is no universal rule requiring the new rate to be one percentage point lower before a refinance makes sense. Mortgage balance, closing costs, points, remaining term, loan type, mortgage insurance, and expected holding period all affect the answer. A relatively small rate reduction on a large mortgage can produce more dollar savings than a much larger percentage reduction on a small mortgage.
This is particularly important shortly after purchase because the mortgage balance is usually close to its original size. A 0.50 percentage-point reduction on a large recently originated mortgage can therefore have a substantial effect, while the same reduction on a much smaller mature mortgage would produce less dollar savings. The rate change needs to be translated into an actual payment and interest comparison.
The decision should also consider how the rate was obtained. If the new lender requires several discount points to achieve the attractive rate, the borrower may need years to recover the upfront expense. A slightly higher rate with much lower closing costs can be stronger for someone who expects another move or refinance relatively soon.
What If Rates Fell Right After You Closed?
This is frustrating because the borrower can feel as though the original mortgage was immediately a mistake. Mortgage rates move continuously, however, and a purchase often needs to close on a specific date, which means the borrower cannot always wait for the perfect market environment. The original decision should be judged based on the financing available when the purchase needed to close.
Once the home is yours, the new decision begins from the mortgage you have today. If another lender can legitimately replace it with materially better financing and the transaction satisfies applicable seasoning requirements, compare the new costs with the future savings. Regret about the original rate should not cause the borrower either to refinance impulsively or refuse a better opportunity.
A rapid rate decline is one of the situations where refinancing relatively soon can make financial sense. The larger and more durable the improvement, the easier it becomes for the new mortgage to overcome another set of transaction costs. The calculation still needs to be completed rather than assuming that a lower market rate guarantees savings.
What If Your Credit Score Improved After Buying?
A stronger credit profile can potentially improve mortgage pricing, depending on the loan program and complete borrower profile. Someone who purchased while carrying high credit-card balances may pay those balances down after closing and later qualify for a different refinance offer. The change can be meaningful when the original loan pricing was substantially affected by the borrower’s credit characteristics.
A credit-score increase alone does not mean refinancing should happen immediately. The rate improvement actually offered needs to be compared against closing costs, and the mortgage still needs to satisfy any applicable seasoning requirements. A lender’s advertised best rate is irrelevant unless the borrower qualifies for that pricing.
Avoid deliberately taking on unnecessary credit activity immediately after closing merely to manipulate a refinance score. The homeowner’s wider financial position matters more than a single score number. Stable income, manageable debts, adequate reserves, and a refinance that produces a real financial improvement create a much stronger case.
Can Refinancing Remove Mortgage Insurance Soon After Purchase?
Potentially, but the answer depends heavily on the current mortgage and the replacement financing. A homeowner whose property value rises or who made a relatively small down payment may become interested in refinancing to change the mortgage-insurance structure. The lender still needs a qualifying property value and a transaction that fits the applicable program.
Rapid appreciation should be treated carefully because an online estimate is not necessarily the value the refinance lender will use. A new appraisal or accepted valuation method can produce a different result from the homeowner’s expectations. If the refinance depends entirely on reaching a particular LTV threshold, understand what happens if the valuation comes in lower.
Mortgage insurance savings should be included in the monthly comparison rather than looking only at principal and interest. A refinance can be worthwhile even when the note-rate change is relatively modest if another significant recurring mortgage cost disappears. The same transaction can be weak if expensive closing costs are required to obtain that reduction.
Can You Refinance Soon After Buying to Change From an ARM to Fixed?
Potentially, subject to the timing and qualification rules applicable to the current mortgage and proposed refinance. A homeowner may choose an adjustable-rate mortgage during the purchase because its initial pricing is attractive and later decide that long-term payment certainty matters more. The refinance should be evaluated against the actual ARM adjustment schedule rather than against a vague fear that the payment might someday rise.
If the ARM remains in its initial fixed period for several years, paying significant refinance costs immediately for protection that is not yet needed may have limited value. If the borrower expects to hold the property well beyond the initial period and fixed-rate pricing has become attractive, refinancing can provide a clearer long-term payment structure. The expected ownership period remains central to the choice.
Read the ARM terms before refinancing because caps, index, margin, first adjustment date, and subsequent adjustment rules determine the actual future exposure. A fixed mortgage can provide certainty, but certainty has a price when the replacement loan carries closing costs or a higher current payment. Compare the contracts rather than the product names alone.
Can You Refinance Soon After Buying to Get Cash?
This is where the answer becomes much more restrictive because equity extraction is not treated the same way as merely replacing the existing mortgage. Conventional cash-out, FHA cash-out, and other loan programs can impose ownership, occupancy, and seasoning requirements that prevent a newly purchased property from immediately becoming a source of large cash withdrawals. The borrower should identify the intended cash amount before asking how soon refinancing is possible.
Even after the required time passes, available equity determines how much cash can realistically be obtained. A homeowner who purchased with a high LTV may have little usable equity after only one year unless substantial principal has been paid or the property value has risen. Closing costs can also consume part of the apparent available amount.
Cash-out refinancing should therefore be separated from a rate-reduction decision. If the homeowner needs a relatively small amount of money and has an excellent first mortgage, another borrowing structure may deserve consideration rather than replacing the entire mortgage. The cost of repricing a large first-mortgage balance can exceed the benefit of obtaining a much smaller amount of cash.
What If the House Has Increased in Value Quickly?
A rapid increase in local property values can improve the homeowner’s apparent equity position, but it does not automatically remove seasoning requirements. The applicable loan program can still require a minimum mortgage age, ownership period, or payment history before the transaction is eligible. Value and seasoning answer different questions.
The lender also determines what valuation is acceptable for underwriting. A homeowner may believe the property increased from $400,000 to $475,000 because several nearby homes sold at higher prices, while the refinance appraisal may reach a different conclusion after considering condition, size, location, and comparable sales. A refinance plan that requires the absolute highest plausible valuation has very little margin for error.
This is particularly relevant for cash-out borrowers because a lower value can directly reduce available proceeds. The homeowner should calculate the transaction at a conservative value before relying on the maximum possible equity withdrawal. A plan that still works under a slightly lower appraisal is much more resilient.
What If the House Has Lost Value Since You Bought It?
A decline in value can make refinancing more difficult even when the borrower has perfect payment history. The mortgage balance may now represent a larger percentage of the property’s value, which can restrict available programs, change mortgage-insurance treatment, or prevent the desired cash-out structure. Seasoning alone does not solve an LTV problem.
Suppose the borrower purchased the home for $500,000 using a $450,000 mortgage and the property is now valued at $465,000. The outstanding balance can remain close to its original amount after a short ownership period, leaving very little equity cushion. A lower interest rate may be available in the market while the property itself prevents a straightforward refinance.
Government-backed or specialized refinance options can sometimes address situations that ordinary conventional financing cannot, but eligibility depends on the mortgage and current program rules. Ask the lender which options actually fit rather than repeatedly applying for standard products that require more equity. A lower property value changes the financing architecture rather than simply delaying the closing.
Do You Need a New Appraisal When Refinancing Soon After Purchase?
Possibly, depending on the refinance program, lender, automated underwriting result, and property. The purchase appraisal or valuation does not automatically remain usable for every subsequent refinance because the new transaction has its own underwriting requirements. Some programs can allow alternative valuation treatment under qualifying circumstances, while others require a new appraisal.
A new appraisal can be especially important when the borrower claims that the property value changed materially within only a few months. The lender needs credible support for the value on which the new LTV will be based. Improvements made after purchase can matter, but the dollar amount spent on renovations does not guarantee an equal increase in appraised value.
Build some valuation uncertainty into the refinance calculation. If the transaction is worthwhile only when the property appraises at exactly $600,000, ask what happens at $575,000 or $550,000. That sensitivity test can prevent an appraisal surprise from turning a promising refinance into a rushed financial decision.
Can You Refinance Before Making Your First Mortgage Payment?
This is possible only in limited transaction circumstances and should never be assumed from a general refinance article. A lender considering such an early transaction will examine the applicable mortgage program, investor requirements, loan age, ownership, and complete purpose of the refinance. Many common streamline and government-backed refinance structures explicitly need payment history before they can be used.
Even when some conventional structure technically allows extremely early refinancing, the economics deserve exceptional scrutiny. The original purchase loan has barely begun, and another transaction can require significant costs immediately after closing. A small improvement in rate is unlikely to justify repeatedly paying mortgage-transaction expenses within weeks.
If the original mortgage contains a serious error or an urgent financing problem, speak with the lender and appropriate professionals rather than assuming a refinance is the only correction. Extremely early replacement financing is unusual enough that the exact circumstances matter more than a generic waiting-period answer. A lender should be able to explain the rule supporting the proposed transaction.
Do You Skip a Mortgage Payment When Refinancing Soon After Buying?
A refinance can create a calendar gap that makes it appear as though one scheduled monthly payment has disappeared, but mortgage interest has not simply been forgiven. The old loan is paid off through the refinance, while the new loan has its own interest accrual and first-payment schedule. The timing of closing determines how those obligations appear on the calendar.
This can be particularly confusing when the borrower refinances only a few months after the original purchase because the mortgage schedule has barely become familiar. The homeowner may see no ordinary mortgage payment due during a particular month and mistakenly count that amount as refinance savings. The guide to whether you skip a mortgage payment when refinancing explains why the apparent gap should not be treated as free money.
Keep enough cash available for both the refinance closing and the upcoming first payment on the new mortgage. Escrow refunds and timing differences can make the transaction cash flow look unusual for several weeks. Temporary account movements should not be confused with permanent financial savings.
Should You Refinance After Only Six Payments?
Six payments can be meaningful because some mortgage programs use payment history as part of their seasoning framework. Reaching six payments still does not tell you whether the transaction makes financial sense, because closing costs, rate reduction, remaining term, and expected holding period remain separate questions. Eligibility is the beginning of the calculation rather than the conclusion.
A homeowner should calculate what changed during those six months. Perhaps mortgage rates fell dramatically, the borrower’s credit improved, or an expensive temporary financing structure can now be replaced. Those changes can create a strong reason to refinance.
If nothing important changed, the fact that six payments have been made is not itself a financial benefit. Refinancing because a calendar milestone has arrived can create another set of closing costs without solving a meaningful problem. A replacement mortgage should earn its place rather than exist merely because it became available.
Should You Refinance After One Year?
One year is a natural review point because additional cash-out possibilities may become available and the borrower has enough homeownership history to understand the mortgage more accurately. The household has experienced property taxes, insurance, maintenance, utility costs, and a full year of mortgage payments, which makes future affordability easier to judge. The homeowner can also compare actual property-market changes with the assumptions used during purchase.
The new mortgage should still improve something meaningful. It may reduce the rate, remove an unwanted mortgage feature, lower mortgage insurance, shorten the repayment period, improve monthly flexibility, or provide appropriately structured access to equity. If none of those outcomes matters, refinancing because the loan has reached its first birthday has no special financial value.
This is also a good time to review how much principal has actually been repaid. Early in a long amortization schedule, a significant portion of payments can still be interest, which means the mortgage balance may not have declined as dramatically as expected. The equity calculation should use the current payoff and current property value rather than the original loan amount.
When Refinancing Soon After Purchase Has a Stronger Case
A sharp and durable decline in available mortgage rates creates one of the strongest arguments for refinancing relatively quickly. The larger the mortgage balance, the more dollar impact a meaningful rate reduction can have, and newly originated mortgages generally still have large outstanding balances. Low transaction costs can make the case even stronger because the break-even period becomes shorter.
The case can also be strong when the purchase financing was intentionally temporary. A buyer may have accepted a higher-cost mortgage, bridge structure, or other short-term solution because closing certainty mattered more than long-term pricing during the purchase. Replacing intentionally temporary financing is different from repeatedly chasing tiny market movements.
Another strong case occurs when the new mortgage fixes an important structural problem. Moving away from an unsuitable adjustable-rate structure, improving mortgage-insurance treatment, or replacing a loan that no longer fits the household can provide value beyond the headline rate reduction. The objective should be clear before the refinance application begins.
When Refinancing Soon After Purchase Is Usually Weak
The case is weak when the rate improvement is small and another substantial set of closing costs is required. A homeowner who spends $7,000 to reduce the payment by $100 per month faces a simplified break-even period of 70 months, which is nearly six years. If the homeowner expects to move or refinance again before then, the transaction has little opportunity to recover its cost.
The case also weakens when the payment falls mainly because the new loan is structured over a longer repayment period. Shortly after purchase this term-reset effect may be small, but it can still matter when the new refinance includes cash out or otherwise increases the balance. Compare future debt rather than assuming the lower payment represents pure savings.
A refinance should also be questioned when it leaves the household with very little cash after closing. New homeowners commonly discover repairs, furnishing expenses, maintenance obligations, and other costs that were not obvious during the purchase. Using every available dollar to obtain a slightly lower mortgage rate can reduce financial resilience at exactly the stage when homeownership is still producing surprises.
Refinance Now or Wait for a Better Opportunity?
Waiting preserves the current mortgage and avoids another immediate transaction cost, while refinancing locks in whatever improvement is available today. The correct choice depends on the value of the current offer rather than a prediction that rates definitely will or will not move later. Nobody can know with certainty whether a better refinance will be available six months from now.
One useful approach is calculating the break-even period on today’s refinance and then asking how long you confidently expect to keep the replacement mortgage. A 12-month break-even can be compelling for a homeowner expecting to remain for seven years, while a 48-month break-even may be less attractive when a relocation within three years is plausible. Expected holding period turns an abstract rate decision into a household decision.
Another useful approach is comparing multiple pricing structures today. One lender may offer a very low rate with expensive points, while another offers a slightly higher rate with minimal upfront cost. The lower-cost structure can be especially attractive when refinancing soon after purchase because it reduces the risk of paying large transaction expenses twice within a short period.
What Documents Should You Prepare for an Early Refinance?
Prepare the current mortgage statement and enough information for the lender to identify the original closing date, first-payment due date, payment history, and current payoff. The exact dates are important when the proposed refinance has seasoning requirements. A vague statement that the mortgage is “about six months old” is less useful than the actual note and payment history.
Income, employment, assets, debts, insurance, and other underwriting information may also need to be updated even though the original mortgage application was completed recently. The new lender cannot simply assume that the borrower’s situation remains identical because another lender approved the home purchase. Refinancing is a new credit transaction with its own underwriting file.
If the refinance depends on recent property improvements, retain contracts, invoices, permits where applicable, and evidence showing what work was completed. Those records do not guarantee a particular appraisal result, but they can help document changes to the property. A lender or appraiser can then evaluate the property using the documentation appropriate to the transaction.
Questions to Ask Before Refinancing a Recently Purchased Home
Ask the lender what specific waiting rule applies to your transaction and what event controls the date. Determine whether the lender is measuring from the original note date, first-payment due date, number of payments, purchase date, title date, occupancy period, or another milestone. This prevents a vague six-month answer from causing unnecessary confusion.
Ask whether the refinance is being classified as rate-and-term, limited cash-out, cash-out, FHA Streamline, VA IRRRL, or another specific transaction. Then ask whether the lender applies any additional seasoning beyond the underlying loan-program requirement. Knowing the classification allows you to compare two lenders that may otherwise appear to be giving contradictory answers.
Finally, request the complete pricing rather than only the new rate. Compare closing costs, points, lender credits, mortgage insurance, payment, amortization, cash to close, and projected mortgage balance. The earliest lender willing to refinance is valuable only if the mortgage it offers is also financially competitive.
The Three Tests for Refinancing Soon After Buying
1. Has the Mortgage Become Eligible?
Determine which mortgage and refinance rules apply before performing a detailed savings analysis. A conventional limited cash-out transaction, Fannie Mae cash-out refinance, FHA Streamline, FHA cash-out transaction, VA refinance, and USDA refinance can each use different timing requirements. Lender overlays can create an additional restriction even after the underlying program requirement is met.
Use the actual mortgage dates rather than rounded calendar estimates. Six months of ownership does not necessarily mean six required mortgage payments have occurred, while 210 elapsed days may not mean every payment-history condition has been satisfied. The lender should be able to identify the date on which the transaction becomes eligible under its proposed structure.
2. Does the New Mortgage Recover Its Costs?
Calculate the entire new transaction cost and divide it by the comparable monthly savings as a first-pass break-even estimate. Include points and other costs that genuinely exist because of the refinance rather than pretending a low advertised rate arrived for free. Then compare the break-even period with the amount of time you realistically expect to keep the replacement mortgage.
Follow the simple calculation with a future-balance comparison. A mortgage that lowers the monthly payment but leaves the borrower owing more several years later may be providing cash-flow relief rather than pure financing savings. That can still be valuable when the household needs flexibility, but the benefit should be described accurately.
3. Is Refinancing Now Better Than Keeping the Mortgage?
The current mortgage is the alternative against which the refinance needs to compete. Compare its payment, rate, remaining term, mortgage insurance, flexibility, and future balance with the proposed replacement loan. A new mortgage should improve enough of those characteristics to justify another closing.
Do not compare today’s refinance against the mortgage rate you wish you had received during the purchase. That mortgage never existed. The choice available today is keeping the actual loan already in place or replacing it with the actual refinance being offered now.
Frequently Asked Questions About Refinancing After Buying a House
How soon after buying a house can you refinance?
There is no single waiting period that applies to every mortgage refinance. Conventional rate-and-term, conventional cash-out, FHA, VA, and USDA transactions can apply different seasoning, ownership, occupancy, and payment-history requirements. The lender also may apply additional requirements, so the answer depends on both the mortgage you have and the refinance you want.
Can I refinance three months after buying a house?
Some conventional rate-and-term structures may potentially be available relatively soon after purchase, but three months does not satisfy every refinance program’s requirements. Government-backed streamline loans and cash-out transactions can use different seasoning or ownership rules, while individual lenders may impose additional waiting periods. Even when technically available, compare closing costs and the expected break-even period before refinancing so soon after the purchase.
Can I refinance six months after buying a house?
Six months can be an important milestone for some refinance transactions, but it is not a universal eligibility date. Certain programs use additional payment-count, loan-age, ownership, occupancy, or elapsed-time requirements that can extend beyond six months. Ask the proposed lender which exact requirement controls your refinance before relying on the purchase anniversary alone.
Can I refinance after owning my house for one year?
One year of ownership can satisfy important timing requirements for some transactions, including the general existing-first-mortgage seasoning requirement used by Fannie Mae for many cash-out refinances and the standard FHA cash-out occupancy period. Approval still depends on the borrower, property, equity, payment history, lender, and complete loan program. Reaching one year therefore removes a potential timing barrier without guaranteeing that the refinance qualifies or makes financial sense.
Why do some lenders make you wait six months to refinance?
The lender may be applying a program seasoning requirement, investor rule, payment-history requirement, ownership condition, or its own underwriting overlay. Different refinance types can also produce different answers even for the same property. Ask the lender to identify the exact rule and the specific date or event that needs to occur before the mortgage becomes eligible.
How soon can I cash-out refinance after buying a house?
Cash-out refinances can have stricter waiting requirements than ordinary rate-and-term refinances. Fannie Mae generally requires an existing first mortgage being paid off through a cash-out refinance to be at least 12 months old, subject to specified exceptions, while FHA cash-out has its own ownership and occupancy requirements. Other loan programs and lenders can apply different rules, so confirm the transaction-specific requirement before depending on recently acquired equity.
Can I refinance immediately if I bought the house with cash?
A qualifying recent cash purchase may potentially use a delayed-financing exception under certain conventional guidelines. The exception contains detailed requirements concerning the purchase transaction, source of funds, ownership, and refinance documentation, so it is not automatic. Discuss delayed financing with the lender as early as possible when the strategy is part of the original purchase plan.
Should I refinance if rates dropped right after I bought the house?
A rapid rate decline can create a strong refinance opportunity when the mortgage is eligible and the savings are large enough to recover the new closing costs within the period you expect to keep the replacement mortgage. Calculate the new payment, transaction costs, break-even period, and future mortgage balance rather than relying only on the percentage-point rate reduction. A recent purchase should make you more careful about another set of costs, but it should not automatically prevent a financially superior refinance.
Final Verdict
You may be able to refinance shortly after buying a house, but the purchase date alone does not tell you when the transaction becomes available. The type of refinance matters because conventional rate-and-term, cash-out, FHA, VA, and USDA mortgages can operate under different seasoning, payment-history, ownership, and occupancy rules. A lender can also impose an additional waiting period beyond the minimum rule associated with the underlying program.
Cash-out refinancing deserves particular attention because its timing can be materially different from simply replacing the current mortgage with another loan. Current Fannie Mae policy generally requires the existing first mortgage being paid off in a cash-out transaction to be at least 12 months old, subject to specified exceptions, while FHA cash-out has its own 12-month principal-residence ownership and occupancy standard under the normal rule. Government-backed streamline programs use still different payment and seasoning frameworks.
Eligibility should never become the entire decision. A homeowner who purchased recently may be paying mortgage-related closing costs for the second time within only a few months, which means the replacement mortgage needs to create a meaningful enough improvement to recover those expenses. Calculate the break-even period and compare future loan balances before interpreting a lower monthly payment as automatic savings.
The earliest possible refinance is therefore rarely the most useful target. The better target is the earliest point at which the mortgage is eligible and the replacement loan improves the household’s financial position by enough to justify another transaction. When those two conditions arrive at the same time, refinancing soon after buying can be entirely reasonable rather than evidence that the original mortgage was a mistake.