Estimate Your Cash Flow Before You Refinance Your Mortgage
Before you refinance your mortgage, it’s important to consider your cash flow. Although it’s an important factor, it’s not the only consideration. You’ll also need to consider interest savings and costs. In other words, you need to know how much money you’ll be spending on your mortgage each month.
Calculating your breakeven point
When it comes to refinancing your mortgage, the first step is figuring out your breakeven point, or how long it will take to recoup the cost of the new loan. This amount will depend on a number of factors, including the total closing costs of your refinancing transaction and how much you will save on the new loan.
The total closing costs will vary by lender, but they are typically listed in the “other costs” section. These costs can include ongoing fees, such as insurance and taxes. For a loan with an escrow account, lenders will require you to make a payment to the escrow account for these items. Most lenders follow federal standards when setting up these accounts.
Refinancing your mortgage is an excellent way to save money on interest and other closing costs. However, it’s important to remember that your breakeven point needs to occur relatively soon. This is important because you want to reap the benefits of the new loan for a longer period of time. You should also keep in mind your overall mortgage objective, including any plans for future moves. For example, if you plan to sell your home soon, refinancing your mortgage will be less beneficial than keeping the home in the same price range.
Calculating your breakeven point before you refi your mortgage is a crucial step in the refinancing process. Refinancing can save you a lot of money over the long run if you can lower your monthly payments and lower interest rates. However, if you’re planning to move before the breakeven point, refinancing is probably not the best idea.
Before refinancing your mortgage, you need to determine the breakeven point by comparing the monthly savings with the total costs. Most people who refinance their mortgage aim for a lower monthly payment and a lower interest rate. However, before refinancing, they need to be sure that they’ll stay in their home for long enough to make up for the costs. To calculate your breakeven point, simply divide the total costs of your mortgage by the savings you’ll experience monthly.
You can also calculate your breakeven point by using a refinance calculator. These calculators require a number of factors, including the original mortgage value and private mortgage insurance, and use this value to calculate the new breakeven point. You can even input the number of points you paid for discount to see how these points will affect your breakeven point.
Estimating your cash flow
If you’re looking to refinance your mortgage, you’ll need to figure out how much cash you can afford. This money can help pay off credit card balances, pay for home improvements, or any other need. However, it is also a major financial commitment. Depending on the lender, you may have to incur additional costs in order to refinance the loan.
Luckily, refinancing can be a lifesaver. With lower interest rates than most personal loans, refinancing your mortgage can help you free up extra money each month. Even though it won’t create wealth on its own, the extra money you can save can be used for luxury purchases and vacations, or even invested in a 401k or brokerage account.
If you have tenants, you’ll need to increase your cash flow by bringing your rents up to market rate. This may be difficult in some areas, but in others, it’s possible to increase rents. Even if the property is underperforming, it can be improved to bring it up to market rates. If the location of the property is desirable, it may attract high rents, resulting in a long-term appreciation.
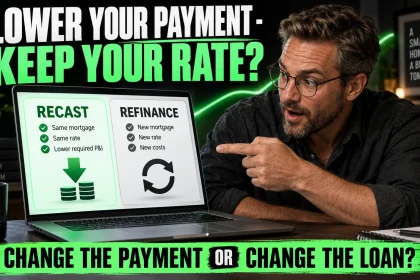
Before you refinance your mortgage, you should compare the costs and benefits of each option. Take a look at the closing costs, interest rate, and monthly payment to make an informed decision. It’s also important to take into account your breakeven point. If you’ll have to stay in your home for at least five years to break even, refinancing may not be a good idea.
The most common reason to refinance your mortgage is the lower rate. But calculating the actual savings is a tricky task. To calculate the real savings, you’ll need to know the difference between your interest savings and your cash flow savings. Once you understand how to break down the savings you’ll get, refinancing can be a great financial move. It can also allow you to make home improvements and pay off high-interest debt.
The second factor to consider is the cash flow of your rental property. You’ll need to know how much rental income you’ll make on the property. In addition to mortgage payments, operating expenses should be calculated. You should also include appreciation of the property in your calculations.
Considering the costs of refinancing your mortgage

When you are looking to refinance your mortgage, it’s important to consider the costs of the transaction. The main reason for refinancing is to get a lower interest rate. This will save you hundreds of dollars over the life of the loan. It will also mean lower monthly payments, which can help your cash flow. Many experts believe that even a reduction of 0.75% is worthwhile.
In addition to interest rate changes, refinancing can also involve closing costs, which can amount to three to six percent of the loan principal. These fees can add up quickly, and they can be difficult to recover. Also, be wary of “no-closing-cost” refinancings. These refinancings may be offered by banks, but the rates may be higher than if you had opted to pay the closing costs.
Another consideration is the interest rate, which will directly affect your monthly payment. Refinancing your mortgage at a lower interest rate will usually result in lower monthly payments. You may be able to secure a lower interest rate by improving your credit score or by taking advantage of changes in market conditions. In addition, lower interest rates will allow you to accumulate equity faster.
The cost of refinancing your mortgage may not seem large at first, but it can add up to thousands of dollars over the life of the loan. The money you will save in interest and principal payments will eventually make up for these fees. However, it can be difficult to break even in five years, so a long-term view is necessary.
When it comes to mortgage refinancing, the most important consideration is whether the savings will outweigh the costs. Although the interest rate is predicted to reach a historic low by 2020, it’s important to remember that the cost of refinancing your mortgage can be significant. For instance, a prepayment penalty may increase the time it takes you to break even on your new loan. If you are planning to sell your home in a few years, you might want to avoid paying this fee.
Lastly, you need to consider the closing costs. Refinancing your mortgage can save you money, and can lower your monthly payment by several hundred dollars. However, you must pay the closing costs associated with the refinancing process, which can range from two percent to five percent of your loan.
Estimate Your Cash Flow Before You Refinance Your Mortgage – Final Thoughts
Before refinancing your mortgage, you need to estimate your cash flow. You should take into account the costs of the loan, as well as the closing costs. Refinancing can help you lower your interest rate, shorten the length of your loan, and access the equity in your home. But it is important to note that refinancing can also add to your monthly payments and hurt your credit score.
First, you should ask your lender about the amount of available equity in your home. Once you know this amount, you can compare it to the percentage the lender will be willing to offer you. If you are not satisfied with their answer, you may want to look for other lenders or reconsider the refinancing process altogether.
Second, you should compare the costs of the various refinancing options. Consider the time it will take for you to recoup the costs of the transaction. This will determine how much you’ll save over time. You can also compare amortization schedules.
Lastly, you should consider the amount of cash you will receive from the refinancing. In many cases, the amount of equity you receive from refinancing your mortgage is much lower than the original loan amount. The difference between the two amounts will result in a lower interest rate.