SoFi currently groups its lending into several main categories: personal loans, private student loans, student-loan refinancing, mortgages, home-equity borrowing, and auto-loan refinancing through a marketplace. The most important distinction is that labels such as “wedding loan,” “travel loan,” or “debt-consolidation loan” are usually uses of the same SoFi personal-loan product, while student, mortgage, home-equity, and auto-refinance options follow different structures and eligibility rules.
SoFi is a U.S.-focused financial-services company, so availability depends on state, borrower eligibility, property rules, school status, loan purpose, and the specific product. Rates and terms change, so this page focuses on what each borrowing category is for and what can materially change the decision.
SoFi Loan Types at a Glance
| Borrowing need | Closest SoFi category | What makes it different |
|---|---|---|
| Debt consolidation, home improvement, wedding, travel, family planning, or another large expense | Personal loan | One unsecured installment-loan category can serve several personal uses. |
| Paying current college or graduate-school costs | Private student loan | Designed for current education costs rather than replacing existing student debt. |
| Replacing existing eligible student loans | Student-loan refinance | Creates a new private loan; refinancing federal debt gives up federal borrower benefits. |
| Buying or refinancing a home | Mortgage | Property-secured financing with mortgage-specific underwriting and closing costs. |
| Borrowing a defined lump sum from home equity | Home equity loan | Closed-end borrowing against equity, separate from the first mortgage in many cases. |
| Drawing home equity over time | HELOC | A revolving line secured by the home, generally with a variable rate. |
| Replacing an existing vehicle loan | Auto refinance marketplace | SoFi presents marketplace quotes from third-party providers rather than a direct SoFi auto loan. |
Borrowing Fit Check
Match your real borrowing goal to the closest loan category, then compare cost, collateral, protections and flexibility before you apply.
1. What are you trying to finance?
Choose the real job first. SoFi uses several marketing labels for personal-loan use cases, but those labels are not always separate loan products.
2. Add the condition that changes the answer
These questions separate look-alike products, especially student refinancing and home-equity borrowing.
3. Compare up to three real offers
Paste numbers from offers you actually received. This comparison area stores what you enter but does not invent lender rates, fees, approvals or rankings.
Compare real nearby candidates
Paste up to four real professionals from your own Google results. Nothing below is invented, ranked, or prefilled.
Independent educational experience. Not affiliated with or endorsed by SoFi. It does not provide rates, underwriting, approval odds, legal advice or individualized financial advice. Product availability and terms can change; verify current details directly with the lender.
1. SoFi Personal Loans Cover Several Different Uses
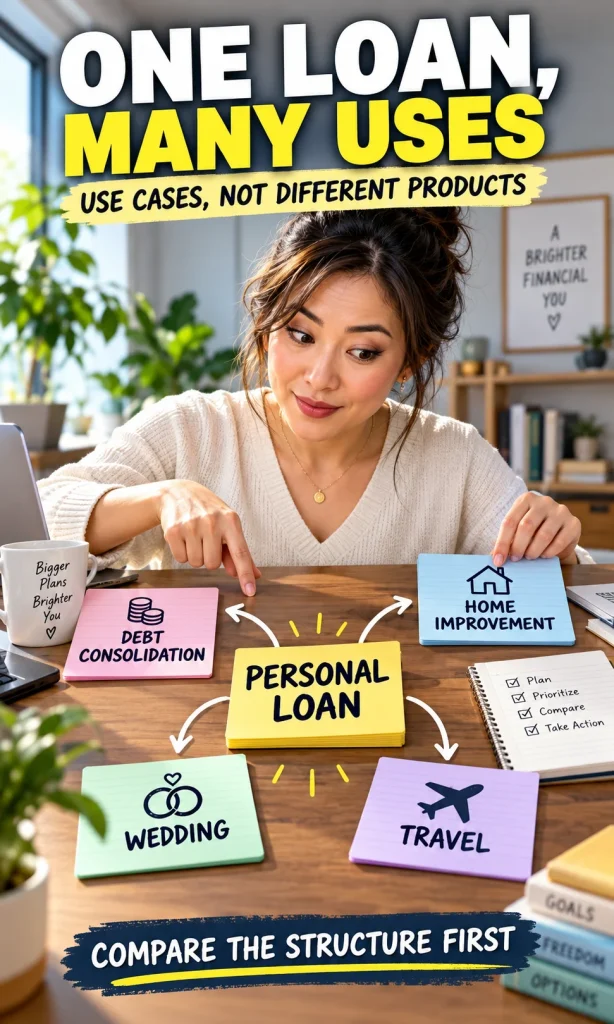
A SoFi personal loan is an unsecured installment loan, which means it is generally not secured by your home or car. You receive a lump sum and repay it over a set term, so the core product is different from a credit card or revolving home-equity line.
The confusing part is the naming. SoFi may describe home-improvement loans, credit-card-consolidation loans, family-planning loans, travel loans, and wedding loans, but these are normally use cases for its personal-loan product rather than five completely different lending systems. That distinction matters because the underwriting, repayment structure, and cost comparison should be evaluated as a personal loan.
- Debt consolidation: can combine eligible high-interest debts into one installment payment, but the new APR and total repayment cost still determine whether consolidation saves money.
- Home improvement: can fund renovations without putting the home up as collateral, although homeowners should compare the cost against home-equity borrowing.
- Large personal expenses: may include medical, family-planning, wedding, relocation, or travel costs where an installment loan fits better than revolving credit.
SoFi currently offers personal-loan structures in which an origination-fee option can affect the APR and the amount of cash actually received. That makes APR and net proceeds more useful comparison numbers than a headline interest rate alone.
2. Private Student Loans Are for Current Education Costs
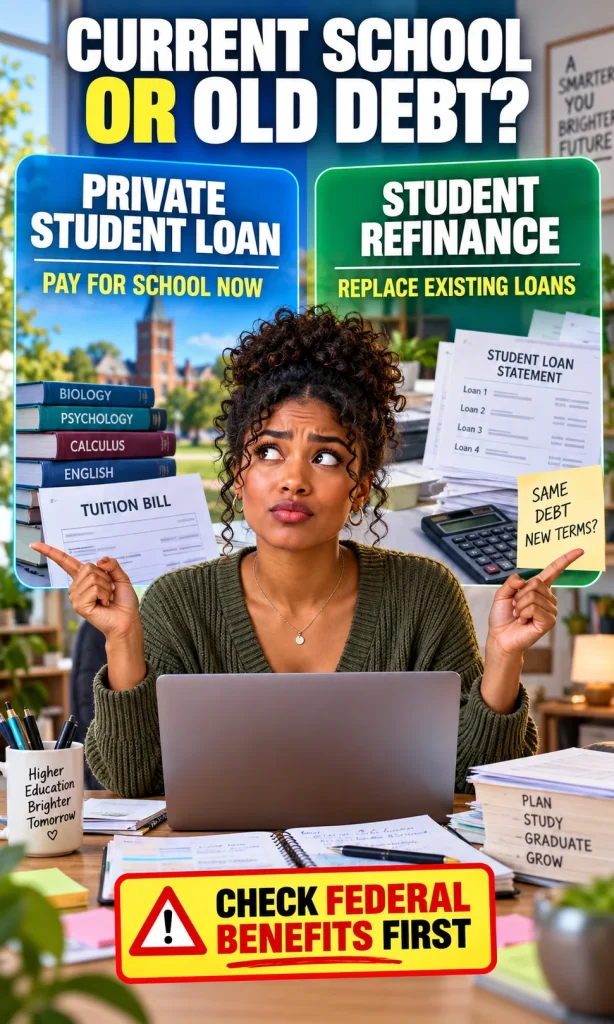
Private student loans serve a different job from student-loan refinancing. They are used to fund eligible current education expenses, while refinancing replaces education debt you already have.
SoFi lists private student-loan options for undergraduate students, graduate students, law and MBA programs, health-profession programs, parents, and some international-student situations. The exact option should match who is borrowing and what program the money is funding.
Before using a private student loan, students should normally exhaust grants, scholarships, and suitable federal aid first. Federal student loans can carry borrower protections and repayment options that a private loan does not automatically reproduce.
For a dedicated breakdown of education borrowing, see SoFi student loans.
3. SoFi Student-Loan Refinancing Replaces Existing Education Debt
Student-loan refinancing creates a new private education loan that pays off eligible existing student debt. The new loan can change the interest rate, repayment term, monthly payment, or all three, so the right comparison is the new total borrowing cost against the loans you already have.
SoFi currently lists several refinance paths, including general student-loan refinancing, Parent PLUS refinancing, medical or dental residency refinancing, and SmartStart refinancing. Program-specific professional refinancing can also sit within the broader student-refinance family.
The major warning is federal debt. If federal student loans are refinanced into a private SoFi loan, the borrower gives up federal repayment and forgiveness benefits associated with those federal loans. That decision cannot be judged by rate alone, especially for a borrower who may need income-driven repayment, forgiveness eligibility, or other federal protections.
If your main question is whether refinancing itself makes sense, start with how student-loan refinancing works. If you are comparing lenders, the ELFI vs SoFi student-loan refinancing comparison belongs later in the decision.
4. SoFi Mortgage Loans Cover Home Purchase and Refinance
SoFi’s mortgage category includes home-purchase financing and mortgage refinancing. It also lists product branches such as cash-out refinancing, jumbo loans, FHA loans, and VA loans, subject to the borrower, property, location, and program requirements that apply to each mortgage.
A standard mortgage refinance is primarily about replacing the existing home loan. A cash-out refinance does more: it replaces the mortgage and increases borrowing so the homeowner receives part of the property’s equity as cash. Because the entire first mortgage can be repriced, a cash-out refinance should be compared with leaving the current mortgage alone and using a separate home-equity product.
For the broader refinance decision, use the mortgage refinance guide before focusing on any one lender.
5. Home Equity Loan vs HELOC: The Difference Is How You Access Equity
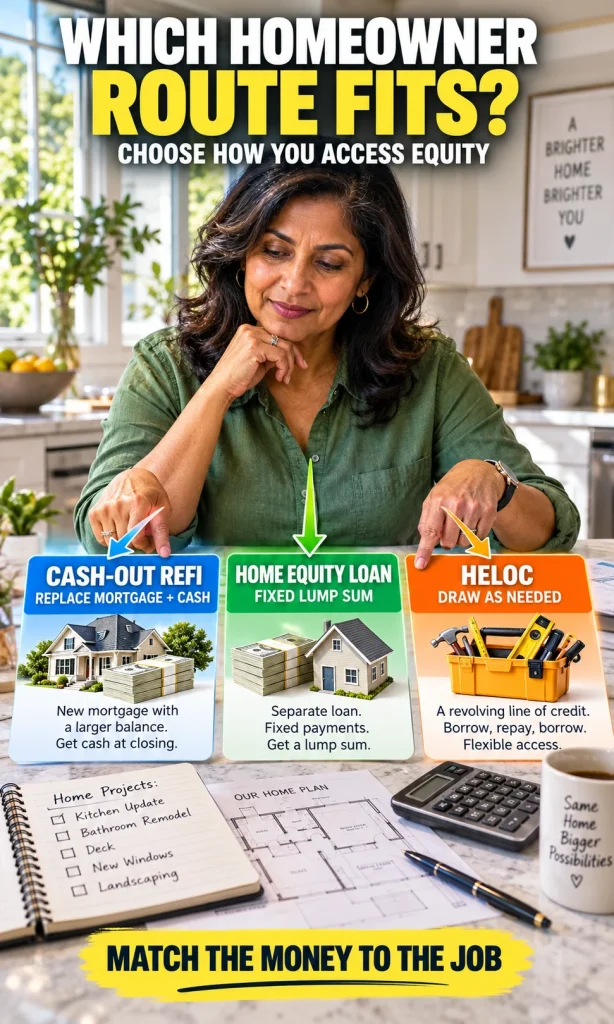
Both options use home equity, but they solve different cash-flow problems. A home equity loan is better aligned with a defined lump sum, while a HELOC is designed for repeated or staged borrowing during its draw period.
| Feature | Home equity loan | HELOC |
|---|---|---|
| How money is received | One lump sum | Draw as needed within the line rules |
| Typical rate behavior | Often fixed | Typically variable |
| Best fit | Known project or one-time expense | Staged renovation or uncertain future draws |
| Main risk | Home secures the debt | Home secures the debt and variable rates can move |
The decision is not simply “which one has the lower rate?” A borrower who needs $40,000 once has a different job from a homeowner who expects to draw money in stages over several years.
6. SoFi Auto Refinancing Is a Marketplace
SoFi’s auto-refinance experience should be described carefully. The company currently presents auto-loan refinancing through a marketplace where borrowers can compare offers from participating providers; the resulting auto loan is provided under the chosen provider’s terms rather than being a direct SoFi Bank auto loan.
That means you should compare the provider’s APR, fees, vehicle restrictions, loan term, and total interest. A lower monthly payment does not automatically mean the refinance is cheaper because extending the term can reduce the payment while increasing how long you remain in debt.
Which SoFi Loan Type Fits Which Borrower?
The cleanest way to choose is to match the financing structure to the job rather than starting with a promotional rate. A personal loan is built around unsecured lump-sum borrowing; a private student loan is built around current education costs; a student refinance replaces existing education debt; a mortgage finances or refinances property; home-equity products borrow against equity; and auto refinancing is currently a marketplace comparison experience.
- Choose a personal-loan comparison when the expense is personal, unsecured, and you know the amount you need.
- Choose private student-loan research when the money is for current eligible school costs after reviewing federal aid.
- Choose student-refinance research when the debt already exists and you understand any federal protections that could be lost.
- Choose a mortgage path when you are buying a home or replacing the first mortgage.
- Choose home equity when you already own a home and want to borrow against equity without necessarily replacing the first mortgage.
- Choose auto refinance marketplace research when your goal is specifically replacing an existing vehicle loan.
Does Checking a SoFi Rate Affect Your Credit?
SoFi states that checking rates or prequalifying for several lending products can begin with a soft credit inquiry, which does not affect the credit score in the way a hard inquiry can. If you continue with a full application, the lender may request a full credit report and hard inquiry as part of final underwriting.
That distinction is useful because prequalification can help you compare potential terms before committing to a full application. It still does not guarantee approval, the final rate, or final loan terms.
What to Compare Before You Apply
The best SoFi loan type is the one whose structure fits the job and whose final terms beat realistic alternatives. Compare the entire borrowing cost rather than one attractive number.
- APR rather than interest rate alone.
- Origination, closing, or other product-specific fees.
- Net proceeds after fees.
- Repayment term and total interest.
- Fixed versus variable rate.
- Collateral risk for mortgages and home-equity borrowing.
- Federal benefits that would be lost by privately refinancing federal student loans.
- Whether the offer comes directly from SoFi or through a marketplace provider.
For the latest product lineup and eligibility rules, verify the relevant product directly on SoFi’s official product directory before applying.
Frequently Asked Questions
Does SoFi offer different kinds of personal loans?
SoFi markets personal loans for several uses, including debt consolidation, home improvement, travel, weddings and family-planning expenses. These labels generally describe how the borrower plans to use the personal loan rather than completely separate lending products with unrelated structures.
Does SoFi offer private student loans and student-loan refinancing?
Yes. Private student loans are intended for current eligible education expenses, while student-loan refinancing replaces eligible education debt that already exists. They should not be treated as interchangeable products because the timing, purpose and borrower protections are different.
Can SoFi refinance federal student loans?
Eligible federal education debt may be refinanced into a private SoFi refinance loan, but doing so gives up federal borrower protections and access to federal repayment or forgiveness programs for the refinanced debt. Borrowers who value those protections should compare federal options before refinancing.
Does SoFi offer home equity loans and HELOCs?
SoFi currently lists both home equity loans and home equity lines of credit. A home equity loan is aligned with a defined lump sum, while a HELOC is a revolving line that can be drawn over time. Both use the home as collateral and should be compared with keeping or refinancing the existing first mortgage.
Does SoFi make auto loans directly?
SoFi currently presents auto-loan refinancing through a marketplace. The marketplace lets borrowers compare options from participating providers, and the final loan is provided under the selected provider’s terms. This is different from a direct SoFi-originated auto refinance loan.
Which SoFi loan should I choose?
Start with the financing job. Use personal-loan research for unsecured personal expenses, private student-loan research for current school costs, student refinancing for existing education debt, mortgage products for home purchase or refinance, home-equity products for borrowing against an owned property, and auto-refinance marketplace research for an existing vehicle loan. Then compare APR, fees, term, protections and total cost.
Final Checklist
- Identify whether you need new borrowing or refinancing.
- Separate personal-loan use cases from genuinely different loan products.
- Protect federal student-loan benefits when they matter to you.
- Compare home-equity borrowing with a cash-out refinance before replacing a favorable first mortgage.
- Treat auto refinance as a marketplace comparison rather than a direct SoFi loan.
- Check the current lender terms before applying because rates, fees, eligibility and product availability can change.