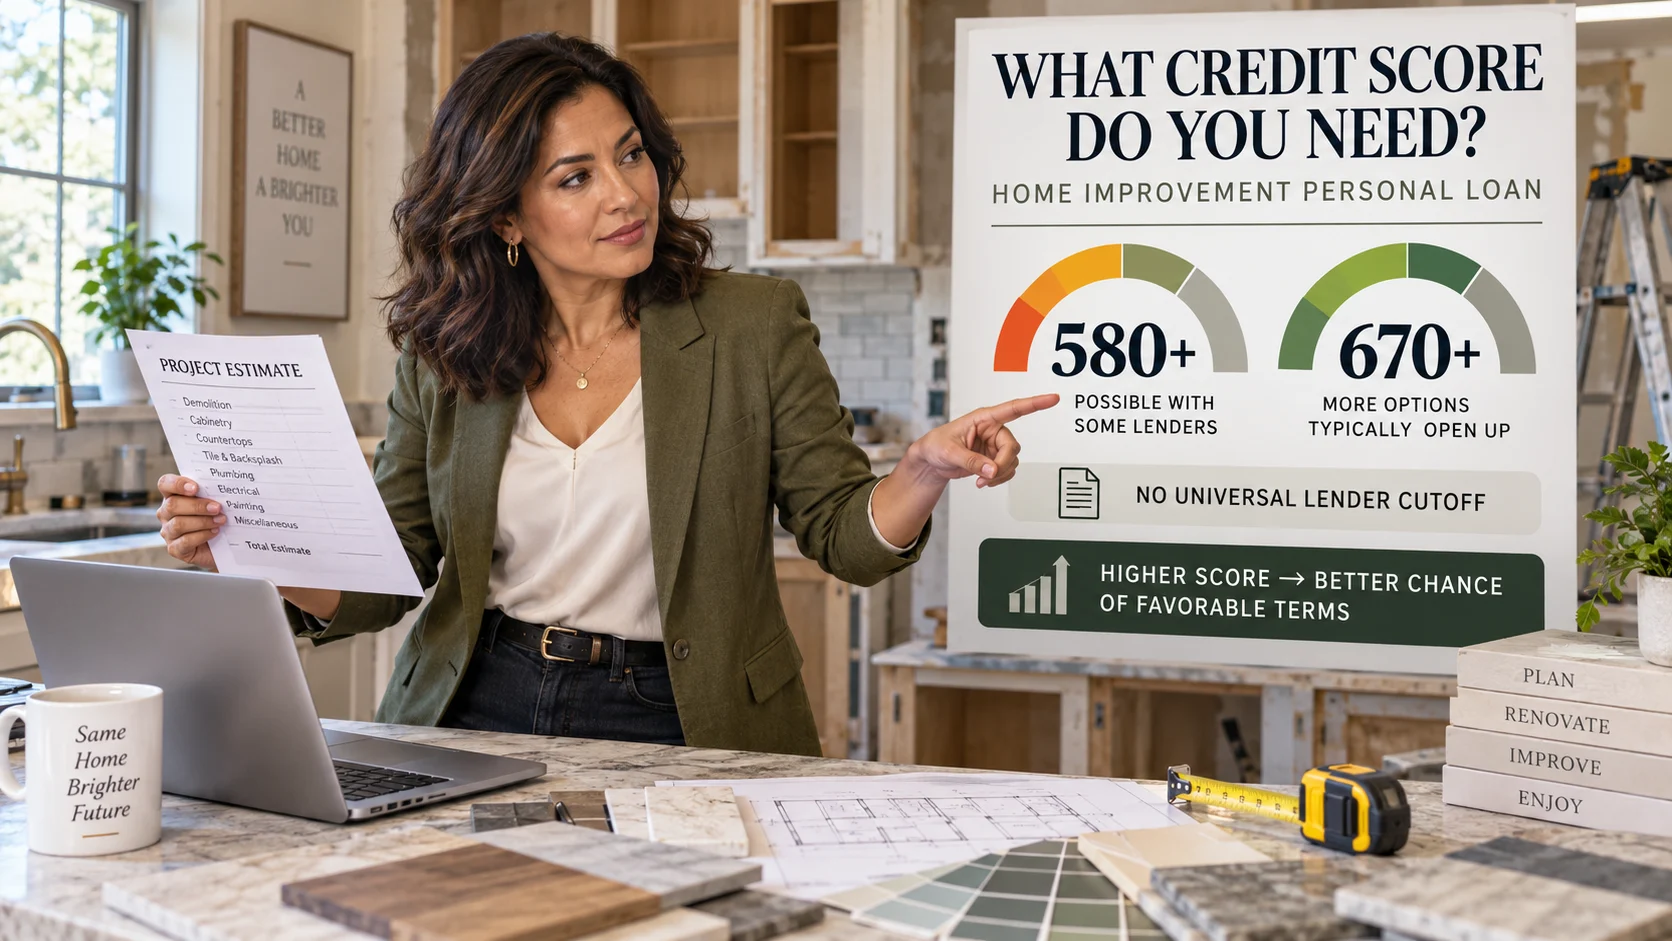
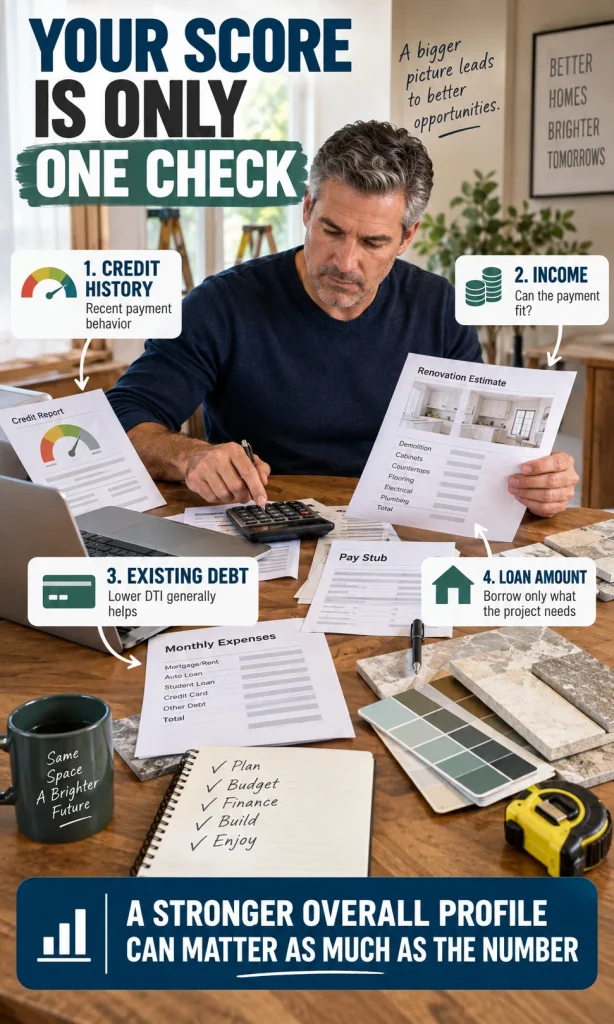
There is no single credit score that guarantees approval for a home improvement personal loan. A score around 670 or above generally puts a borrower in a stronger credit range, while borrowers in the fair-credit range can still find personal-loan options, usually with fewer choices and potentially higher borrowing costs. Your income, existing debt, requested loan amount, repayment history and the lender’s own underwriting rules can matter just as much as the number you see on a credit-score app.
A home improvement personal loan is usually an unsecured personal loan used to pay for repairs, remodeling or upgrades. Because the home normally is not pledged as collateral, the lender has to judge whether your overall financial profile is strong enough to support the new monthly payment.
There Is No Universal Minimum Credit Score
One of the most useful changes to make to the old advice is to stop treating one score, such as 660, as a universal qualification line. Different lenders use different underwriting models, some publish minimum requirements while others do not, and the credit score the lender obtains may not be identical to the score shown in a consumer app.
A borrower with a lower score can sometimes qualify because the rest of the application is strong. A borrower with a higher score can still be declined when the requested amount is large relative to income, existing debts are heavy, recent delinquencies appear on the credit report, or the lender finds another risk factor.
For planning purposes, the familiar FICO ranges are more useful as shopping context than as guaranteed personal-loan approval thresholds.
| FICO Score Range | Credit Profile | What It May Mean When Shopping |
|---|---|---|
| 740+ | Very good to exceptional | Usually a stronger position for lender choice and pricing, assuming income and debt also support the requested amount. |
| 670-739 | Good | Often provides access to a wider range of unsecured personal-loan offers, although approval and APR still depend on the whole application. |
| 580-669 | Fair | Approval can still be possible, but lender choice may narrow and the cost of borrowing can become much more important. |
| Below 580 | Poor | Unsecured approval may be difficult or expensive. Improving the application, reducing the amount requested or delaying non-urgent work may be more valuable than accepting a very costly loan. |
These ranges describe credit profiles, not lender promises. Two borrowers with the same score can receive very different decisions because their incomes, debts, credit histories and requested amounts are different.
Your Credit Score Is Only One Part of the Approval Decision
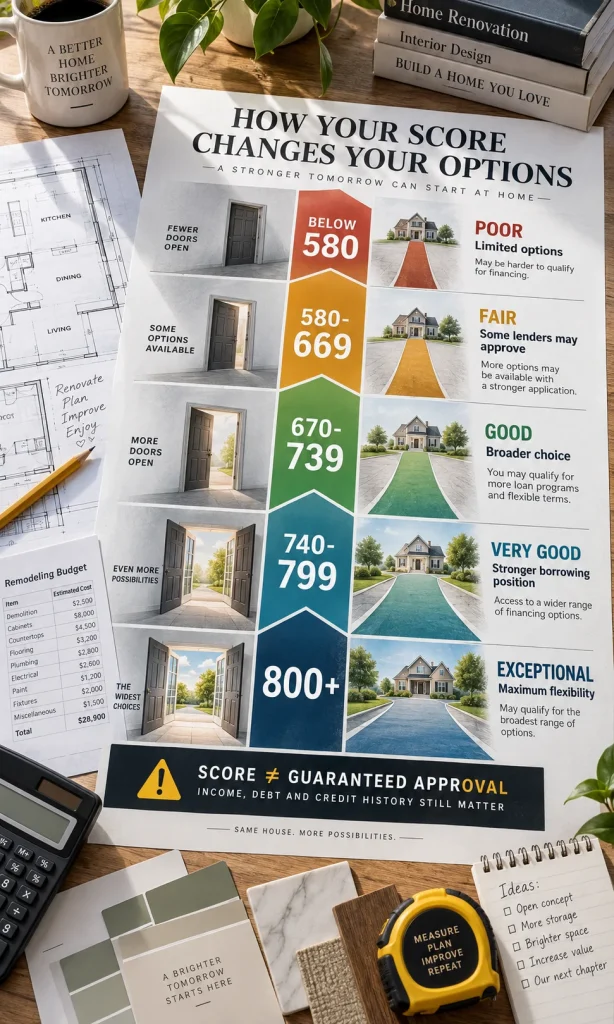
Credit scores summarize information in your credit history, but lenders still need to determine whether the proposed payment is realistic for your finances. That is why focusing exclusively on reaching a particular score can lead to disappointment.
The main factors commonly affecting an unsecured home improvement personal-loan application include:
- Credit score and credit history: missed payments, collections, recent applications and the amount of revolving credit already being used can all matter.
- Income: the lender needs enough evidence that the new payment can be supported.
- Existing monthly debt: large credit-card, auto, student-loan or other debt payments reduce the income available for another loan.
- Debt-to-income ratio: lenders may use the relationship between monthly debts and gross income when evaluating repayment capacity.
- Requested amount: qualifying for $8,000 of renovation financing can be easier than qualifying for $40,000 under the same financial profile.
- Loan term: a longer term can lower the required monthly payment but may increase the total interest paid.
- Recent financial events: delinquencies, collections, bankruptcy or several recent credit applications can affect the decision.
The important question is therefore not simply, “Is my score high enough?” It is “Does my complete application support this particular loan amount and payment?”
Calculate Your Debt-to-Income Ratio Before Applying
Debt-to-income ratio, usually shortened to DTI, compares your required monthly debt payments with your gross monthly income.
The basic calculation is:
Monthly debt payments ÷ gross monthly income × 100 = DTI
Suppose a borrower earns $6,000 per month before taxes and currently has $2,000 in monthly debt obligations. Their DTI is approximately 33%.
If a proposed home improvement loan would add another $500 monthly payment, the same borrower’s monthly obligations would rise to $2,500, producing a DTI of about 42%.
There is no one DTI limit shared by every personal-loan lender, but the example shows why the requested amount matters. The same credit score can look much stronger when the proposed payment fits comfortably within the borrower’s income.
Loan Size Can Matter More Than Homeowners Expect
Imagine two borrowers with similar income and credit profiles. One needs $7,500 to replace an aging water heater and repair damaged flooring, while the other requests $45,000 for a full kitchen and bathroom renovation.
The lender is not evaluating the same risk simply because both applications say “home improvement.” The second borrower needs to demonstrate the ability to support a much larger payment or a much longer repayment period.
This is why you should build the renovation budget before you apply. Separate the work into:
Must do now
Should do soon
Would like to do
A smaller loan covering urgent work may produce a much healthier financial structure than borrowing enough for every desirable upgrade at once.
If you are still deciding which improvements deserve priority, the home improvements that can add practical value can help you separate projects that solve a real housing problem from upgrades that can reasonably wait.
How Much Does Income Matter?
A high credit score does not repay the loan by itself. The lender still needs to see that your income and existing obligations leave enough room for the new payment.
Depending on the lender and application, you may be asked for items such as pay statements, tax documentation, bank information, proof of identity or other evidence needed to verify the financial information you provided.
Self-employed borrowers may have a different documentation experience because income can be less uniform from month to month. The key is consistency: enter information accurately and be prepared to support it if the lender requests verification.
Do not inflate income, omit debts or guess at figures to make the application look stronger. A loan that only works when the application numbers are stretched is usually a poor fit for the household budget anyway.
Can You Qualify With Fair or Bad Credit?
Possibly, but the question should quickly move from “Can somebody approve me?” to “Is the offer affordable enough to accept?”
An approval with a very high APR and a large origination fee can make a relatively modest remodeling project surprisingly expensive. The fact that funding is available does not mean taking it improves your financial position.
If your credit is weak, concentrate on four levers before submitting full applications.
1. Reduce the Amount You Need
If $20,000 produces an uncomfortable payment, determine whether the urgent phase of the project can be completed for $10,000 or $12,000 instead. A smaller request reduces both the lender’s exposure and your own repayment burden.
2. Improve Credit-Card Utilization Before Applying
Paying down revolving balances can strengthen the credit profile used by scoring models, especially when cards are carrying a high proportion of their limits. Allow enough time for updated balances to be reported rather than expecting a payment made tonight to change every score tomorrow.
3. Correct Genuine Credit-Report Errors
Review the underlying reports rather than relying only on a score. An inaccurate late payment, balance or account can affect the credit information on which lending decisions are based.
4. Consider a Co-Borrower Only When the Lender Allows One
Some lenders allow joint applications and some do not. A stronger co-borrower can improve the overall application in certain cases, but both borrowers become responsible for the debt, so this should never be treated as a cosmetic way to “borrow somebody else’s score.”
Prequalify Before Submitting Several Full Applications
When a lender offers prequalification using a soft credit inquiry, it can be useful for checking potential terms without immediately making a full application. Read the lender’s disclosure carefully because the word “prequalified” does not mean approved, and the final offer can change after the lender verifies the application.
A full credit application commonly results in a hard credit inquiry. That does not mean you should avoid comparison shopping, but it does mean you should understand what kind of inquiry will be used before entering the final application stage.
The goal is to narrow your choices first. Once you identify a small number of plausible offers, compare their complete costs rather than applying indiscriminately across a long list of lenders.
Compare APR, Not Just the Advertised Interest Rate
The interest rate tells you how interest is charged on the borrowed amount. APR is designed to reflect the interest rate together with certain loan fees, making it more useful when comparing borrowing costs.
Origination fees deserve particular attention. Some personal-loan lenders deduct the fee from the amount funded rather than adding it separately.
For example, imagine you are approved for a $20,000 loan with a 5% origination fee deducted from the proceeds. A 5% fee equals $1,000, so only $19,000 may reach you even though the loan obligation began at $20,000.
That creates a practical renovation problem when the contractor invoice is $20,000. Before accepting an offer, confirm:
- amount borrowed;
- amount actually deposited;
- APR;
- monthly payment;
- repayment term;
- origination fee;
- late-payment terms;
- prepayment terms;
- total scheduled repayment.
A loan can have the smallest monthly payment and still be the more expensive choice because the repayment period is much longer.
Personal Loan vs Home Equity Loan vs HELOC
A home improvement personal loan should not be confused with borrowing against home equity. The risk structure is fundamentally different.
| Financing Type | Uses Home as Collateral? | Often Better Suited To | Main Trade-Off |
|---|---|---|---|
| Personal loan | Usually no | Defined projects where the homeowner wants fixed installment payments without pledging the house. | Unsecured borrowing can be expensive when credit is weak. |
| Home equity loan | Yes | Larger one-time projects when sufficient equity exists and a lump sum is needed. | The house secures the debt, so failure to repay carries much more serious collateral risk. |
| HELOC | Yes | Projects that will be paid in stages and need flexible access to funds. | Rates are commonly variable and the home secures the line. |
| Cash-out refinance | Yes | Situations where replacing the entire first mortgage also makes financial sense. | The homeowner reprices the existing mortgage balance as well as the new cash being borrowed. |
Do not assume that weak credit automatically makes home-equity borrowing easier. Home equity solves the collateral side of the financing structure, but lenders still evaluate creditworthiness and repayment capacity, and the consequences of default are much more serious when the house secures the debt.
If you are considering replacing your first mortgage to release renovation cash, read the mortgage refinance guide first and compare the replacement mortgage rather than looking only at the amount of cash received. The mortgage refinance calculator can then help compare the payment, costs and break-even consequences.
When an Unsecured Personal Loan Fits Home Improvement Well
A personal loan becomes particularly practical when the project has a clear budget, you do not want to put the house behind the debt, and you can repay the balance over a relatively short period without stretching the household budget.
Typical examples can include:
- replacing an HVAC system;
- repairing a roof;
- fixing water damage after the cause has been addressed;
- replacing unsafe electrical components;
- remodeling one bathroom;
- completing a smaller kitchen update;
- improving accessibility;
- replacing damaged flooring.
The financing decision becomes weaker when the project budget is still changing dramatically. Borrowing the maximum amount offered “just in case” means paying interest on money that might never have been necessary.
Do Not Schedule the Contractor From a Prequalification Screen
A prequalification result is not the same as final funding. The lender may still verify income, identity, credit information and other application details before issuing the loan.
Do not commit to a non-refundable contractor deposit solely because an online screen says you appear eligible for a certain amount. The safer sequence is to obtain the project quote, compare financing, complete the required approval process and understand when the money will actually be available before locking yourself into a payment obligation to the contractor.
The same principle applies to materials. An expiring tile sale or appliance promotion should not pressure you into accepting an unsuitable loan.
How to Improve Your Approval Position Before Applying
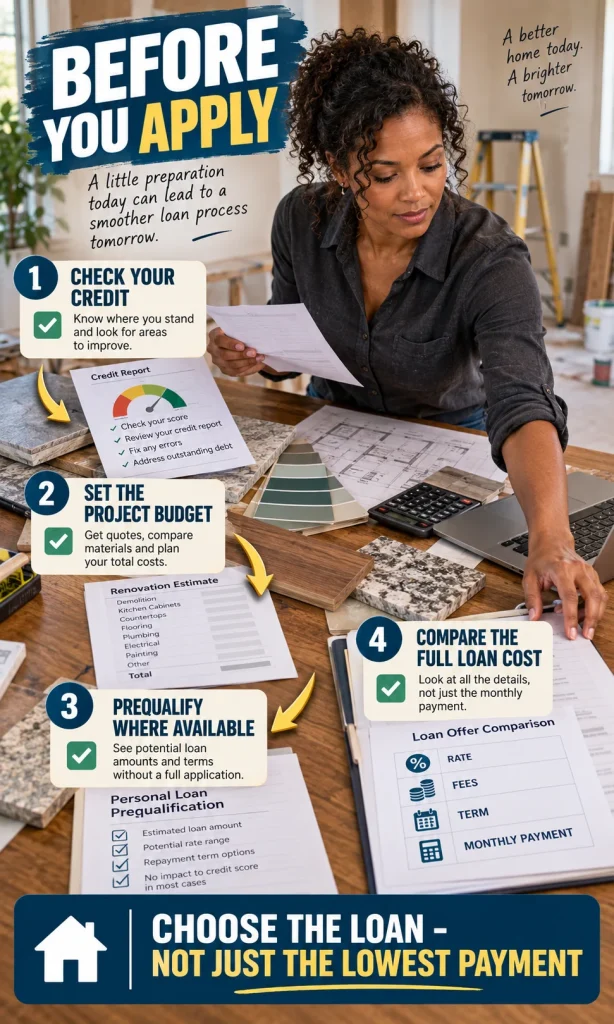
When the project can wait for a few weeks or months, improving the application can be more valuable than searching harder for a lender willing to accept a weak one.
Start with the factors you can realistically change:
- Check all three credit reports for incorrect information.
- Bring late accounts current where possible.
- Reduce high revolving balances.
- Avoid opening unnecessary new credit accounts before applying.
- Calculate your current DTI using accurate monthly obligations.
- Reduce the requested project amount if the renovation can be phased.
- Build a small project contingency into the budget rather than borrowing without a cost estimate.
- Compare prequalification options before submitting several complete applications.
Do not pay a company simply because it promises to “erase” accurate negative credit information immediately. Legitimate credit improvement usually comes from correcting genuine errors and building stronger payment and balance behavior over time.
Should You Borrow for a Project That Adds Home Value?
A project can improve the property without producing a dollar-for-dollar return. That distinction matters because a loan has a contractual repayment cost, while the future resale value of an improvement is uncertain.
Borrowing for a leaking roof is fundamentally different from borrowing for a luxury finish upgrade. The roof may protect the structure from further damage even if it never generates a glamorous resale calculation; the luxury upgrade may look attractive while creating little financial benefit relative to its cost.
For discretionary improvements, compare:
Project cost + financing cost
against
the value the project adds to your use of the home
and
the realistic period you expect to remain in the property.
Not every sensible renovation has to produce a profit, but the borrower should know whether the decision is primarily about property protection, quality of life or potential resale value.
How Much Should You Borrow?
Start with a contractor estimate or a realistic materials-and-labor budget. Then separate the total project price from the amount that actually needs financing.
For example, if the renovation costs $18,000 and you can comfortably contribute $5,000 without depleting your emergency savings, the financing need may be closer to $13,000 than $18,000.
Borrowing less can improve several parts of the decision at once. It can reduce the monthly payment, reduce total interest, lower the lender’s exposure and make it easier to finish repayment before the improvement itself needs another major update.
Do not drain every dollar of savings merely to reduce the loan, however. A home renovation is exactly the kind of period when unexpected plumbing, electrical, structural or material costs can appear.
What Documents Should You Prepare?
Requirements vary, but preparing the common information before you apply can make the process much smoother.
Have accurate records of:
- identification;
- address and contact information;
- employment or income information;
- housing payment;
- existing debts;
- requested loan amount;
- bank details if required for funding;
- project budget or estimate for your own planning.
An unsecured personal loan may not require the same property documentation as a mortgage or home equity transaction. That can make it operationally simpler, but the simpler application should not distract from the cost of the debt.
What If You Are Declined?
A decline does not automatically mean you should immediately submit another five applications.
Find out what weakened the application. Depending on the situation, the problem may be credit history, insufficient income relative to the requested payment, excessive debt, a very large requested amount, limited credit history or another lender-specific condition.
Then decide whether the problem can actually be changed.
If the renovation is urgent, consider whether the work can be reduced to the safety-critical portion. If the project is cosmetic, delaying the project while improving the financial profile can be considerably cheaper than accepting expensive credit simply because it is available today.
The Approval Amount Is Not Your Renovation Budget
One of the easiest borrowing mistakes is allowing the lender’s maximum offer to become the project budget.
If you need $12,000 and the lender says you qualify for $25,000, you have not suddenly discovered an additional $13,000 of affordable renovation. You have discovered additional debt capacity.
Build the project first and size the borrowing to it. This keeps the financing decision tied to the improvement rather than allowing available credit to enlarge the project unnecessarily.
Frequently Asked Questions
What credit score do I need for a home improvement personal loan?
There is no universal minimum score shared by every lender. A good credit profile generally gives you more options and potentially better pricing, while fair-credit borrowers can still qualify with some lenders. Income, existing debt, credit history, requested loan amount and the lender’s underwriting model can all change the result.
Can I get a home improvement personal loan with a 600 credit score?
It can be possible because 600 falls within the broad fair-credit range rather than creating an automatic industry-wide rejection. The important issue is what loan amount, APR, fees and monthly payment are actually offered. A smaller request, manageable debt load and stable income can produce a stronger application than the score alone suggests.
Is 660 enough for a home improvement loan?
A 660 score can be sufficient for some personal-loan lenders, but it should not be described as a universal minimum or guaranteed approval score. It sits within the fair FICO range, so pricing and eligibility can vary substantially according to the rest of the application.
Does a home improvement personal loan use my house as collateral?
A conventional home improvement personal loan is usually unsecured, so the house is not normally pledged as collateral. A home equity loan or HELOC is different because it is secured by home equity, which means nonpayment can put the property at risk. Always confirm the specific contract because a lender can offer secured and unsecured products under different names.
Will checking personal-loan offers hurt my credit score?
Checking your own credit does not lower your score, and some lenders can show prequalification possibilities through a soft inquiry. A formal credit application commonly involves a hard inquiry, so confirm the lender’s process before applying and narrow your choices before submitting several full applications.
Is a HELOC better than a personal loan if my credit is poor?
Not automatically. A HELOC uses your home as collateral and still has lender qualification requirements, while its interest rate is commonly variable. It can make sense for a qualified homeowner who needs funds in stages, but weak credit alone is not a reason to convert an unsecured renovation expense into debt secured by the home.
Should I choose the personal loan with the lowest monthly payment?
Not without comparing the APR, origination fee, term and total scheduled repayment. A longer term can produce a smaller monthly payment while substantially increasing the time you remain in debt and the total interest you pay. Compare offers using the same borrowing amount whenever possible.
Next Steps
Check your credit reports, calculate your current monthly debt obligations and build a realistic project budget before asking a lender how much you can borrow. Those three numbers will tell you far more about the strength of the decision than searching for one supposedly universal credit-score cutoff.
Then compare only loans that can fund the amount you actually need. Judge the offers by APR, fees, net proceeds, monthly payment and total repayment, and compare unsecured borrowing against home-equity financing only after you understand the additional collateral risk.
A home improvement loan should solve the renovation problem without creating a larger financial one.